ASX 200 Live Today - Friday, 2nd October
The S&P/ASX 200 is set to bounce after Thursday's broad-based selloff and a pullback in bond yields overnight. Here are today's top stories.
Today’s ASX 200 Updates
Welcome to our live ASX coverage for Friday, October 2. Expect a high volume of posts pre-market and more periodic updates throughout the day. We'll be wrapping the blog up around 2:00 pm AEST. Let us know how we can make it even better.
ASX bounces but ends the week flat as oil and yields stay in focus
[2:00 pm] That's a wrap! The ASX 200 is up 47 points (+0.55%) in a small oversold bounce after Thursday's carnage, leaving the index flat for the week after rallying as much as 1.6% midweek. Brent crude has added more than 6% over the past two sessions on reports the US is sending an additional aircraft carrier to the Middle East. On the flip side, the policy-sensitive Australian 3-year yield is starting to roll over, down 13 basis points over the past four sessions to 4.922%.The closing commentary is much the same as it's been for the past few days. The market has come off a Tuesday-Wednesday relief rally and a Thursday tumble, and is still looking for more evidence that yields and oil prices have peaked.
Here's a look at this week's best performers, most of which have had fairly meaty announcements. Codan and Data#3 delivered trading updates, DroneShield and Megaport landed contract wins, and Northern Star is in takeover talks.
Ticker | Company | 1 Week | Price | 1 Week | YTD |
|---|---|---|---|---|---|
CDA | Codan | 27.7% | $67.21 | 27.7% | 136.5% |
DTL | Data#3 | 21.3% | $13.71 | 21.3% | 52.8% |
DRO | Droneshield | 13.4% | $1.83 | 13.4% | -40.7% |
NST | Northern Star Resources | 10.1% | $24.13 | 10.1% | -1.8% |
MP1 | Megaport | 9.5% | $21.56 | 9.5% | 90.0% |
4DX | 4Dmedical | 9.1% | $4.42 | 9.1% | 10.5% |
LLC | Lendlease Group | 7.2% | $2.62 | 7.2% | -49.7% |
INA | Ingenia Communities Group | 6.7% | $4.77 | 6.7% | -8.3% |
EOS | Electro Optic Systems | 6.5% | $11.40 | 6.5% | 20.8% |
SEK | Seek | 6.0% | $11.95 | 6.0% | -48.7% |
Meanwhile, the decliners have largely centred on high-beta resources like lithium and uranium, along with Centuria Capital on its exposure to Bathla.
Ticker | Company | 1 Week | Price | 1 Week | YTD |
|---|---|---|---|---|---|
LTR | Liontown | -17.5% | $0.80 | -17.5% | -49.0% |
VUL | Vulcan Energy Resources | -16.9% | $1.70 | -16.9% | -61.6% |
ELV | Elevra Lithium | -13.7% | $5.26 | -13.7% | -34.6% |
DYL | Deep Yellow | -13.7% | $1.11 | -13.7% | -39.9% |
IPX | Iperionx | -13.4% | $2.42 | -13.4% | -56.2% |
KAR | Karoon Energy | -11.9% | $1.56 | -11.9% | 1.0% |
LYC | Lynas Rare Earths | -9.6% | $12.82 | -9.6% | 3.3% |
COH | Cochlear | -8.3% | $128.89 | -8.3% | -50.6% |
CNI | Centuria Capital Group | -7.2% | $1.17 | -7.2% | -41.7% |
ARF | Arena Reit | -7.1% | $2.02 | -7.1% | -43.4% |
UBS trims Lynas target after Meteoric acquisition
[1:36 pm] UBS has cut its Lynas target by 7% to $21 and retained a Buy rating, viewing the all-scrip Meteoric Resources acquisition as initially about securing heavy rare earths supply for its expanding Malaysian refining capacity.
Deal terms offer 0.0207 Lynas shares per Meteoric share, implying a $968m equity value and a 57.6% premium to the 30-day VWAP, with implementation targeted for March 2027
Caldeira in Brazil's Minas Gerais is the largest known ionic clay JORC rare earths resource outside China, at 1,631Mt grading 2,317ppm TREO, including 802kt NdPr and 41kt DyTb
DFS outlines average production of 12,500tpa TREO, including 3,862tpa NdPr and 127tpa DyTb, over a 23-year mine life, with US$498m of upfront capex
Heavy rare earths revenue is forecast at about 20% of group revenue from FY28, as Caldeira helps fill the expanded heavy rare earths refining capacity at LAMP
~20kt NdPr equivalent of upstream supply across Kalgoorlie, LAMP and Caldeira leaves separation and western magnet demand as the bottlenecks, the broker estimates
Company page: Lynas Rare Earths (LYC)
Tech on track for best week since August
[1:26 pm] The S&P/ASX 200 Tech Index is up 3.2%, and tracking 6.0% higher for the week, but only just coming off a six-month low. It's been a catalyst-rich week for tech names. Codan has surged about 30% this week to fresh all-time highs, overtaking WiseTech as the market's largest tech stock. Data#3 made a similar move on the back of a 1H27 guidance update, while Praemium rallied today after its CEO resigned, which tells you plenty about how the market rated the outgoing boss.
Ticker | Company | % Chg | Price | 1 Week | YTD |
|---|---|---|---|---|---|
HSN | Hansen Technologies | 9.1% | $3.41 | 9.5% | -35.5% |
PPS | Praemium | 8.2% | $0.60 | 6.2% | -25.2% |
DTL | Data#3 | 8.1% | $13.65 | 20.8% | 52.2% |
360 | Life360 | 7.3% | $20.45 | 6.1% | -36.5% |
MP1 | Megaport | 7.0% | $21.67 | 10.0% | 90.9% |
NXL | Nuix | 5.3% | $1.90 | 1.6% | 4.7% |
WTC | Wisetech Global | 4.9% | $32.87 | 2.4% | -52.0% |
ZIP | Zip Co | 3.8% | $2.07 | 2.0% | -36.7% |
TNE | Technology One | 3.5% | $30.24 | 4.3% | 9.7% |
SDR | Siteminder | 3.0% | $2.71 | 1.9% | -55.8% |
OCL | Objective Corporation | 2.9% | $5.99 | 3.3% | -63.8% |
XRO | Xero | 2.3% | $56.60 | -2.6% | -50.3% |
WBT | Weebit Nano | 2.3% | $3.80 | 4.5% | -24.1% |
MAQ | Macquarie Technology Group | 2.0% | $53.84 | -2.1% | -19.6% |
CAT | Catapult Sports | 1.9% | $3.24 | 3.2% | -22.1% |
IRE | Iress | 0.9% | $5.41 | 0.6% | -35.4% |
BVS | Bravura Solutions | 0.6% | $3.11 | -1.3% | 21.0% |
CDA | Codan | 0.1% | $67.55 | 28.3% | 137.7% |
IFT | Infratil | -0.1% | $11.19 | -3.9% | 16.8% |
NXT | NextDC | -0.2% | $10.58 | -5.7% | -14.1% |
DDR | Dicker Data | -0.4% | $15.40 | -0.5% | 49.6% |
AD8 | Audinate Group | -0.4% | $2.29 | 0.0% | -43.6% |
DGT | Digico Infrastructure Reit | -2.6% | $2.46 | 1.9% | -12.0% |
PME | Pro Medicus | -2.8% | $156.62 | -3.9% | -29.0% |
Macquarie downgrades Lindian, cuts lithium targets
[12:50 pm] Macquarie has trimmed its spodumene forecasts and cut targets across most of its lithium coverage, while downgrading Lindian Resources to Underperform on risks to its Kangankunde expansion.
Spodumene forecasts cut 1-5% across CY26-CY28 on a softer medium-term price outlook, driving earnings downgrades led by PLS, IGO and Liontown
Lithium target cuts take PLS to $5.50 from $6.00, IGO to $9 from $9.50, Liontown to $1.25 from $1.50, Elevra to $11.50 from $12.50 and Wildcat to $0.80 from $0.90, all retaining Outperform
Global Lithium downgraded to Neutral after strong share price performance, despite a target lift to $1.15 from $0.85
NdPr prices up ~30% year-to-date, though Lynas's target falls to $19 from $20 and Iluka's to $7.20 from $8, with both retaining Outperform
Lindian downgraded to Underperform with a target cut to $0.50 from $0.75, after the broker removed the Kangankunde stage 2 expansion on regulatory and state equity risks
Nickel Industries target cut to $1.20 from $1.25, with CY27 EPS lifted 14% but cuts of 16-26% from CY28 as rising Indonesian capacity weighs
Jera doesn't see Qatar LNG returning soon
[12:49 pm] Japan's Jera, the world's largest LNG buyer, expects Strait of Hormuz disruptions to keep Qatari supply off the market heading into the northern winter.
Jera CEO Yukio Kani said "we don't expect Qatar LNG coming back to the market soon", with market participants worried about the coming winter
Spot LNG prices are double year-ago levels after hitting their highest since late 2022 last month
Qatar was the world's second-largest LNG supplier before the war, with the Middle East accounting for about a fifth of global supply
LNG transit through Hormuz rose in September to its highest since the war began, but remains 80% below February levels, according to Kpler
Force majeure has been extended by Qatar to November for long-term Asian customers and December for Europe
Europe's seasonally low gas storage and the EU ban on Russian LNG imports from January suggest spot prices will rise further, according to Kani
Source: Bloomberg
Data#3 runs for a second day
[11:50 am] Data#3 is up 8.9% to $13.76, notching a second straight day of all-time highs. The stock surged 13.6% on Thursday after a better-than-expected 1H27 trading update, which was oddly released at 12 pm AEST. Key numbers included:
1H FY27 gross profit up more than 15% to above $165.5m vs $164.5m ests (at least 1% beat)
1H FY27 PBT up more than 40% to above $46.9m vs $39.1m ests (at least 20% beat)
One-off larger transactions, stronger Infrastructure and Software Solutions activity and the timing of planned investment spend are lifting the half, along with about $1.5m of above-expectation interest income
FY27 PBT now expected to be skewed to 1H, vs ests that had 2H PBT of $49.0m ahead of 1H's $39.1m
Business update due at the AGM on 28 October, with 1H results and the interim dividend on 22 February 2027
The sustained buying is likely off a mix of a surprise trading update at noon plus the analyst upgrades that followed, given the magnitude of the beat (e.g. Jarden upgraded to Neutral from Underweight this morning, lifted its target by 23% to $12.10).
Australia-US 10-year yield gap nears zero
[11:34 am] Australia's 10-year bond yield is poised to fall below its US counterpart for the first time in over a year as RBA and Fed policy expectations diverge.
Spread narrowed to about 12bp between 10-year Australian bonds and Treasuries, hovering around its smallest since September 2025
Rate hike pricing shows traders expecting three more quarter-point Fed hikes over the next 12 months, against just one from the RBA
August inflation cooled, while RBA Governor Michele Bullock expressed "hope" that this year's four rate hikes will be enough to contain price pressures
Australian government bonds returned -1% in September, outperforming a 2.2% slide in Treasuries
NAB's Kenneth Crompton has a base case of spread inversion during 2027 but says it could happen now, with a retest of -20bp possible by the end of next year
Barrenjoey and Westpac expect Australian and US 10-year yields to converge in the coming months
Source: Bloomberg
Firmus seeks $43.7bn valuation in ASX IPO
[11:30 am] Nvidia-backed data centre operator Firmus Grid is seeking a $43.7bn valuation in its ASX IPO, which is shaping up as one of the largest in Australian history.
IPO price fixed at $11 per share, with the company looking to raise at least US$5bn
Bookbuild opens on 6 October and closes on 9 October unless accelerated, ahead of a targeted ASX debut on 23 October
US$2bn in commitments were secured in August from investors including Jane Street, Blackstone and Nvidia, following a US$505m Coatue-led round in April
Joint lead managers are Bank of America Securities, JPMorgan, Morgan Stanley and Morgans
Source: Bloomberg
ASX claws back some ground as tech and energy rebound
[10:40 am] The ASX 200 is up 32 points, or 0.38%, a modest bounce after Thursday's 175-point (1.99%) selloff. Tech is leading the way on some strong catalyst-driven moves and is now up 3.2% for the week. Most software names are tracking higher, but the heavy lifting has come from Codan and Data#3, which have rallied 30% and 24.4% respectively this week after above-consensus trading updates. Energy is also bouncing after yesterday's 3% tumble, with Brent crude back above US$100 a barrel on reports the US may deploy another aircraft carrier and 10,000 sailors and Marines to the Persian Gulf. Still, a small bounce offers little consolation after yesterday's carnage.
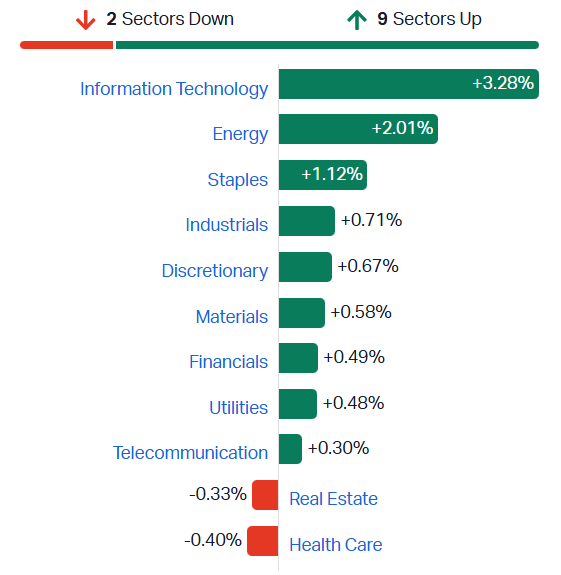
S&P/ASX 200 sectors (Source: Market Index)
Large cap banks and miners edge slightly higher
[10:30 am] The market's largest names have opened slightly higher, with Westpac, NAB, ANZ, CSL and Woodside clawing back some ground after falling around 3% on Thursday.
Ticker | Company | % Chg | Price | 1 Week | YTD |
|---|---|---|---|---|---|
BHP | BHP Group | 0.8% | $60.75 | 0.5% | 33.4% |
CBA | Commonwealth Bank | 0.1% | $149.83 | 0.3% | -6.7% |
RIO | Rio Tinto | 0.6% | $163.78 | -0.5% | 11.6% |
NAB | National Australia Bank | 0.6% | $38.11 | -0.1% | -9.9% |
WBC | Westpac | 0.4% | $34.03 | -0.3% | -11.6% |
ANZ | ANZ Group | 0.2% | $37.27 | -0.4% | 2.2% |
MQG | Macquarie Group | -0.7% | $244.10 | 1.7% | 20.2% |
CSL | CSL | -1.0% | $176.42 | -1.3% | 1.7% |
WES | Wesfarmers | 0.1% | $75.77 | 3.1% | -6.7% |
WDS | Woodside Energy G | 1.4% | $31.32 | -1.5% | 32.0% |
Top ASX 200 gainers
[10:26 am] It's not often you see a long list of tech names top the leaderboard, with bounces for battered names like Life360 and Wisetech, while Data#3 continues to rally off the back of yesterday's 1H27 guidance upgrade. Miners including lithium and coal also catch a bid after yesterday's broad-based selloff.
Ticker | Company | % Chg | Price | 1 Week | YTD |
|---|---|---|---|---|---|
DTL | Data#3 | 9.4% | $13.82 | 22.3% | 54.1% |
DRO | Droneshield | 6.7% | $1.83 | 13.7% | -40.6% |
MP1 | Megaport | 6.2% | $21.50 | 9.2% | 89.5% |
360 | Life360 | 5.1% | $20.03 | 3.9% | -37.8% |
TWE | Treasury Wine Estates | 4.7% | $5.65 | 4.3% | 7.5% |
LTR | Liontown | 4.1% | $0.82 | -15.3% | -47.6% |
XRO | Xero | 3.9% | $57.44 | -1.1% | -49.6% |
PLS | PLS Group | 3.8% | $3.79 | -2.6% | -9.8% |
WTC | Wisetech Global | 3.8% | $32.54 | 1.4% | -52.5% |
WHC | Whitehaven Coal | 3.7% | $7.63 | 1.2% | -1.8% |
Top ASX 200 losers
[10:26 am] An odd mix of REITs, gold and agriculture names lag in early trade.
Ticker | Company | % Chg | Price | 1 Week | YTD |
|---|---|---|---|---|---|
ELD | Elders | -3.3% | $6.12 | -4.8% | -10.7% |
NWH | NRW | -2.2% | $7.85 | -0.6% | 57.0% |
LLC | Lendlease Group | -2.2% | $2.66 | 9.0% | -48.8% |
TLX | Telix Pharmaceuticals | -2.0% | $15.29 | -3.4% | 35.9% |
SOL | Washington H. Soul | -1.6% | $45.02 | -6.1% | 21.0% |
PNR | Pantoro Gold | -1.4% | $2.91 | 0.3% | -40.6% |
GNC | Graincorp | -1.4% | $6.56 | -1.2% | -9.0% |
PME | Pro Medicus | -1.2% | $159.09 | -2.4% | -27.9% |
CYL | Catalyst Metals | -1.2% | $5.73 | -2.7% | -22.4% |
CHC | Charter Hall Group | -1.1% | $18.06 | 1.0% | -26.2% |
Macquarie upgrades Rio Tinto, stays cautious on copper
[9:51 am] Macquarie has upgraded Rio Tinto to Outperform as a relative call against BHP, while staying cautious on policy-supported copper and reiterating its Outperform on Fortescue.
Rio Tinto has lagged BHP by about 20% year-to-date while offering iron ore leverage and copper growth from the Oyu Tolgoi underground ramp-up
CMRG is China Mineral Resources Group, the state-backed centralised buyer of iron ore
BHP retained at Neutral, trading at about 7x one-year forward EBITDA at spot vs about 5x for Rio, leaving less room for a policy-driven copper price reversal
CMRG negotiations are a risk for Rio, though the broker expects resolution in the near term, with any additional discount likely applied to all seaborne suppliers to China
Fortescue is reiterated as a counter-consensus trade and the cleanest large-cap exposure to an expected near-term iron ore recovery on cost support
Iron ore benchmark prices are down more than 10% year-to-date, with higher freight pushing FOB netbacks lower and prompting some marginal supply cuts
Copper is being supported by Section 232 tariff uncertainty despite a forecast refined market surplus, with CY27 assumptions cautious relative to spot
OFX investigates cybersecurity incident involving client data
[9:25 am] OFX is investigating a cybersecurity incident involving unauthorised access to data, including some client data, though it has found no access to client accounts or funds so far.
No financial loss to clients has been identified based on information available to date
Services and systems continue to operate normally, with containment actions implemented
Number of affected clients is still being determined, with those affected to be contacted directly once confirmed
Identity documents do not appear to have been accessed, and none of the data accessed appears usable to make a payment on the platform
Non-client data may also have been accessed, including information on job applicants
Regulators notified include the Australian Cyber Security Centre and the Office of the Australian Information Commissioner, along with other global authorities
Company page: OFX Group (OFX)
Stakk signs $12.95m Candescent contract
[9:22 am] Stakk has signed a five-year US$9 million (~A$12.95m) contract with US banking technology provider Candescent through its subsidiary ParaScript, with its technology already live.
Annual revenue of US$1.8m (~A$2.59m) through to 31 December 2030, with support included throughout the term
FY27 revenue is expected to land modestly above Stakk's $55m milestone with the contract's contribution, which should be significant for FY28
Candescent serves more than 1,300 banks and credit unions representing over 30m registered users
Rollout complete with Stakk's AI-powered cheque and document intelligence now live across in-branch, teller and back-office applications, including corporate remote deposit capture
Recent wins include a live signature verification deployment for the FBI and additional healthcare contracts
The FBI deal was announced on Tuesday, and expected to "contribute meaningfully" to FY27 revenue, though commercial terms remain confidential. Stakk shares surged 61% on the day
Company page: Stakk (SKK)
Macquarie upgrades Transurban to Outperform
[9:16 am] Macquarie has upgraded Transurban to Outperform from Neutral, with a target of $14 from $13.50, as bond rates potentially ease and the $4.5 billion WestConnex and NorthWestern Roads deal puts spare balance sheet capacity to work.
10.5% of WestConnex for $2.5bn and 25% of NorthWestern Roads Group for $2bn, with the $4.5bn total in line with the broker's valuation of about $4.6bn
Initial yield of about 4.2%, rising to about 5.5% with NorthWestern Roads regearing, though the deal is not cashflow accretive until year three
$3bn of additional debt capacity comes with the deal, which also extends concession life
I-95 project contractor procurement is starting at an estimated $4.5-5.5bn, or about $6bn including capitalised interest, with first revenues not expected until CY35
US pipeline would reach about $10bn if the I-495S project succeeds, committing most of Transurban's FY31-FY35 balance sheet capacity
FY27 EPS forecasts up 1.8%, with FY28 up 1.5% and FY29 down 0.6% on updated financing and balance sheet assumptions
Company page: Transurban (TCL)
Macquarie lifts Ampol earnings on refining margins after Evie deal
[9:15 am] Macquarie has upgraded its CY26 earnings forecasts for Ampol on stronger refining margins, retaining an Outperform rating and $50 target after the $225 million Evie Networks acquisition.
Evie Networks acquisition for $225m is pending ACCC clearance and will be funded from available cash and debt
$30m EBITDA aspiration for Evie could be achieved if charging bay utilisation lifts to around 15% from below 10%, alongside $10m of synergies, the broker estimates
Lytton refiner margin forecast lifted to US$27.67/bbl for 2H26 vs US$24.7/bbl ests
Lytton EBIT now forecast at $423m in 2H26
5-6MMbbl/d of refining capacity remains offline across Russia and the Middle East, with about 45% of Russia's refining system offline
CY26 EPS forecasts up 7%, with CY27 down 1.2% and CY28 up 0.3% on inclusion of the Evie acquisition
Company page: Ampol (ALD)
Elixir Energy's exclusivity with Beach lapses without binding deal
[9:09 am] Elixir Energy's exclusivity period with Beach Energy over a proposed farm-in to its Taroom Trough portfolio has expired, freeing the company to engage with other interested parties.
Exclusivity expired at close of business on 1 October, before the parties agreed final binding terms under the process deed signed on 21 August
Beach remains in discussions on its proposed strategic farm-in, with the expiry not terminating talks or preventing a deal
Unsolicited interest from additional third parties was received during the exclusivity period and can now be fully considered
All strategic alternatives involving the company and/or its Taroom Trough portfolio will be considered by the board, with no assurance of a binding transaction
Elixir is the largest acreage holder in the Taroom Trough in Queensland's Bowen Basin, appraising about 3.5 TCF of 2C contingent gas resources bordering Shell's main area of investment
Company page: Elixir Energy (EXR)
Praemium CEO Anthony Wamsteker resigns with immediate effect
[9:09 am] Praemium CEO Anthony Wamsteker has resigned as chief executive and director with immediate effect, with chief commercial officer Denis Orrock stepping in as Acting CEO.
Wamsteker will serve a three-month notice period and remain available to assist Orrock during the transition
Denis Orrock joined Praemium in 2022 and has more than 30 years of experience in financial services and wealth management platforms
Permanent CEO search will be run with an external search firm, with both internal and external candidates to be considered
New technology platform will be progressively rolled out to clients over the next year and is expected to deliver efficiency gains and cost base reductions, according to chairman Matthew Quinn
Company page: Praemium (PPS)
Sigma Lithium halts production awaiting Brazil appeals ruling
[9:08 am] Sigma Lithium has suspended all mining and industrial production in Brazil while it awaits an appeals court ruling on an injunction targeting its environmental licences.
Production suspended on 30 September after Minas Gerais environmental authority FEAM issued a notice and the Federal Court of Appeals took 15 days to review Sigma's emergency motion
FY27 guidance of 330,000t of lithium oxide concentrate maintained
12-month guidance of 240,000t pushed back by three months
Tailings operations continue, with sales of high-purity lithium fines expected to self-fund the company during the suspension
Distance dispute at the centre of the NGO lawsuit, with Sigma putting the Quilombola community 8 to 9km from its Xuxa pits and about 11km from Barreiro, against 2.7km claimed
Brazil's election second round on 25 October could delay the appeals decision, according to Sigma, which will seek a further appeal in the superior federal courts if the ruling goes against it
Company page: Sigma Lithium (SAU)
Dynamic Metals sells Lady Jane gold project to First Au
[9:06 am] Dynamic Metals has agreed to sell its Lady Jane gold project in WA's Ora Banda district to First Au for $650,000 in cash and deferred consideration, while keeping a royalty over the asset.
$150,000 cash payable upfront, with $50,000 due within five business days of execution and $100,000 at completion
$500,000 deferred consideration due around the first anniversary of completion, as cash or First Au shares at Dynamic's election
1.5% gross revenue royalty retained over all minerals extracted and sold from the project
Minimum $250,000 drilling spend committed by First Au within 24 months of completion, excluding geophysics, geochemistry, desktop studies and overheads
Re-acquisition right allows Dynamic to buy back the project for $100,000 if First Au misses the drilling commitment
Dynamic Metals trades at a market cap of $31.5 million.
Company page: Dynamic Metals (DYM)
US factory prices surge as activity expands
[9:01 am] US manufacturing growth picked up in September, but price pressures intensified.
S&P Global manufacturing PMI up to 55.9 from 53.9 in August, the highest since May 2022, though below the 57 flash reading
ISM manufacturing index of 54.5 vs 54.9 ests, down 0.1 points from August
ISM prices paid up 6.8 points to 77.9 vs 72 ests
Survey respondents cited tariffs and escalating trade tensions with Canada as headwinds
Source: S&P Global
Global commodity price pressures rise for first time in five months
[9:00 am] Global commodity price inflation accelerated in September on higher energy and transport costs linked to the Middle East, according to S&P Global.
All Items Price Pressures Index up to 2.0 from 1.9, the first rise in five months but well below April's 4.6 peak
A reading of 2.0 means reports of higher prices were twice the long-run survey average
Transport cost reports ran at 6.3 times the long-run average
Energy price pressures hit 4.5 times the average, the highest since May
Semiconductors recorded the most widespread price rises at 13.1 times the average, though this eased from August's four-year peak
Electrical items shortages were the most widespread since February 2023, with copper, oil, semiconductors and transport also in short supply
Source: S&P Global
No date set for US-China tariff cuts, says Greer
[8:59 am] US Trade Representative Jamieson Greer said there is no timeline for cutting tariffs on the $60 billion of goods recommended by the US-China Board of Trade.
Public comment and a legal determination are required before the recommendations are adopted, reducing the chance of relief before the holiday season
$30bn of non-sensitive goods from each country is covered by the plan
US exports under the arrangement include meat and dairy, while Chinese imports include small appliances, toys and holiday decorations
Future tariff measures could draw on the board, including any China remedies from the USTR's excess capacity probe
Source: Bloomberg
Anthropic targets mid-November IPO
[8:54 am] Anthropic is preparing to go public as soon as mid-November, with prospective investors valuing it at up to $2tn, according to Bloomberg.
Investor day on 14 October will be followed by formal marketing as soon as the week of 9 November, ahead of a debut before Thanksgiving on 26 November
Valuation of $1.8tn to $2tn is seen as fair by prospective investors, with Anthropic expecting to match or beat SpaceX's record IPO size
2025 revenue up almost twelve-fold to about $4.6bn from $386m
2025 net loss of almost $42bn, up from $8.3bn, with more than $34bn tied to changes in the fair value of liabilities
Broadcom is lending Anthropic $42bn, with Anthropic tipped to become the chip designer's largest compute customer by next year, according to Reuters
OpenAI has postponed its own IPO, while 2026 listings excluding SpaceX and SK Hynix have returned an average loss of 4%
Source: Bloomberg
Alphabet gains premarket on Gemini 4 Argon launch
[8:53 am] Alphabet shares rallied 2.7% in early trade but finished 1.7% lower after launching Gemini 4 Argon, its most advanced AI model, with Jefferies flagging pricing well below Anthropic's.
Pricing of $2 per million input tokens and $10 per million output tokens compares with $4 and $20 for Claude Opus 5.5 and $10 and $50 for Claude Fable 5.1
DeepSWE v1.1 score of 77.9% is a record on the coding benchmark, though Argon trails leading rivals on the tougher FrontierSWE v2 test
CWE-bench v1 score of 68% tied Grok 4.7, with initial access limited to trusted cybersecurity researchers
Prompt injection success rate of 0.7% vs 1% for Claude Opus 5.5 and Fable 5.1
Output limit lifted to 1m tokens from 64,000, compared with 128,000 for Anthropic's models
Source: Yahoo Finance
US 10-year yield hits highest since 2002 before reversing
[8:50 am] Treasury yields hit fresh multi-decade highs early in the session before reversing, with the sharpest declines at the short end of the curve.
10-year yield rose as much as 5 bps to 5.344% intraday, its highest since April 2002, but finished the session 4 bps lower to 5.24%
2-year yield down 10 bps to 4.79% as traders priced out the chance of a Fed hike this month
30-year yield reached levels not seen in 24 years earlier in the session, finished fractionally lower at 5.61%
Macquarie's Thierry Wizman links higher yields to the Iran war's impact on both inflation and deficits, with Pentagon figures putting US war spending at $43.6bn or more
TD Securities says a fiscal crisis is not imminent, with the 5.9-year average maturity of US debt meaning higher rates feed into borrowing costs gradually
Source: Yahoo Finance
China suspends fuel exports
[8:46 am] Chinese refiners have halted oil product exports beyond Hong Kong and Macau until further notice from Beijing, according to Reuters.
PetroChina cancelled a handful of gasoline and jet fuel shipments planned for October, most of which were committed in the past two weeks
Zhejiang Petrochemical skipped scheduling any oil product shipments during the holiday week
No export approval was given before China's week-long holiday began on Thursday, and it is unclear whether exports resume after it ends on 7 October
Asian diesel margins rebounded to about $75 a barrel, the highest in a week
Global fuel markets are already grappling with lost supply from the Middle East and Russia, with the suspension potentially pushing prices in some countries to new highs
Source: Reuters
Oil jumps as US sends third carrier towards Middle East
[8:45 am] Oil rallied after reports the US is sending a third aircraft carrier towards the Middle East, adding to supply concerns after China halted fuel exports.
USS Theodore Roosevelt left San Diego on Sunday and would return the US to three carrier strike groups in the region, though no final destination has been set
10,000 additional sailors and Marines could also be deployed, with forces expected to arrive by the end of November
Trump told Time magazine that ramped-up bombing of Iran after the November midterms was "possible"
Nuclear inspectors could return to bombed facilities in exchange for sanctions relief, Iran's foreign minister Abbas Araghchi suggested in private talks
Iran loaded no crude onto tankers in September, down from about 250,000 barrels per day in August, under the US naval blockade
Iranian inflation is running at almost 90% year-on-year, with the rial down 30% against the US dollar
Three tankers came under attack this week while trying to transit the Strait of Hormuz, even as Middle East crude flows recovered to prewar levels
Fed's Jefferson says next rate move may take more time
[8:43 am] Fed vice chair Philip Jefferson said inflation remains too high but stopped short of endorsing another rate hike.
Jefferson said yields have risen across the curve since September's meeting and policymakers "will need to come to our own judgment, which may take more time"
Energy prices, the AI buildout and trade policy were the shocks Jefferson cited as buffeting the economy
New York Fed's John Williams said earlier in the week there is no urgency to follow September's quarter-point hike with another move
Minneapolis Fed's Neel Kashkari said AI data centre investment is likely pushing the neutral rate higher temporarily
US AI investment is expected to reach about $581bn this year, around 10% of private fixed investment
Nike slumps 8.5% after hours on FY27 guidance miss
[8:41 am] Nike shares fell 8.5% after hours to their lowest since September 2013 after FY27 earnings guidance came in well short of ests.
Revenue down 4% to $11.21bn vs $11.32bn ests (1% miss)
Nike Direct down 8% to $4.1bn vs $4.4bn ests (7% miss)
Greater China down 22% to $1.18bn vs $1.3bn ests (9% miss)
Converse down 28% to $263m vs $296m ests (11% miss)
Gross margin of 42.8% vs 42.2% ests (60bp beat), helped by lower warehousing and logistics costs
EPS down 2% to $0.48 vs $0.43 ests (12% beat)
FY27 adjusted EPS guidance of $1.15 to $1.35 vs $1.65 ests (24% miss), excluding about $0.15 of Pace restructuring costs
FY27 revenue is expected to decline by a high single digit percentage
Management said "We have more work to do in Nike Sportswear, Jordan Brand and Greater China, and we're taking deliberate actions to strengthen those businesses the right way for the long-term"
Wall St claws back early losses as yields ease
[8:40 am] US stocks finished the first session of October modestly higher after recovering from morning losses as Treasury yields pulled back from multidecade highs.
S&P 500 up 0.19% to 7,666.45, while the Nasdaq rose 0.04% to 26,871.60 and the Dow added 20 points to 50,926.56
Russell 2000 up 0.35% after falling more than 5% in September and about 7.5% over the third quarter
KBW Nasdaq Bank Index fell as much as 2.4% intraday before paring losses, and sits more than 13% below its mid-August peak
Accenture up about 18% at midday after fiscal fourth quarter revenue of $18.68bn topped its own guidance range of $17.8bn to $18.4bn
FICO up 8% after FHFA director Bill Pulte said he would ensure its new FICO Direct mortgage program is approved
Good morning!
[8:24 am] ASX 200 futures are up 45 pts (+0.52%). Here's what happened overnight:
Wall Street shook off a bond scare, with the S&P 500 clawing back a (0.45%) decline to close slightly higher, after Treasury yields eased from their highest levels in more than two decades
S&P 500 (+0.19%), Nasdaq (+0.04%), Dow (+0.04%) and Russell 2000 (+0.35%)
Oil pushed back above $100 after a report the US is sending a third carrier strike group to the Middle East and Chinese refiners halted fuel exports
AI dealmaking stayed front and centre, with Anthropic reportedly targeting a mid-November IPO and its prospectus revealing a $42bn Broadcom financing line