ASX 200 Live Today - Monday, 12th October
The S&P/ASX 200 is up for a second straight session, near a one-month high, led by miners, banks and tech. Here are today’s top stories.
Today’s ASX 200 Updates
Welcome to our live ASX coverage for Monday, October 12. Expect a high volume of posts pre-market and more periodic updates throughout the day. We'll be wrapping the blog up around 2:00 pm AEST. Let us know how we can make it even better.
ASX 200 nears one-month high as miners and banks lead
[2:19 pm] That's a wrap! The ASX 200 is up 69 points or 0.80%, taking its gain over the past two sessions to 1.43%. The index is now just shy of a one-month high and about 0.3% below its key 200-day moving average. Heavyweight miners and banks are carrying the index, tech continues to gather strength and healthcare has hit a fresh eight-month high, while defensive and yield-sensitive sectors take a breather.
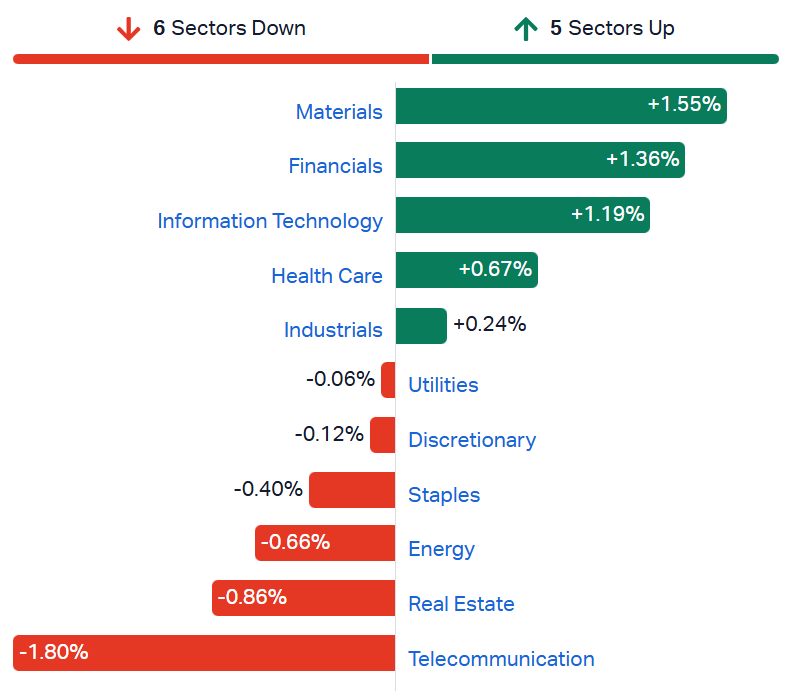
S&P/ASX 200 sectors (Source: Market Index)
It’s a tentatively constructive backdrop overall. Brent is down 1.3% to US$102.85 a barrel, Australian yields continue to ease from recent highs and commodity prices have firmed over the past two sessions.
Australian 3-year yield down 2.7bps to 4.90%
Australian 10-year yield down 2.5bps to 5.33%
Australian 30-year yield down 3.0bps to 5.80%
With tech regaining momentum, here’s a look at this year’s best and worst ASX 200 performers. The leaderboard is largely unchanged, with Codan, Minerals 260 and Megaport holding the podium spots they’ve occupied for some time.
Ticker | Company | YTD | Price |
|---|---|---|---|
CDA | Codan | 137.8% | $67.59 |
MI6 | Minerals 260 | 96.4% | $0.83 |
MP1 | Megaport | 75.4% | $19.90 |
RHC | Ramsay Health Care | 57.0% | $54.05 |
DTL | Data#3 | 54.8% | $13.89 |
VEA | Viva Energy Group | 53.4% | $3.18 |
NWH | NRW | 53.1% | $7.66 |
NHC | New Hope Corporation | 49.1% | $5.98 |
TLX | Telix Pharmaceuticals | 45.3% | $16.35 |
The recent resurgence for tech stocks has seen names like Wisetech, Xero and Seek fall out of the top 10, replaced by lithium, uranium and property-linked names like Lendlease and Pexa.
Ticker | Company | YTD | Price |
|---|---|---|---|
TUA | Tuas | -77.1% | $1.61 |
VUL | Vulcan Energy Resources | -69.4% | $1.35 |
IPX | Iperionx | -57.7% | $2.33 |
CIA | Champion Iron | -54.2% | $2.78 |
GDG | Generation Development Group | -52.9% | $2.78 |
LTR | Liontown | -52.9% | $0.74 |
LLC | Lendlease Group | -51.9% | $2.50 |
SLX | Silex Systems | -51.9% | $4.06 |
PXA | Pexa Group | -51.9% | $6.47 |
COH | Cochlear | -50.6% | $128.92 |
Large caps lead as gains fade further down the market
[1:53 pm] The S&P/ASX 200 Resources and Banks indices are up 1.6% and 1.5% respectively, while the ASX 20 is trading 1.1% higher. Gains thin out the further you move down the market cap spectrum, with the ASX 300 up 0.8%, the All Ords up 0.7%, the Small Ords up just 0.3% and the Emerging Companies Index down 0.2%.
Ticker | Company | % Chg | Price | 1 Week | YTD |
|---|---|---|---|---|---|
BHP | BHP Group | 2.5% | $62.45 | 0.9% | 37.2% |
CBA | Commonwealth Bank | 0.9% | $150.66 | -0.9% | -6.2% |
RIO | Rio Tinto | 1.0% | $164.01 | -1.2% | 11.7% |
NAB | National Australia Bank | 2.0% | $38.43 | -0.2% | -9.1% |
WBC | Westpac | 2.1% | $34.42 | -0.1% | -10.6% |
ANZ | ANZ Group | 1.9% | $37.89 | 1.4% | 4.0% |
MQG | Macquarie Group | 2.0% | $253.31 | 2.8% | 24.8% |
CSL | CSL | 0.4% | $184.49 | 5.4% | 6.3% |
WES | Wesfarmers | 0.4% | $77.63 | 1.7% | -4.2% |
WDS | Woodside Energy Group | -0.9% | $32.03 | 2.4% | 35.0% |
Copper nears record high but small caps lag the move
[1:47 pm] Copper stocks are trading mostly higher after the metal rallied 2.4% last Friday. It’s up a further 0.4% at the time of writing to US$6.78/lb, within 2% of its record close on 22 September.
Risk appetite isn’t firing on all cylinders, though. Plenty of small caps, including 29Metals, Aeris, Cyprium and Firefly Metals, are lagging the move. The only smaller names advancing strongly are high-flyers like Kantra and Cobre, the latter having raised $90m on 2 October at 30 cents per share, a 9.1% discount.
Ticker | Company | % Chg | Price | 1 Week | YTD |
|---|---|---|---|---|---|
CBE | Cobre | 7.1% | $0.34 | -3.6% | 237.5% |
SFR | Sandfire Resources | 4.2% | $22.94 | 3.7% | 27.7% |
KAN | Kantra Copper | 2.8% | $1.19 | -2.3% | 64.9% |
S32 | South32 | 2.5% | $5.04 | 1.5% | 41.8% |
BHP | BHP Group | 2.4% | $62.43 | 0.8% | 37.1% |
CSC | Capstone Copper Corp | 2.3% | $13.92 | -4.8% | -8.2% |
29M | 29Metals | 2.3% | $0.34 | -6.2% | -35.9% |
RIO | Rio Tinto | 1.0% | $163.96 | -1.2% | 11.7% |
AIS | Aeris Resources | 0.5% | $0.47 | -1.6% | -21.3% |
CYM | Cyprium Metals | 0.0% | $0.43 | 0.0% | -18.8% |
FFM | Firefly Metals | -0.5% | $1.58 | -5.5% | -23.4% |
HCH | Hot Chili | -0.7% | $1.51 | -1.9% | 8.6% |
MC2 | Marimaca Copper Corp | -2.7% | $7.80 | -6.6% | -37.6% |
AR1 | Austral Resources | -4.2% | $0.07 | -5.6% | 19.3% |
Morgans cuts Megaport, Pinnacle and ARB from Best Ideas
[12:44 pm] Morgans has trimmed its Best Ideas list, removing Megaport after it hit the broker’s targeted return ahead of schedule and two others on near-term earnings risk.
Megaport removed after delivering Morgans’ targeted return faster than expected, though it retains a Buy rating, with sentiment and volatility around AI and tech names remaining high
Pinnacle removed as private credit issues at Metrics could weigh on the stock until those risks pass or capital market conditions improve, despite Morgans seeing clear value
ARB removed after weaker-than-expected new vehicle sales lowered confidence in an improved aftermarket sales update at its AGM
Large-cap Best Ideas are Wesfarmers, Evolution Mining, Sigma Healthcare, ResMed, Aristocrat, ALS, Orica, Infratil, REA Group and DBI
Mid-small cap Best Ideas include Pro Medicus, Eagers Automotive, Treasury Wines, Monadelphous, Capstone Copper, Ramelius Resources, Civmec, Lovisa, Guzman Y Gomez, Imricor and Nufarm
Omega surges 19% on best Canyon well result to date
[12:42 pm] Omega Oil & Gas shares are up 19.2% to 77.5 cents after its Canyon-4 well returned its strongest result yet in the Taroom Trough, taking year-to-date gains to 84%.
Net pay of 197m across a 589m gross oil and gas-bearing sequence, up from 170m at Canyon-3 and 132m at Canyon-1
Average porosity in the primary Canyon Sandstone target rose to 12.1%, up from 7.4% at Canyon-1
Oil indicators from gas ratios and petrophysical analysis point to oil through most reservoir intervals, with gas observed bubbling from the core
Development potential across the roughly 400km2 area around the Canyon wells could support about 160 horizontal well locations
Resource upgrade for oil and gas is being targeted by 1Q27, with horizontal flow testing to follow in 1H27
Appraisal program remains fully funded following a $60m raise in April at 84 cents per share, with shares still 7.7% below that price
Company page: Omega Oil & Gas (OMA)
UBS sticks with Zip after 20% slide, trims target
[12:39 pm] UBS has reiterated its Buy rating on Zip, arguing macro concerns behind the stock’s roughly 20% fall over two months are overplayed, though it has cut its price target 6% to $4.40.
US TTV growth of 35% year-on-year is forecast for Q1 FY27, with peers guiding to around 30% volume growth for the September quarter
Non-discretionary spend accounts for 65-70% of US TTV, supporting UBS’s 30% FY27 growth forecast in constant currency
Net bad debts are forecast to rise to 1.82% in FY27 from 1.77% in FY26, still within Zip’s 1.5-2% target range
Q1 FY27 preview forecasts portfolio income of $369m and cash EBTDA of $76.9m, ahead of the 23 October result
Cash EBTDA forecasts were trimmed 1% on expectations of another rate hike in Australia and the US by the end of CY26
Valuation of 15x forward P/E looks attractive for high-teens earnings growth, with the lower target also reflecting a higher risk-free rate of 5%, up from 4.5%
Company page: Zip Co (ZIP)
CPI and Warsh in focus as Treasury yields hover near 24-year high
[12:31 pm] US bond traders are looking to this week’s CPI print and an appearance by Fed Chair Kevin Warsh for clues on how quickly the Fed will keep raising rates.
Treasury yields were little changed last week, hovering near a 24-year high after jumping on the Fed’s unanimous rate hike last month
October hold is expected after a sharp slowdown in job growth, with markets pricing a 25bp hike in December and two more by late 2027
Headline CPI is expected to rise 0.6% month-on-month in September, up from 0.4%, lifting the annual rate to 3.6%
Core CPI is seen easing to 0.2% month-on-month from 0.3%, with the annual rate rising to 2.5%
TD Securities said the risk to CPI is asymmetric, as a hotter print could signal the Fed needs to pick up the pace of tightening
Warsh speaks on Thursday (US time) at the IMF annual meeting in Bangkok, alongside Waller and Hammack, before the Fed’s blackout period begins ahead of its 28 October decision
Source: Bloomberg
UBS drops CSL and AMP from top picks as it backs capex over consumer
[11:59 am] UBS has trimmed its Australian Top Picks list to nine stocks, leaning into a “capex over consumer” theme following August reporting season.
Overweight Mining and Industrials on a capex cycle fuelled by spending on data centres, mining, energy and defence, while underweight Banks and Consumer on the risk of EPS downgrades from RBA rate hikes
Current Top Picks are BHP, Charter Hall, IAG, Light & Wonder, Mineral Resources, Megaport, Orica, Sigma Healthcare and Ventia
Removed AMP after recent outperformance and a downgrade to Neutral, Auckland Airport ahead of NZ’s general election, Genesis Minerals on structurally higher real rates, and CSL after hitting its price target
BHP offers exposure to UBS’s preferred commodity, with about 55% of FY27 EBITDA expected from copper
Megaport’s contracted EBITDA of $650m from its Latitude AI compute contracts points to upside risk for FY28 EBITDA forecasts of $697m from UBS and $716m from consensus
Charter Hall trades on 15.8x NTM P/E vs 18.0x for the ASX 200, despite forecast FY27 EPS growth of 13% vs 8% for the index
Source: UBS
Macquarie lifts Viva Energy target on distillate strength
[11:58 am] Macquarie has raised its Viva Energy price target to $4.00 from $3.75 and retained an Outperform rating, arguing the valuation remains undemanding despite the stock’s strong run.
2H26 refining margin forecast raised to US$24.40/bbl, 12% above consensus of US$21.84/bbl
CY27 refining margin
forecast lifted to US$16.1/bbl, also 12% above consensus, with 5-6MMbbl/d of refining capacity still offline across Russia and the Middle East
Geelong EBITDA forecast at $442m for 2H26, including a 3Q refining margin of US$24.7/bbl
Convenience and mobility EBITDA forecast is 9% below consensus for 2H26, as soft retail fuel margins offset an improving shop contribution
EPS forecasts raised 7% for CY26 and 20% for CY27 on higher refining margins
FSSP Phase 2 outcome is expected this year and will shape Viva’s decision on its fire-damaged alkylation unit, ahead of an investor day on 9 November
Company page: Viva Energy (VEA)
Another strong day for tech
[11:09 am] Tech stocks are trading broadly higher following the strong lead from Wall Street (iShares Expanded Tech-Software ETF up 2.8% to its highest close since November 2025). The battered old guard names like Zip, Wisetech, Xero and Pro Medicus are all up 3-4%, but still down massively YTD.
Ticker | Company | % Chg | Price | 1 Week | YTD |
|---|---|---|---|---|---|
MP1 | Megaport | 5.0% | $19.71 | -11.4% | 73.7% |
ZIP | Zip Co | 4.2% | $2.25 | 7.1% | -31.2% |
WTC | Wisetech Global | 3.3% | $34.76 | 5.3% | -49.3% |
BVS | Bravura Solutions | 3.2% | $3.27 | 3.8% | 27.2% |
XRO | Xero | 3.1% | $61.64 | 7.2% | -45.9% |
PME | Pro Medicus | 2.9% | $170.57 | 9.2% | -22.7% |
NXL | Nuix | 2.6% | $1.75 | -9.4% | -3.6% |
PPS | Praemium | 1.6% | $0.63 | 5.0% | -20.8% |
CDA | Codan | 1.6% | $67.37 | -0.6% | 137.0% |
360 | Life360 | 1.3% | $20.61 | 1.0% | -36.0% |
OCL | Objective Corporation | 1.3% | $5.79 | -4.9% | -65.0% |
DDR | Dicker Data | 1.1% | $16.25 | 5.5% | 57.9% |
MAQ | Macquarie Technology Group | 1.0% | $51.64 | -4.1% | -22.9% |
DTL | Data#3 | 0.8% | $13.99 | 2.1% | 55.9% |
IRE | Iress | 0.6% | $5.66 | 3.0% | -32.5% |
TNE | Technology One | 0.5% | $31.42 | 2.9% | 14.0% |
DGT | Digico Infrastructure Reit | 0.4% | $2.39 | -3.2% | -14.3% |
CAT | Catapult Sports | 0.3% | $3.23 | -2.1% | -22.4% |
AD8 | Audinate Group | 0.2% | $2.16 | -8.7% | -46.9% |
SDR | Siteminder | 0.2% | $2.70 | -2.0% | -56.0% |
IFT | Infratil | -0.5% | $10.64 | -6.1% | 11.0% |
NXT | NextDC | -0.6% | $10.31 | -4.5% | -16.3% |
HSN | Hansen Technologies | -0.6% | $3.36 | -0.3% | -36.4% |
Southern Cross Electrical jumps 6.7% on accretive Entire acquisition
[10:56 am] Southern Cross Electrical opened 3.6% higher at $4.80 and has extended its gains to 6.7% at $4.94, after announcing the acquisition of Victorian fire protection and HVAC services group Entire.
Purchase price of up to $112.1m, funded from existing cash, represents 5.5x FY26 EV/EBIT assuming maximum base earn-outs
EPS accretion of at least 18% is expected on a FY27 pro forma basis
FY27 EBITDA guidance lifted to at least $110m, including a $10m contribution from Entire
Entire generated revenue of $191m and EBIT of $17.5m in FY26, with data centres making up about 25% of revenue
Recent selloff saw shares fall 13% over the previous four sessions, with the Firmus IPO failure weighing on engineering names
Company page: Southern Cross Electrical Engineering (SXE)
A strong day for miners
[10:54 am] The S&P/ASX 200 Materials Index is up 1.8%, led by a broad mix of copper, lithium, coal and gold names. The index is pretty much flat over the past month and still 10% away from its 25 August record high.
Ticker | Company | % Chg | Price | 1 Week | YTD |
|---|---|---|---|---|---|
SFR | Sandfire Resources | 3.4% | $22.75 | 2.8% | 26.7% |
LTR | Liontown | 3.2% | $0.80 | -0.6% | -49.4% |
BSL | Bluescope Steel | 3.0% | $30.85 | 0.8% | 28.2% |
PLS | PLS Group | 3.0% | $3.61 | -2.6% | -14.2% |
SMR | Stanmore Resources | 2.9% | $2.64 | 1.7% | 13.1% |
MIN | Mineral Resources | 2.7% | $50.68 | -1.2% | -6.8% |
S32 | South32 | 2.6% | $5.04 | 1.6% | 42.0% |
BHP | BHP Group | 2.5% | $62.49 | 1.0% | 37.3% |
CMM | Capricorn Metals | 2.3% | $15.08 | 3.8% | 7.7% |
NST | Northern Star Resources | 2.1% | $24.90 | 3.7% | 1.4% |
ASX 200 edges higher as tech rallies and miners bounce
[10:29 am] The ASX 200 is up 29 points or 0.33%, led by a rally in tech and a bounce in miners from a near 10-week low after broad-based gains in commodity prices overnight. Breadth is mixed, with only four sectors in the green and constituents fairly evenly split between gainers and decliners. Telcos are lagging on competition fears from SpaceX, staples opened broadly lower and real estate is slipping after a four-day winning streak.
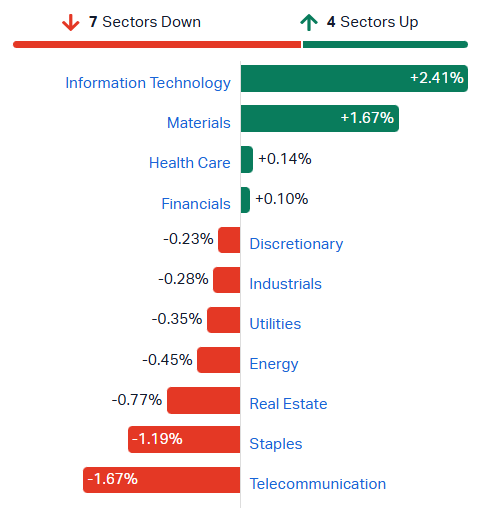
S&P/ASX 200 sectors (Source: Market Index)
Top ASX 200 gainers
[10:19 am] Tech stocks top the leaderboard, extending last Friday's broad-based rally and a strong lead from US software stocks.
Ticker | Company | % Chg | Price | 1 Week | YTD |
|---|---|---|---|---|---|
IPX | Iperionx | 9.5% | $2.41 | -1.6% | -56.3% |
EOS | Electro Optic Systems | 5.3% | $10.67 | -6.8% | 13.0% |
MP1 | Megaport | 4.5% | $19.63 | -11.8% | 73.0% |
WTC | Wisetech Global | 4.1% | $35.00 | 6.1% | -48.9% |
WAF | West African Resources | 3.7% | $3.83 | 9.0% | 28.8% |
ZIP | Zip Co | 3.5% | $2.24 | 6.4% | -31.7% |
PNR | Pantoro Gold | 3.3% | $3.12 | 6.8% | -36.3% |
4DX | 4Dmedical | 3.2% | $4.18 | -3.9% | 4.5% |
XRO | Xero | 3.1% | $61.67 | 7.3% | -45.9% |
BSL | Bluescope Steel | 3.1% | $30.87 | 0.9% | 28.3% |
Top ASX 200 losers
[10:19 am] Telcos open broadly lower, likely driven by SpaceX's plans to acquire critical low-band spectrum needed for Starlink Mobile to offer direct-to-device phone coverage and bypass traditional cell towers.
Ticker | Company | % Chg | Price | 1 Week | YTD |
|---|---|---|---|---|---|
TLS | Telstra Group | -2.5% | $4.65 | -3.5% | -4.5% |
SOL | Washington H. Soul Pattinson | -2.4% | $45.27 | -1.0% | 21.7% |
TPG | TPG Telecom | -2.2% | $3.80 | -1.2% | -0.1% |
CNI | Centuria Capital Group | -2.2% | $1.14 | -3.4% | -43.2% |
WOW | Woolworths Group | -2.1% | $38.74 | 0.6% | 31.9% |
SHL | Sonic Healthcare | -2.1% | $18.26 | -1.2% | -19.2% |
A2M | A2 Milk Company | -2.1% | $6.59 | -1.3% | -28.4% |
ARB | ARB Corp | -2.0% | $17.26 | -1.9% | -45.7% |
DMP | Domino's Pizza | -2.0% | $21.76 | 9.1% | 3.5% |
CPU | Computershare | -2.0% | $39.58 | -0.8% | 16.5% |
Arafura lifts NdPr offtake volume 70% in binding agreement
[9:58 am] Arafura has converted its binding term sheet with a global trading company into a full offtake agreement, with a larger contracted volume than first agreed.
Volume of 850tpa of NdPr oxide at nameplate production, up from 500tpa in the May term sheet, plus associated heavy rare earths
Five-year term with a two-year extension option by mutual agreement
Pricing in USD, linked to a global seaborne index such as Benchmark Minerals Intelligence or S&P Global Platts North America
Counterparty generates about US$10bn in annual revenue and has been tapped under the US government’s Project Vault critical minerals initiative
Future disclosures will no longer name offtake counterparties unless the identity itself is material, as talks continue with other parties
Company page: Arafura Rare Earths (ARU)
Glencore reaffirms Jaguar offtake as Centaurus nears funding package
[9:58 am] Centaurus Metals has confirmed Glencore’s offtake for the Jaguar nickel project remains binding, locking in a key piece of its funding strategy.
Glencore offtake announced in March remains binding and effective on previously announced terms
Additional offtake and strategic funding negotiations are at an advanced stage, with final documentation underway
Senior debt financing process is also well advanced
Funding package updates are expected in the near term, ahead of a final investment decision on Jaguar
Company page: Centaurus Metals (CTM)
Abacus Group MD Steven Sewell to retire
[9:58 am] Abacus Group managing director Steven Sewell will retire after more than eight years in the role.
Sewell will remain MD until 9 July 2027, or earlier if a successor is appointed
Search underway for a replacement, with Spencer Stuart appointed
Timing follows the internalisation of Storage King Group on 30 June 2026, with Sewell saying “it’s an appropriate time” to hand over leadership
Tenure since April 2018 oversaw the group’s shift from an opportunistic core-plus investor to a specialised commercial REIT
Company page: Abacus Group (ABG)
GQG outflows continue despite improved performance
[9:45 am] GQG Partners’ FUM was flat in September as investment gains only just covered another month of net outflows.
September net outflows of US$2.3bn, offset by US$2.4bn in investment performance, leaving FUM steady at US$149.2bn
All four strategies recorded outflows in September, led by Emerging Markets at US$1.0bn
Q3 net outflows of US$11.1bn, partly offset by US$4.4bn in investment performance
YTD net outflows of US$26.2bn, with FUM down 9% from US$163.9bn at the start of the year
Emerging Markets has lost US$9.8bn to outflows YTD, about 24% of its starting FUM, while US strategy outflows of US$4.0bn equate to 27%
Investment returns were positive on both an absolute and relative basis across all four strategies in September and the quarter, following recent portfolio repositioning
Company page: GQG Partners (GQG)
Kaoko copper-silver hits headline busy day for explorers
[9:45 am] Kaoko Metals led a busy session of explorer updates, with maiden drilling in Namibia confirming a shallow copper-silver discovery.
Kaoko Metals first-ever drilling at its Chalkos project hit 37.1m at 1.23% Cu and 15.2g/t Ag from 54m, with a second hole returning 48m at 1.02% Cu and 12.9g/t Ag
Caspin Resources lifted its Kelpie tin resource 45% to 6.5Mt at 0.43% Sn for 28kt of contained tin, with 25% now in the Indicated category
Austral Resources extended the McLeod Hill copper system beyond 1km of strike, more than double the existing resource footprint, with a best hit of 5m at 2.32% Cu
Critica delivered a maiden Indicated resource of 160Mt at 1,700ppm TREO within its 1.7Bt Jupiter resource, with a scoping study due shortly
Iltani Resources intersected a 5.4m sulphide zone in its first hole at Isabel, including an estimated 35% sphalerite over 2m, with assays due in December
Dalaroo Metals logged a 34m zone of alteration and quartz-sulphide veining 1.25km from its Wilfred discovery, with assays expected before the end of October
Kali Metals identified nine new gold target areas at Marble Bar, with helicopter-supported reconnaissance starting mid-October
Company pages: Kaoko Metals (KAO), Caspin Resources (CPN), Austral Resources (AR1), Critica (CRI), Iltani Resources (ILT), Dalaroo Metals (DAL), Kali Metals (KM1)
My two cents on the SCEE and GenusPlus acquisitions
[9:35 am] A few quick thoughts on the Southern Cross Electrical and GenusPlus acquisitions.
Both stocks have pulled back in recent days, with Southern Cross Electrical down 13% and GenusPlus down 7.4% over the past four sessions. The failed Firmus IPO looks like the likely catalyst
Year-to-date gains remain strong, with most of these engineering names still up more than 50%
Recent capital raisings have left both companies well funded, with SCEE raising $165m in June and GenusPlus $200m in May
Acquisition multiples are broadly in line with what you typically see in this space, at around mid-single digit EV/EBIT
SCEE’s deal looks very accretive at first glance, with up to $112.1m paid from cash (under 8% of its $1.43bn market cap) delivering at least 18% EPS accretion from FY27. Wouldn't be surprising to see a strong market reaction this morning
GenusPlus didn’t quantify accretion, but UCG’s FY26 EBIT of NZ$7.8m is equivalent to about 8% of Genus’s $81.3m FY26 EBIT
SCEE lifts FY27 guidance with $112m Entire acquisition
[9:23 am] Southern Cross Electrical Engineering is buying Victorian fire protection and HVAC services group Entire, marking its entry into mechanical services and building scale in Victoria.
Total consideration of up to $112.1m, including $70m upfront and up to $42.1m in earn-outs tied to FY27 to FY29 EBIT targets, funded from existing cash
Purchase price represents 5.5x FY26 EV/EBIT with maximum base earn-outs, or 4.1x FY29 EV/EBIT if outperformance earn-outs are paid (implying FY29 EBIT of at least $27.5m)
Entire generated revenue of $191m and EBIT of $17.5m in FY26, with data centres making up about 25% of revenue and recurring maintenance about 35%
EPS accretion of at least 18% expected on a FY27 pro forma basis
FY27 EBITDA guidance lifted to at least $110m, including a $10m contribution from Entire assuming completion on 1 November
Mechanical services entry backed by data centre and electrification tailwinds, with MD Graeme Dunn saying “Mechanical (HVAC) is a logical adjacency for SCEE”
Company page: Southern Cross Electrical Engineering (SXE)
Genus expands into New Zealand with up to NZ$65m UCG acquisition
[9:22 am] GenusPlus is buying New Zealand telecommunications contractor UCG, giving it a platform for growth across the Tasman anchored by a long-term Chorus contract.
Total consideration of up to NZ$65m, comprising NZ$38.25m upfront, NZ$1.75m deferred over two years and up to NZ$25m in earn-outs, funded from cash and existing debt facilities
UCG generated revenue of NZ$96m and adjusted EBIT of NZ$7.8m in FY26 (unaudited)
Purchase price represents 5.1x EV/EBIT on upfront and deferred consideration, or 5.0x if maximum earn-outs are paid, and is expected to be immediately earnings accretive
Earn-out hurdles require adjusted EBIT of NZ$9.9m in FY27 and NZ$13m in FY28 for full payment, implying 27% and 31% growth respectively
Chorus has been a customer for more than 10 years, with UCG holding a long-term maintenance, build and provisioning contract across the upper North Island, including Greater Auckland
Company page: GenusPlus Group (GNP)
Summerset resales jump 36% as Middle East uncertainty weighs on new sales
[9:15 am] Summerset’s resales had a strong quarter, offsetting softer new sales as economic uncertainty made some prospective residents hesitate to sell their homes.
Total sales of 415 in Q3, comprising 175 new sales and 240 resales
Resales up 36% year-on-year to 240, ahead of 227 in Q2
YTD sales up 10% to 1,228, with resales up 27%
New sales down on Q3 2025, which CEO Scott Scoullar attributed to the Middle East conflict delaying home sales
New sales contracts up 20% on Q1 and Q2, with no material change in contracting rates since the deferred management fee was lifted to 30% in August
Q4 outlook supported by a solid contract pipeline, with Scoullar saying “the level of buyer interest and our pipeline of contracts give us confidence in sales rates for the balance of the year”
Company page: Summerset Group (SNZ)
Ryman resales hit eight-quarter high as aged care occupancy climbs
[9:15 am] Ryman Healthcare delivered its strongest resales quarter in two years, with demand for serviced apartments and aged care holding up despite soft housing conditions.
Total sales of 379 in Q2 FY27, comprising 312 resales and 67 new sales
Resales up 14% year-on-year, underpinned by continued strength in serviced apartments
Net resales contracts up 11% year-on-year, following 7% growth in Q1 FY27
New retirement living stock down 67 units to 347, taking the reduction since 31 March to 132 units
Aged care occupancy of 94.0%, up 3.3 percentage points year-on-year
Resales target of matching turnover by the end of FY27 remains on track, with CEO Naomi James saying Ryman entered the second half “with a healthy contract book”
Company page: Ryman Healthcare (RYM)
Meeka starts second underground mine with first ore due January
[9:14 am] Meeka Metals has started decline development at Turnberry, adding a second high-grade ore source at its Murchison Gold Project.
Fairway decline development started in October, after surface infrastructure and the portal were completed in September
First ore expected in January 2027, to be trucked about 20km to the processing plant alongside ore from the Andy Well mine
Initial Ore Reserve of 50koz at 2.5g/t Au, within an underground Mineral Resource of 360koz at 3.9g/t Au
Drilling below the reserve returned 52.3m at 3.0g/t Au and 18.0m at 3.0g/t Au
Reserve growth to be targeted from underground drill platforms, with MD Tim Davidson saying “The 50koz Ore Reserve is only a starting point”
Company page: Meeka Metals (MEK)
Is it time to get bullish on local tech?
[9:04 am] Local tech stocks rallied last Friday, with Pro Medicus, WiseTech, Life360, Zip and Xero all gaining more than 3%. Then, the iShares Expanded Tech-Software ETF gained 2.8% overnight to its highest close since November 2025. The ETF is now up 5.8% year-to-date, a sharp turnaround from a 30% year-to-date decline in mid-April. The past couple of weeks have been rather constructive, with shallow pullbacks, a run of higher lows and holding above the key 50-day moving average.
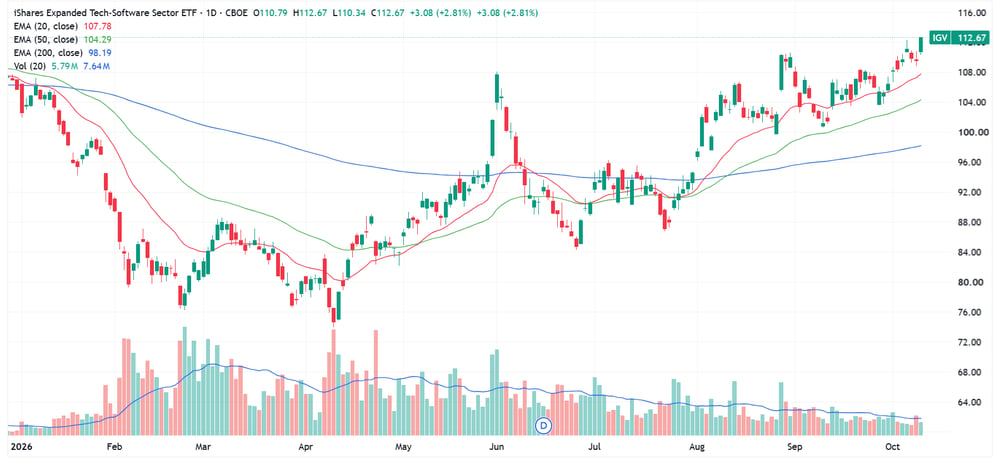
iShares Expanded Tech-Software ETF daily chart (Source: TradingView)
Despite Friday’s strength, most local tech names remain well down for the year. The question now is whether they continue to lag their US peers, or whether a catch-up rally is starting to play out.
Ticker | Company | % Chg | Price | 1 Week | YTD |
|---|---|---|---|---|---|
PME | Pro Medicus | 4.5% | $165.73 | 3.0% | -24.9% |
WTC | Wisetech Global | 4.2% | $33.63 | 5.6% | -50.9% |
360 | Life360 | 4.1% | $20.34 | 4.1% | -36.9% |
ZIP | Zip Co | 3.8% | $2.16 | 8.0% | -33.9% |
XRO | Xero | 3.5% | $59.81 | 7.1% | -47.5% |
DTL | Data#3 | 3.4% | $13.87 | 5.0% | 54.6% |
IRE | Iress | 3.3% | $5.62 | 4.7% | -32.9% |
TNE | Technology One | 2.9% | $31.27 | 6.3% | 13.5% |
BVS | Bravura Solutions | 2.9% | $3.17 | 2.6% | 23.3% |
CDA | Codan | 2.7% | $66.32 | -1.4% | 133.4% |
DDR | Dicker Data | 1.8% | $16.07 | 4.0% | 56.2% |
CAT | Catapult Sports | 1.6% | $3.22 | 1.3% | -22.6% |
SDR | Siteminder | 1.5% | $2.69 | 1.1% | -56.1% |
HSN | Hansen Technologies | 0.9% | $3.38 | 8.3% | -36.0% |
NXT | NextDC | 0.9% | $10.37 | -1.6% | -15.8% |
MAQ | Macquarie Technology Group | 0.3% | $51.15 | -2.8% | -23.7% |
PPS | Praemium | 0.0% | $0.62 | 10.7% | -22.0% |
DGT | Digico Infrastructure Reit | 0.0% | $2.38 | -5.6% | -14.7% |
IFT | Infratil | 0.0% | $10.69 | -5.4% | 11.6% |
AD8 | Audinate Group | -0.5% | $2.15 | -6.9% | -47.0% |
NXL | Nuix | -0.9% | $1.70 | -6.1% | -6.1% |
OCL | Objective Corporation | -1.0% | $5.71 | -5.9% | -65.5% |
MP1 | Megaport | -3.1% | $18.78 | -9.9% | 65.5% |
Metals rally lifts mining ETFs overnight
[8:59 am] It was a strong overnight session for commodities, with precious and base metals rallying across the board.
Platinum up 2.8% to $1,686.90/oz, with silver up 2.7% to $60.78/oz and palladium up 2.1% to $1,148.01/oz
Gold up 1.5% to $4,194.15/oz
Zinc up 3.2% to $3,799.98/t
Copper up 2.5% to $6.76/lb, with nickel up 1.4% to $15,689.78/t and aluminium up 0.4% to $3,041.10/t
Global X Copper Miners ETF up 4.3%, leading the pack, with the VanEck Gold Miners ETF up 3.0% and Global X Silver Miners ETF up 2.6%
VanEck Rare Earth and Strategic Metals ETF and Global X Uranium ETF lagged, up just 0.6% and 0.9% respectively
Goldman flags upside risk to oil as risk premium nears record
[8:54 am] Goldman Sachs sees upside risk to its Brent forecast if geopolitics keeps the oil risk premium elevated for longer, after updating its price model to capture very low inventories outside the OECD.
Risk premium of US$22/bbl in September, the second highest monthly reading on record after April 2026
Premium outlook assumes a gradual return to the historical average of zero, though it may stay elevated until there is a clear diplomatic resolution
Premium drivers include supply disruption fears and portfolio hedging, as disruptions lift inflation and Treasury yields and weigh on bonds and equities
Global visible stocks are near their lowest since at least 2017, keeping Brent above $100 despite a recovery in Persian Gulf exports
Model update adds global stocks outside OECD commercial storage, after the Brent timespread rose US$30/bbl YTD while OECD commercial stocks barely moved
Tanker squeeze replaces crude shortage as oil’s key pressure point: JPMorgan
[8:53 am] JPMorgan says October’s oil market looks a lot like April’s, but the problem has shifted from a shortage of crude to the cost of moving it.
Delivered crude prices are back at spring highs, with European refinery margins turning negative again and the risk of run cuts rising
Hormuz flows jumped to 12mbd in September from around 7.5mbd in July and August
VLCC fleet stretched with 766 of 923 in active use by September, while 124 Iranian VLCCs (13% of the fleet) are largely unavailable due to US sanctions
Longer voyages from ship-to-ship transfers taking up to 10 days and rerouting around higher-risk areas mean each tanker completes fewer trips
Middle East crude (ex-Iran) now needs an extra 35 VLCCs, 13 Suezmaxes and 10 Aframaxes vs the 2025 average, with VLCC employment elsewhere down 16 vessels
Smaller tankers are filling the gap outside the Middle East, with Aframax employment up 141 vessels (23%) and Suezmax up 52 (11%) vs the 2025 average
Oil holds above US$100 as Middle East attacks offset Trump’s strike pause
[8:50 am] Escalating attacks on shipping and Saudi Arabia kept Brent anchored above US$100 a barrel, outweighing Trump’s pledge not to strike Iran before the US midterms.
Brent up 0.4% to US$104.29 on Friday after jumping ~3% on Thursday
Trump pledge not to attack Iran before the 3 November midterms, citing “productive discussions”. Iran is reviewing a US response to its proposal to reopen Hormuz within seven days
Putin relayed Tehran’s vision for ending the war to Trump after meeting Iranian President Pezeshkian, according to the Kremlin
Missile capacity preserved, according to Western officials, who say Iran’s factories are replenishing arsenals with Russia also supplying missiles. The White House rejected the assessment
Tanker attacks hit at least 10 vessels in the past week, with tanker hire costs at about $1.2m a day vs less than $50,000 before the war
Houthis strike Riyadh airport on Saturday, killing at least 12, wounding more than 300 and cancelling 600+ flights, with fresh strikes on Sunday
US weighs joining Saudi strikes on the Houthis, with Trump saying “We may”, after rejecting two Saudi requests last month
Dated Brent topped $135 on Thursday, the highest since April, though Aramco will supply European refiners all the November crude they requested after allocating none last month
Russia to resume diesel exports under Trump-Putin deal
[8:49 am] Russia will partially lift its diesel export ban after Trump struck a supply deal with Putin aimed at easing record US fuel prices ahead of the midterms.
Supply schedule of more than 300,000 tons immediately, 500,000 tons in November and 1m tons thereafter, followed by another 3m tons depending on refinery conditions, according to Trump
Export ban eased with Russia allowing 500,000 tons of exports from Saturday, partially reversing curbs in place since January
Sanctions waived on Russian diesel by the US Treasury through April 2027
US diesel above US$6 a gallon for the first time, with heating oil futures falling as much as 5% in post-settlement trade on the news
Zelenskyy condemned the deal, saying “Gifts to Putin will not bring peace or any benefit to the civilized world”
Hurricane Isaias shut in about 72% of Gulf of Mexico crude output, with nearly 500,000 bpd of refining capacity in its path
RBI ramps up rupee defence as currency nears record low
[8:49 am] The Reserve Bank of India unveiled its strongest currency support measures since the 2013 taper tantrum, days after hiking rates, with analysts viewing 97 per US dollar as its line in the sand.
FX risk reserve requires lenders to hold 20% of the notional value of each derivative trade above $2m with the RBI, mirroring a PBOC tool
Dollar window opened for state-owned oil refiners, while the limit on derivatives without an underlying exposure was cut to $5m from $100m
Rupee down 7% YTD, the worst performer in Asia, closing Friday just above its 96.965 record low
Reserves drained by $51bn in four weeks, after a record $133bn diaspora deposit drive lifted reserves to nearly $800bn
Foreign outflows from Indian equities top $30bn this year, with ANZ’s Dhiraj Nim saying “oil prices and capital flows will still decide the rupee’s direction”
Source: Bloomberg
Nvidia in talks to deepen Reflection AI ties
[8:47 am] Nvidia is in early talks to boost its investment in open-weight model developer Reflection AI or supply it with computing power.
Deal options reported by the FT include an acqui-hire, a chip supply deal or a bigger equity stake, potentially leading to an acquisition offer. No terms have been reached
Beam model Reflection’s first open-weight model launched this month, scoring comparably to China’s Z.AI GLM-5.2 on reasoning benchmarks
Reflection valuation talks to raise $2.5bn at $25bn (WSJ), alongside billion-dollar compute deals with SpaceX and Nebius
Nvidia dealmaking follows its $13bn Hugging Face acquisition in September and a roughly $20bn licensing pact with Groq
Source: Bloomberg
History favours more S&P 500 gains as bull market turns four
[8:46 am] The US bull market turns four today and strategists say history points to further upside into year-end.
Truist’s Keith Lerner says it is the seventh of 11 bull markets since the 1950s to reach four years, with its 119% gain below the 184% average
Fifth-year returns averaged 12% with a median of 15% among bull markets that reached this stage
Midterm seasonality The S&P 500 has risen in 21 of the last 23 midterm cycles from one month before to two months after the vote, with a 7% median return (Deutsche Bank)
Exceptions in 1978 and 2018 were both driven by rising rates, but Deutsche’s Jim Reid notes neither had a blockbuster earnings season about to begin
Q3 earnings growth of 29.5% expected for the S&P 500, which would be a third straight quarter above 25%
Semis and hardware account for about 40% of YTD upgrades to 2026 S&P 500 earnings estimates and 75% for 2027 (Barclays)
Source: Yahoo Finance
OpenAI eyes $70bn revenue run-rate after report rattles chip stocks
[8:45 am] OpenAI has told investors it expects annualised revenue to reach at least $70bn by year-end, easing concerns sparked by a report its sales were running well short of estimates.
Annualised revenue was about $50bn at the end of September, with growth driven largely by enterprise
Measurement gap The FT reported the shortfall came from investors applying Anthropic’s method, which accounts for cloud provider sales differently
Chipmakers sold off on Thursday’s report, with a gauge of chip giants down 3.4% and the Nasdaq 100 down 1.4%
Anthropic hit $65bn in annualised revenue by end of July and could IPO as soon as November, while OpenAI has pushed its listing to at least next year
Fundraising talks for $30bn or more at a $1.4tn pre-money valuation, after raising $122bn in March at an $852bn post-money valuation
US telcos sink as SpaceX buys spectrum for Starlink Mobile push
[8:44 am] America’s big three carriers tumbled after SpaceX agreed to buy low-band spectrum it says paves the way for Starlink Mobile to become a major US carrier. SpaceX shares rose 1.3%.
Grain Management portfolio of up to 14 MHz of paired 800 MHz spectrum, subject to FCC approval
Carriers hit with T-Mobile down ~13%, AT&T ~10% and Verizon ~9%, while Crown Castle rose ~12%, American Tower ~8% and SBA ~6% on hopes of tower buildouts
Evercore ISI said “The carriers’ best argument just got weaker” but called it “more of a coverage fix than a capacity solution”
Spectrum gap Even including EchoStar’s 65 MHz, SpaceX would hold about 79 MHz vs 280 to 380 MHz each for the big three
TD Cowen said SpaceX still likely wants an MVNO first and “could be bluffing”
Timeline Next-gen mobile satellites start flying in 2027 with 5G-quality service from 1H28, after the FCC approved 15,000 Gen2 Starlink Mobile satellites this week
Delta slashes FY26 guidance as fuel bill soars
[8:43 am] Delta Air Lines missed ests for the first time in two years as a $6 billion increase in full-year fuel costs swamped strong premium demand. Shares closed flat.
Adjusted revenue up 16% to $17.58bn vs $17.76bn ests (1% miss)
Adjusted EPS of $1.72 vs $1.82 ests (5% miss)
Premium revenue up 18% to $6.82bn, outpacing 12% growth in main cabin revenue to $6.8bn
Fuel bill up 62% to $4.1bn, including $500m above July guidance
FY26 adjusted EPS guidance cut to $5.10 to $5.60 from $6.50 to $7.50, with the midpoint down 24%. Q4 guidance also came in below ests
Free cash flow guidance cut to $2.5bn from $3bn to $4bn
Q4 revenue forecast to rise 20% year-on-year, with CEO Ed Bastian saying “The consumer response continues to be quite strong”
Good morning!
[8:25 am] ASX 200 futures are up 37 pts (+0.42%). Here's what happened overnight:
Wall Street capped a volatile week higher, with tech rebounding from Thursday's AI wobble and the S&P 500 finishing within reach of a record ahead of bank earnings
S&P 500 (+0.59%), within 0.09% of the 6-Oct record
Nasdaq (+0.64%), Dow (+0.83%), Russell 2000 (+0.46%)
US weekly recap – S&P 500 (+1.15%), Nasdaq (+0.64%), Dow (+0.93%), Russell 2000 (-0.91%)
Trump's diesel deal with Putin waived Russian sanctions through April 2027, and Moscow partially lifted its export ban over the weekend
Middle East risks flared over the weekend after a Houthi strike killed 12 at Riyadh's airport, while Bloomberg reported Russia is supplying Iran with missiles