ASX 200 Live Today - Thursday, 1st October
The S&P/ASX 200 is set to fall after US stocks experienced an abrupt last minute selloff. Here are today's top stories.
Today’s ASX 200 Updates
Welcome to our live ASX coverage for Thursday, October 1. Expect a high volume of posts pre-market and more periodic updates throughout the day. We'll be wrapping the blog up around 2:00 pm AEST. Let us know how we can make it even better.
ASX 200 slumps almost 2% as relief rally unwinds
[2:05 pm] That's a wrap, and it's rough out there. The ASX 200 is down 170 points (-1.93%) and still trading around intraday lows, with so few constituents in the green you could almost count them on two hands.
There's not much else to highlight. As it turns out, the market's recent bounce, particularly Wednesday's ~0.9% rally, was largely a relief rally after the RBA's Tuesday decision proved no more hawkish than what was already priced in. It began late on Tuesday, when the ASX 200 recovered from a ~0.2% loss in the last 30 minutes of trade to finish 0.34% higher, after Governor Bullock said she "hopes" the fourth rate hike of 2026 will be restrictive enough to bring inflation back down. The rally then carried into Wednesday as CPI data came in largely in line with expectations, sending the rate-sensitive 3-year yield down as much as 7bps before it clawed back to close fractionally higher at 4.95%.
Come today, the market has realised nothing has changed. Yields show little sign of falling back below key thresholds, breadth remains challenged, and the bounce looks to have been nothing more than that.
ASX 200 tumbles to near four-month low
[1:30 pm] The ASX 200 is currently down 174 pts (-1.98%), trading at the lowest since 10 June. Absolute carnage out there, with all sectors red and 185 constituents (92.5%) trading lower.
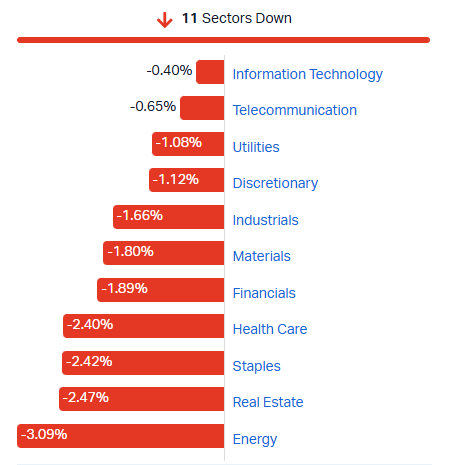
S&P/ASX 200 sectors (Source: Market Index)
Copper steadies as backwardation signals tight supply
[1:27 pm] Traders are focused on potential supply shifts as a Chinese national holiday thins trading volumes.
LME copper up 0.1% to US$14,421 a tonne, trimming a minor drop in the prior session after weak Chinese industrial earnings weighed on prices this week
Spot copper is back at a premium to three-month futures, a sign of tight supply last seen in August on concerns over US tariffs on refined metal
A strike at an Antofagasta site may hit Chilean output, while Panama's government has proposed resuming production at a giant mine
Iron ore down 0.7% to US$92.80 a tonne in Singapore, with the Dalian Commodity Exchange closed for a public holiday
Source: Bloomberg
Data#3 guides to at least 40% 1H profit growth, well ahead of ests
[12:42 pm] The upgrade sits well ahead of Macquarie ests, though one-off transactions and timing benefits mean profit will now be skewed to the first half.
1H FY27 gross profit up more than 15% to above $165.5m vs $164.5m ests (at least 1% beat)
1H FY27 PBT up more than 40% to above $46.9m vs $39.1m ests (at least 20% beat)
One-off larger transactions, stronger Infrastructure and Software Solutions activity and the timing of planned investment spend are lifting the half, along with about $1.5m of above-expectation interest income
FY27 PBT now expected to be skewed to 1H, vs ests that had 2H PBT of $49.0m ahead of 1H's $39.1m
Business update due at the AGM on 28 October, with 1H results and the interim dividend on 22 February 2027
This update was announced at 12:00 pm AEST. Data#3 shares were briefly halted and resumed trading at 12:11 pm. The stock gapped up from a ~1.8% gain before the halt to 7.4% ($11.75) and rallied as much as 23.3% ($13.74) by 12:27 pm.
Company page: Data#3 (DTL)
RBA flags AI boom and bond markets as top stability threats
[11:51 am] The RBA's October Financial Stability Review says domestic cyclical risks aren't systemic at present, with global and operational threats now the most prominent concerns.
Rising sovereign debt and leveraged hedge fund activity in government bond markets raise the prospect of a disorderly sell-off, with yields also pushed higher by competition from AI-related corporate bond issuance
The AI investment boom is increasingly debt-funded, including some circular financing arrangements, and a shift in sentiment on hyperscaler profitability could trigger a sharp repricing of low risk premia
Frontier AI has made cyber threats more complex, with the RBA warning that an attack timed to coincide with market stress could undermine confidence in the system
ASX's Austraclear has yet to establish adequate contingency arrangements for a prolonged outage, making it a supervisory priority for the RBA
Bank CET1 ratio of 12.4% at June would fall only to about 11.6% in a very adverse downturn scenario
About 2% of variable-rate owner-occupiers are in cash flow shortfall, with the median mortgagor holding buffers covering more than a year of repayments
Company insolvencies remain elevated in hospitality, construction and transport, with one large developer's administration set to spike September quarter figures
Banks' drawn exposure to private credit is at most 2.8% of assets, with the actual figure likely much smaller
Source: RBA
Macquarie trims Liontown target on higher costs and slower ramp
[11:45 am] The analysts see a bigger Kathleen Valley expansion, though output arrives later and costs are higher than it had assumed.
Outperform retained with the target cut 5% to $1.20, while EPS forecasts are cut by 35% for FY28 and 40% for FY29
Processing capacity lifts to 4.2Mtpa, 5% above the prior 4.0Mtpa plan, though construction completion in 2Q FY29 is later than the broker's 4Q FY28 assumption
FY30-34 production target of about 780ktpa of SC5.4 is modestly above the broker's 753ktpa estimate, partly offset by a slower ramp
FY30-34 FOB costs guided at $840-920/t in real terms, well below FY27's $1,050-1,250/t, though the midpoint is about 10% above the broker's assumption
Expansion capex of $389m is in line with the broker's $390m and will be funded from $561m cash and operating cash flow, reducing near-term equity risk
The 2.5-year payback assumes consensus long-term SC6 pricing of US$1,495/t vs the broker's US$1,350/t, leaving returns sensitive to lithium prices
Company page: Liontown Resources (LTR)
UBS cuts REA target to $164 on listings caution
[11:43 am] The broker views the Distilled acquisition more constructively than past offshore M&A, but sees Australian listing volumes as the bigger debate.
Neutral rating reiterated, with the target cut 7% to $164 from $177 after adding the Distilled stake at $409m and lifting the risk-free rate to 5% from 4.5%
The 16.4x EBITDA price looks full, in line with REA's own multiple and a 60% premium to listed global peers, though Distilled is growing in the high teens with 60% EBITDA margins
Irish listing take rates are about 10-20% of REA's 20bps, with vendor-paid listings already at 25%, up from low single digits four years ago
The 35% stake is 1-2% EPS accretive over FY27-FY29, though it leaves less room for near-term capital returns
FY27 listings are forecast to fall 6%, vs a 3% fall in ests, with channel checks pointing to a softer start to spring selling
FY27 yield growth of 11% is maintained, with downside risk from negative geographic mix and some agents downgrading packages
Company page: REA Group (REA)
ASX 200 erases yesterday's gains as bond yields climb
[11:38 am] The ASX 200 is down 100 points (-1.14%), more than wiping out yesterday's 80-point (+0.92%) gain. Today's session feels like a case of "hang on, nothing has actually changed". The policy-sensitive 3-year yield finished fractionally higher on Wednesday after reversing a sizeable 7bp intraday decline, and it's up another 3bps today to 4.98%. Overnight, US 10 and 30-year yields continued their near-vertical climb to multi-decade highs, while Brent is still trading above US$100 a barrel. In hindsight, Wednesday's session echoes Bullock's comment about "the hope here is that this will be restrictive enough... to bring things down."
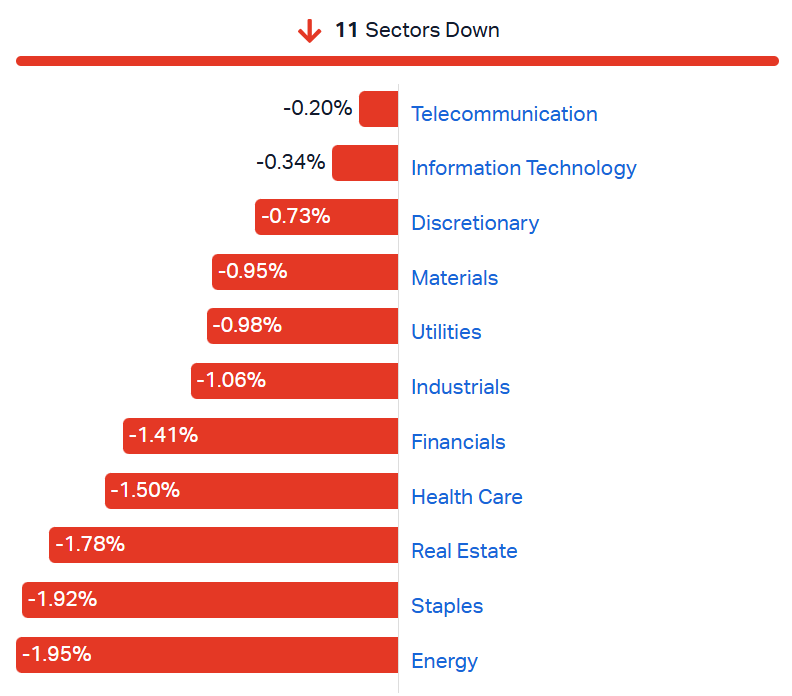
S&P/ASX 200 sectors (Source: Market Index)
China's property slump deepens despite fresh support measures
[11:37 am] Beijing's latest mortgage subsidies came in narrower and smaller than expected, five years into the downturn.
Mortgage-interest subsidies for first-home buyers are worth 1 percentage point a year for up to five years, limited to homes under 120 sqm costing no more than 1.5m yuan
Used home prices in top-tier cities were down more than a third as of July, with smaller cities down further
China Vanke posted a record 89bn yuan (US$13bn) loss last year, taking two-year losses above 130bn yuan
Bank bad debt hit a record 3.7tn yuan at the end of June, with Fitch warning it could worsen in 2026
UBS estimates 3.3m homes could be underwater by 2027, putting up to 232bn yuan of loans at risk
Household debt was near a record 137% of disposable income at the end of 2025, with former finance minister Lou Jiwei warning falling home values will weigh on consumption and deepen deflation
Source: Bloomberg
Top ASX 200 gainers
[10:29 am] A mix of software and uranium names top the leaderboard in early trade.
Ticker | Company | % Chg | Price | 1 Week | YTD |
|---|---|---|---|---|---|
360 | Life360 | 3.6% | $19.62 | -1.9% | -39.1% |
PDI | PDI Gold | 2.5% | $5.00 | 22.0% | 37.0% |
SLX | Silex Systems | 1.9% | $4.29 | -13.0% | -49.1% |
NXG | Nexgen Energy | 1.6% | $13.11 | -9.2% | -6.2% |
DYL | Deep Yellow | 1.5% | $1.19 | -26.7% | -35.5% |
JHX | James Hardie | 1.2% | $36.74 | -10.5% | 18.5% |
NWS | News Corp | 0.9% | $45.66 | -4.5% | 2.6% |
NEU | Neuren Pharmaceuticals | 0.9% | $20.53 | 6.1% | 10.3% |
PNI | Pinnacle Investment Management | 0.7% | $13.38 | -19.6% | -21.6% |
TNE | Technology One | 0.7% | $29.16 | -9.3% | 5.8% |
Top ASX 200 losers
[10:29 am] Lithium and gold names lag in early trade, while Lynas tanks on its Meteoric takeover.
Ticker | Company | % Chg | Price | 1 Week | YTD |
|---|---|---|---|---|---|
LTR | Liontown | -10.0% | $0.84 | -29.1% | -46.7% |
LYC | Lynas Rare Earths | -5.7% | $13.04 | -16.6% | 5.1% |
COH | Cochlear | -5.4% | $132.12 | 0.5% | -49.4% |
IPX | Iperionx | -5.0% | $2.39 | -17.8% | -56.7% |
YAL | Yancoal Australia | -4.7% | $5.74 | -7.8% | 15.2% |
SUN | Suncorp Group | -4.3% | $19.12 | 2.5% | 8.2% |
CNI | Centuria Capital Group | -4.0% | $1.22 | 0.0% | -39.2% |
CMM | Capricorn Metals | -3.8% | $14.33 | -12.2% | 2.4% |
EOS | Electro Optic Systems | -3.7% | $10.84 | 10.5% | 14.8% |
ELV | Elevra Lithium | -3.5% | $5.45 | -32.4% | -32.1% |
Brazilian rare earths plays rally on Lynas-Meteoric deal
[10:20 am] Lynas' $968 million bid for Meteoric has sent other ASX names with Brazilian rare earths exposure higher this morning.
Viridis Mining (VMM) up 12% to $3.74
St George Mining (SGQ) up 6.5% to 6.6 cents
Brazilian Rare Earths (BRE) up 5.5% to $3.83
Power Minerals (PNN) up 4.2% to 12.5 cents
Meteoric up 50% to 25.5 cents, about 5% below the implied offer value of 27 cents
Lynas falls 6% as market weighs Caldeira build cost
[10:11 am] Lynas is trading sharply lower in early trade as shareholders weigh a sizeable resource uplift vs. a hefty development bill attached.
Lynas down 6% to $13.00 in early trade after announcing the $968m all-scrip deal for Meteoric
Caldeira's DFS noted US$498m capex, which Lynas will effectively inherit, at a time when bringing new projects into production is easier said than done
Meteoric had just $37.8m cash at 30 June 2026, leaving Lynas to shoulder most of the build cost
Debt support remains non-binding, including an EXIM Bank letter of interest for up to US$250m for US-origin equipment and services and a conditional EFA letter of support for up to US$50m for Australian contractors
The capex bill equates to about A$750m, or more than 60% of Lynas' $1.2bn cash buffer, if those facilities don't firm up
Company page: Lynas Rare Earths (LYC)
Yancoal completes US$1.85bn Kestrel acquisition
[9:40 am] The deal adds a long-life Bowen Basin metallurgical coal asset, with earnings contributions starting today.
Upfront cash consideration of US$1.85bn was paid for the 80% interest in Kestrel, subject to customary completion adjustments
Funding came from available cash and an initial draw on the five-year US$1.2bn acquisition loan facility, with a US$200m working capital facility undrawn
Yancoal had a A$2.1bn cash balance at 30 June 2026
Contingent payments of up to US$550m are due if the benchmark coal price exceeds US$225/t in any of the first five years after completion
Kestrel production, revenue and earnings will be recognised from 1 October 2026
Company page: Yancoal (YAL)
Lynas pays a chunky premium for a big resource lift
[9:34 am] Here are a few more takeaways from what's shaping up to be the biggest announcement of the week.
Meteoric holders get just 5.9% of the combined group, while Caldeira lifts Lynas' Measured and Indicated TREO resources by about 79% and its Ore Reserves by about 26% (sounds like a pretty good trade off)
Caldeira's 3,862t of annual NdPr equals about 53% of Lynas' FY26 output of 7,260t, and adds 127t of DyTb a year plus a third jurisdiction beyond WA and Malaysia
The A$968m price tag sits below Caldeira's US$847m (A$1.21bn) spot post-tax NPV, and well below the US$2.72bn (A$3.92bn) NPV on forecast pricing
Caldeira capex of US$498m is well covered by Lynas' $1.2bn in cash and short-term deposits, with the all-scrip structure keeping the balance sheet intact
Capex up 12.5% since the PFS, contingency almost halved to US$45m and a first move into ionic clay are reminders that development is easier said than done (just look at Arafura, down 33% YTD)
Brazilian Rare Earths (BRE) and Viridis Mining (VMM) are the obvious ASX names to watch amid chatter about rare earths M&A in Brazil
Company pages: Lynas Rare Earths (LYC), Meteoric Resources (MEI)
Lynas to buy Meteoric for $968m in all-scrip deal
[9:18 am] The deal adds Brazil's Caldeira project, the largest known ionic clay rare earths resource outside China.
Exchange ratio of 0.0207 Lynas shares per Meteoric share implies an equity value of $968m, on a fully diluted, 60-day Lynas VWAP basis
The implied $0.286 per share is a 68.4% premium to Meteoric's last close of 17 cents
Caldeira would lift Lynas' Measured and Indicated TREO resources by about 79% and Ore Reserves by about 26% on a pro forma basis
The DFS production target implies average annual output of about 3,862t of NdPr and 127t of DyTb over Caldeira's life of mine
Lynas expects the deal to be accretive to NAV, resources, reserves and future NdPr and DyTb feedstock capacity
The Meteoric board unanimously recommends the scheme, absent a superior proposal and subject to an independent expert, with directors holding 2.6% intending to vote in favour
Company pages: Lynas Rare Earths (LYC), Meteoric Resources (MEI)
AFIC switches to quarterly dividends with 37cps FY27 guidance
[9:15 am] The listed investment company is responding to shareholder feedback that more frequent income payments would be useful.
FY27 ordinary dividend guidance up 1.9% to 27cps fully franked, from 26.5cps in the prior year
Special dividend of 10cps fully franked lifts the total FY27 payout to 37cps
Ordinary dividend yield of 4.1% (5.8% grossed up), or 5.6% (7.9% grossed up) including specials, based on the 30 September share price
First quarterly dividend of 9.25cps, made up of 6.75cps ordinary and 2.5cps special, is payable 12 November to holders on the register at 16 October
Specials after FY27 will depend on ordinary earnings, franking balances and realised capital gains, so are subject to variability
Company page: Australian Foundation Investment Company (AFI)
Acusensus secures second NSW speed camera extension worth $16m
[9:08 am] The latest six-month extension keeps the contract running while the tender for a long-term replacement remains open.
Transport for New South Wales (TfNSW) exercised its second option to extend its mobile speed camera agreement with the AI-enabled road safety technology developer by six months, to 30 June 2027
The extension is worth about $16m excluding GST, on the same terms as the first extension
The first extension pushed the original 30 June 2026 expiry out to 31 December 2026
Tender for a new long-term contract with TfNSW remains ongoing
Company page: Acusensus (ACE)
Transurban buys out CPPIB's Sydney toll road stakes for $4.5bn
[9:07 am] The debt-funded deal lifts its exposure to three core Sydney motorways without tapping shareholders.
Total cash consideration of $4.5bn including stamp duty covers CPPIB's 25% of NWRG and 10.5% of STP
NWRG stake rises to 75% from 50%, covering Westlink M7 (concession to 2051) and NorthConnex (2048)
STP stake rises to 60.5% from 50%, covering WestConnex (concession to 2060)
No impact on FY27 Free Cash or distributions is expected, with immaterial short-term dilution to Free Cash per security before growing accretion over the medium and long term
Funding comes from committed debt facilities, to be refinanced into longer-term debt, with no equity required and Baa1/BBB+ ratings expected to remain unchanged
Completion is expected in calendar 2027, subject to ACCC clearance and contractual approvals
Company page: Transurban (TCL)
Marmota and Kantra lead today's explorer results
[9:06 am] Near-surface gold, thick copper intercepts and a third gold pour feature in today's drilling and production updates.
Marmota returned 4m @ 15g/t gold from 24m within 16m @ 4.2g/t in maiden drilling south of Greenewood, with initial 4m composite results from only 15 of 84 sections received
Kantra Copper hit 70m @ 1.18% Cu and 0.24g/t Au from 507m in underground drilling at Nugent, including 38m @ 1.46% Cu
Azzuro Resources intersected 7m of semi-massive to massive sulphides with visible copper from 72.3m at Red Hill in Mongolia, 70-80m north of known mineralisation, with assays due in 4-5 weeks
Exultant Mining hit 11.75m @ 9.12g/t Ag and 1.43% Zn+Pb from 240.15m at Balerion, with the main shear thickening about 57% down dip, though focus now shifts to its Black Hammer Cu-Au project
Broken Hill Gold completed a third pour of 5.43kg (174oz) of doré at an estimated 70:30 gold to silver ratio at White Dam, with irrigation to pause in late October for a full pad and pond reline
Company pages: Exultant Mining ([ticker]), Azzuro Resources (AZ9), Broken Hill Gold (BH6), Marmota (MEU), Kantra Copper (KAN)
Trump unveils US$200bn South Korean investment package
[9:00 am] Seoul says each project must pass commercial viability tests, with the Alaska LNG leg still only under review.
The US$200bn commitment is the first set of projects under Seoul's broader US$350bn package, agreed alongside last year's trade deal that cut US tariffs on most Korean goods to 15%
A US$22.3bn Texas gas power complex of 6,472MW will supply AI data centres, led by NextEra Energy and Related Companies, with first power in 2029 and full completion by 2032
A nuclear framework could allocate up to US$120bn to eight reactors, six Westinghouse AP1000s and two Korean APR1400s, though each plant needs separate approval
Korean investors plan to take a stake of at least 5% but below 10% in Westinghouse, alongside an advance payment of up to US$10bn by year-end for long-lead reactor components
Alaska LNG will not proceed unless commercially viable, according to Seoul, which is reviewing it on energy security grounds and cites risks including uncertainty over Australian supplies
Returns will be split 50/50 until Seoul recovers its principal plus interest, then shift to 90% for the US, with Korea's investment capped at US$20bn a year
I wonder if this deal/headline can drive some positive flows into local uranium names today.
Source: Reuters
Micron beats and guides well above ests
[8:55 am] AI-driven memory demand pushed fiscal fourth-quarter revenue to almost four times the prior year. Though Micron shares are trading just fractionally higher after hours.
Revenue up 379% to US$54.23bn vs US$51.07bn ests (6% beat)
DRAM revenue up 343% to US$39.8bn, 73% of total sales
Net income up 1,078% to US$37.7bn
Adjusted EPS of US$33.42 vs US$31.61 ests (6% beat)
1Q FY27 revenue guidance of about US$61.5bn vs US$57bn ests (8% beat)
1Q FY27 adjusted EPS guidance of US$38.15 vs US$35.40 ests (8% beat)
Management flagged much tighter memory markets through 2028 and lifted its capex plans after revenue almost quadrupled in the quarter.
On the outlook: "We expect FY27 to be even better. Industry demand has strengthened since our last earnings call, and we expect memory and storage supply-demand conditions to be much tighter in calendar 2027 and 2028 than they were in 2026"
On supply and demand: "Even with additional industry DRAM clean room space plans, with robust demand trends including new upside requests from customers, we do not have line-of-sight to when supply and demand will return to balance"
On HBM pricing: "We have completed agreements for the vast majority of our calendar 2027 HBM bit supply with significant price increases year over year, narrowing the gross margin gap with conventional DRAM"
On capex: "We plan to increase our capex in FY27 versus prior plans... A majority of the increase is for construction capex, most of which is to help accelerate clean room space availability in late calendar 2028 and beyond"
German inflation jumps to near three-year high
[8:54 am] Energy costs drove the acceleration, adding pressure on the ECB to lift rates again.
CPI up 3.3% year-on-year in September vs 3.2% ests, the highest in almost three years
Core measure unchanged at 2.4%, with Bloomberg Economics seeing limited pass-through so far
Spain's inflation hit 5% as France and Italy also surprised higher, with euro area data due 2 October expected to jump to 3.7%
ECB has hiked twice so far, with traders favouring December for the next move even as doves Stournaras and Demarco keep October open
Lagarde backed a "measured response" and said second-round effects are absent so far
Source: Bloomberg
Trump's Section 301 tariffs face court challenge
[8:53 am] A second legal fight over the president's global duties is underway after the Supreme Court struck down his earlier blanket tariff.
Court of International Trade panel heard arguments Wednesday on whether Section 301 can be used to tariff nearly all US imports
80 countries including China, India and Japan have faced rates of 10% to 12.5% since late July, imposed on forced labour grounds
Previous 10% blanket duty was struck down by the Supreme Court, triggering US$168bn in refunds to importers
Liberty Justice Center, which won the Supreme Court case, argues the administration is misusing Section 301 to preserve a predetermined global tariff policy
A ruling could take weeks or months, with appeals possible to the Federal Circuit and ultimately the Supreme Court
Further duties likely from several pending Section 301 probes, on top of 50% duties on US$20bn of Canadian goods under a Depression-era law
Mideast crude flows near pre-war levels as refined products lag
[8:52 am] Tanker data and bank estimates show Gulf crude exports have largely recovered despite ongoing attacks on shipping.
Crude shipments at 98% of pre-war levels at 17.5m bpd, according to JPMorgan, while product flows sit at 3m bpd or 58%
Hormuz crude transits hit a seven-day average of 13.5m bpd as of Monday, matching the pre-war baseline, according to Kpler
Refined products through Hormuz at 677,000 bpd vs 3.6m bpd before the war, leaving combined flows at about 80% of the 17m bpd baseline
Goldman Sachs estimates Persian Gulf exports, including dark flows, recovered to 23.3m bpd last week, in line with the 2025 average, with the global market roughly balanced in September
More than 70% of crude crossing Hormuz in August switched tankers off the UAE or Oman under US military protection, while pipelines now carry about 40% of Gulf crude vs 17% pre-war
Iran received an official US response to its offer to reopen the strait within a week in exchange for lifting the blockade, releasing frozen assets and waiving oil sanctions, with the contents undisclosed
Trump publicly rejected the proposal days earlier and has told aides he expects to resume bombing Iran after the November midterms, according to the WSJ
Long-end Treasury yields push towards multi-decade highs
[8:51 am] Bond traders looked past the softer inflation print and turned their focus to Friday's payrolls data.
10-year yield up 5 bps to 5.29%, trading near 2007 highs after an early pullback
30-year yield up 6 bps to 5.63%, around its highest since 2002
2-year yield little changed at 4.89%
US core PCE cools to 3%, trimming October hike bets
[8:50 am] The Fed's preferred inflation gauge came in well below forecasts, helped partly by methodology changes to several components.
Headline PCE up 3.4% year-on-year in August vs 3.7% ests, with the 0.3% monthly gain in line
Core PCE up 3% year-on-year vs 3.3% ests and down from 3.3% in July, with the monthly gain of 0.2% below the 0.3% ests
BEA methodology changes to software, legal services and portfolio management pricing lowered July core PCE by 0.36 percentage points, leaving three-month annualised core at 2%
Personal spending up 0.9% vs 0.8% ests, while income rose 0.2% vs 0.4% ests
Q2 GDP revised up to 2.2% annualised from 1.5%, with real final sales to private domestic purchasers up 4.6%
October hike odds fell to about 37%, from more than 80% earlier this month, with markets pushing the next move to December after New York Fed President John Williams said there is "no need for urgency"
Good morning!
[8:29 am] ASX 200 futures are down 48 pts (-0.54%). Here's what happened overnight:
Wall Street's final session of Q3 ended with an abrupt last-minute selloff that wiped out an early rally sparked by cooler inflation data, capping a losing September for the S&P 500 and Dow
S&P 500 was up around ~0.3% in the last 30 minutes of trade and nosedived to finish (-0.25%) lower
Nasdaq (+0.24%), Dow (-0.86%) and Russell 2000 (-0.39%)
Softer core PCE and an upgraded Q2 GDP print cut bets on an October Fed hike, but long-dated Treasury yields held near two-decade highs
Micron's blowout result and guidance after the bell reinforced the AI memory boom heading into Q4