ASX 200 Live Today - Thursday, 8th October
The S&P/ASX 200 is set to fall as US equities slipped from record highs. Here are today's top stories.
Today’s ASX 200 Updates
Welcome to our live ASX coverage for Thursday, October 8. Expect a high volume of posts pre-market and more periodic updates throughout the day. We'll be wrapping the blog up around 2:00 pm AEST. Let us know how we can make it even better.
ASX 200 slips as bond yields climb and defensives find support
[2:15 pm] That's a wrap! The ASX 200 is down 52 points or 0.6%, slightly off session lows. It's a defensive session, with Energy leading the sector leaderboard as Brent edges 1.3% higher to US$102.20 a barrel, while Staples, Utilities and Telcos are also catching a bid.
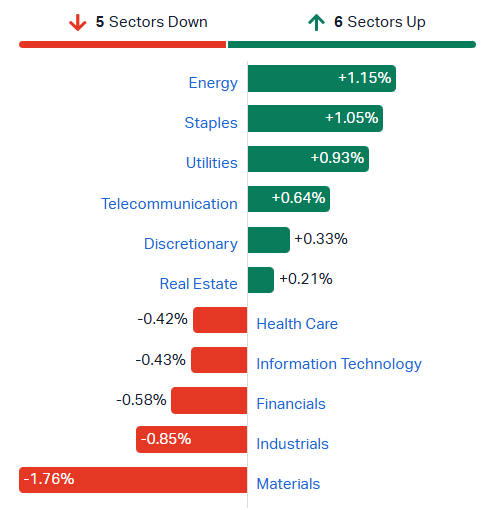
S&P/ASX 200 sectors (Source: Market Index)
Materials have recovered from an intraday fall of as much as 2.7%, following a broad-based sell-off in commodities (ex-Energy) overnight. Copper is staging a strong rebound, up 1.6% to US$6.78/lb and within 2% of its 22 September record close. However, the strengthening US dollar and still-climbing yields are capping the miners' ability to price in the rebound.
Australian bond yields are all trading fractionally higher. The 3-year is at 4.91%, still shy of its recent 5.1% peak, and the 10-year is at 5.40%, just below its recent 5.44% high. The 30-year has edged up to 5.88%, the highest since the benchmark launched in 2016. Yields have been extremely volatile in recent days, with 10 bp swings in either direction becoming fairly normal.
Overall, the market is on the defensive as yields continue to show no convincing signs of topping out and Brent ping-pongs around the US$100 a barrel mark. The small end of town continues to struggle, with the ASX Emerging Companies Index down 1.3% to its lowest level since 5 August. Still, the selling isn't as broad-based as in previous days, and defensives are finding some support.
Commodities bounce after overnight US dollar-driven sell-off
[1:53 pm] Commodities are rebounding across the board after a stronger US dollar weighed on resources overnight, with precious metals, base metals and energy all higher.
Palladium up 2.6% to US$1,144.89/oz and platinum up 2.0% to US$1,663.10/oz, recovering around half of their overnight declines of about 4.4%
Copper up 1.7% to US$6.79/lb, more than erasing its 0.2% overnight dip
Chinese markets resumed trading after their week-long National Day holiday. Chinese lithium futures are currently up 3.1% to 122,500 yuan a tonne.
UBS upgrades HUB24 and Netwealth to Buy, cuts AMP to Neutral
[1:39 pm] UBS believes the post-budget sell-off in specialty platforms has gone too far, with budget tax changes boosting super's appeal as a long-term savings vehicle even as higher bond yields weigh on near-term flows.
HUB24 upgraded to Buy with shares down about 34% this year and its forward P/E down to about 33x from 56x, a roughly 30% discount to its five-year average
Netwealth upgraded to Buy after a 35% share price fall, trading on about 29x forward earnings, a 40% discount to its five-year average
HUB24 preferred near term despite Netwealth's cheaper valuation, given its more defensive super mix and steadier margin outlook
AMP lowered to Neutral after a 96% rally since February, with stronger China partnership and platform flow momentum now largely priced in
Near-term flows expected to stay soft as advisers shift client portfolios toward cash and term deposits, with EPS forecasts cut 3% to 4% for HUB24 and 5% to 6% for Netwealth
Preferred fund managers are Pinnacle, where private credit concerns appear more than priced in, and Navigator, which offers growth uncorrelated to equity markets
Macquarie lifts Light & Wonder target, sees room to re-rate from 9x earnings
[1:38 pm] Macquarie returned from G2E with higher conviction that Light & Wonder can win share in North America, arguing its steep valuation discount to Aristocrat leaves room for a quick re-rating.
Target raised to $185 from $180, based on 15x 12-month forward earnings, a 25% discount to Aristocrat
Shares trade on 9x forward earnings, a 55% discount to Aristocrat, with improved game performance and deleveraging seen as re-rating catalysts
Forecasts sit at the low end of CY26 guidance and 10% below the CY28 US$2bn adjusted EBITDA target, leaving room for upside
North America forecasts raised for Gaming Ops and outright sales, citing improving game performance, new hardware and distractions at a key competitor
Grover is benefiting from regulatory changes and new markets, with New York due in early 2027
SciPlay has been in run-down since CY21, with Macquarie expecting new management to opt for a strategic review over running the business for cash
Company page: Light & Wonder (LNW)
Macquarie lifts Aristocrat target after US trip, sees Interactive as re-rating catalyst
[1:37 pm] Macquarie returned from more than 20 meetings at G2E in Las Vegas with higher conviction that Aristocrat can win market share across its North American land-based and online businesses.
Target raised to $67 from $65, based on 22.5x 12-month forward earnings, a 20% premium to ASX 300 Industrials
Medium-term EPS growth of 10% to 15% expected, with Macquarie forecasting a 13% constant-currency CAGR over FY26 to FY29
North America forecasts raised for Gaming Ops and outright sales, citing game performance, new hardware and distractions at a key competitor
Interactive to scale in 2027, with Macquarie forecasting FY29 revenue of US$959m vs the company's US$1bn target, supported by the Lightning Link and Dragon Link iCasino launches
iCasino market expanding, with Alberta recently opened, Maine coming and five other jurisdictions covering 12% of the US population working through legislation
Valuation range of 20x to 25x forward earnings seen as realistic vs the current 20x, with confidence in Interactive needed to reach the upper end
Company page: Aristocrat Leisure (ALL)
Asian wheat buyers cut forward purchases as Black Sea supplies dry up
[1:36 pm] Asian flour millers are buying wheat closer to delivery as Russian and Ukrainian attacks on shipping choke Black Sea exports, leaving them more exposed to further price spikes.
Forward cover shortened to December or closer to delivery for some Southeast and South Asian millers, vs the usual practice of buying up to six months ahead
Chicago wheat futures surged more than 30% in the two months to August to the highest since February 2023, before falling 13% in September
Russian wheat shipments plunged 75% in September and Ukraine's grain exports are down 26% this season, with the two accounting for more than a quarter of global wheat exports
Bulgaria and Romania, key alternative suppliers, are also under threat after ships were attacked in their economic zones
Southern Hemisphere harvests are due in the coming weeks, while India's lifting of its export ban in August has added some supply
US Wheat Associates' Joe Sowers warned prices could rise very quickly if the conflict drags on or another shock emerges
Source: Bloomberg
Maas Group shares plunge 30% on reports Firmus may change IPO terms
[1:04 pm] Maas Group shares are headed for their worst day on record after reports that Firmus may rework the terms of its planned float, seen as a key test of investor appetite for AI infrastructure.
Shares fell as much as 30.1% to $4.47, their lowest since 6 May, from Wednesday's close of $6.39
Reports earlier this week said Firmus could cut its IPO price from $11 a share after demand from overseas investors fell short of expectations
Maas told the ASX it was not aware of any undisclosed information in response to a price query, and said market speculation over whether the Firmus IPO will go ahead had weighed on investor sentiment
Maas holds a 3.2% stake in Firmus and supplies it through subsidiary JLE, after committing a further $300 million in August through ordinary and preference shares priced at $230 each
Firmus's planned $7.2 billion IPO would value the Nvidia-backed data centre operator at $44 billion, with OpenAI as an anchor customer
The float would be Australia's largest in nearly three decades and second only to Telstra's roughly $14 billion listing in 1997
Company page: Maas Group Holdings (MGH)
Uranium sector gives back yesterday's gains
[12:42 pm] Uranium stocks rallied yesterday after Google signed a 3.6GW nuclear power deal with Constellation Energy, but ASX uranium names are reversing those gains today. This is following a broad selloff across the commodity complex and a 4.4% fall in the NYSE-listed Global X Uranium ETF overnight.
Ticker | Company | % Chg | Price | 1 week | YTD |
|---|---|---|---|---|---|
DYL | Deep Yellow | -7.9% | $1.0 | -3.6% | -88.2% |
BMN | Bannerman Energy | -7.9% | $3.4 | -7.5% | -22.9% |
PDN | Paladin Energy | -7.2% | $8.6 | -9.8% | -64.1% |
EL8 | Elevate Uranium | -6.5% | $0.2 | -1.2% | -8.2% |
DEV | Devex Resources | -5.7% | $0.2 | -3.1% | -44.7% |
BOE | Boss Energy | -5.4% | $1.5 | 2.8% | 48.0% |
AGE | Alligator Energy | -5.1% | $0.0 | -0.3% | 2.0% |
AEE | Aura Energy | -5.1% | $0.1 | -13.2% | -2.9% |
NXG | Nexgen Energys | -4.8% | $12.8 | 2.4% | -24.6% |
PEN | Peninsula Energy | -4.2% | $0.2 | -7.8% | -10.4% |
T92 | Terra Critical Minerals | -2.6% | $0.0 | -2.6% | 1.5% |
LOT | Lotus Resources | -1.4% | $0.2 | -12.9% | -43.2% |
ASX up 4% after UBS lifts price target on futures trading boom
[11:35 am] UBS sees upside to market forecasts after a strong start to FY27, with interest rate futures trading leading growth across the exchange's main revenue lines.
UBS lifted its price target to $65.50 from $64.20 and kept its Buy rating, about 12% above the $58.35 close
Futures volumes rose 33% year-on-year in the September quarter, well ahead of 7% growth in cash equities turnover, with September alone up 44% on short-dated and three-year interest rate contracts
Other revenue drivers also improved, including an 8% rise in the value of trades cleared, 18% more settlement messages and a 12% rise in average Austraclear holdings
UBS's FY27 earnings forecast of $2.74 a share sits 4% above ests of $2.64, after the broker made modest upgrades of 0.6% to FY27 and 1.2% to FY28
Shares are up 22% year-to-date and trading at their highest level since May
Peru unexpectedly holds rates at 4.25% despite fastest inflation since 2023
[11:33 am] Peru's central bank left its key rate unchanged for a 13th straight month, with policymakers expecting a recent jump in inflation to prove temporary.
The central bank held its key rate at 4.25% on Wednesday, surprising nine of 13 economists surveyed by Bloomberg who had expected a quarter-point hike
Consumer prices rose 4.55% in September, the fastest pace since 2023, with rising food costs adding to the global energy shock
Inflation has been above the 1% to 3% target range for seven straight months, with policymakers preferring it near the 2% midpoint
The bank said it is watching core inflation, inflation expectations, economic activity and how long supply shocks last, and committed to taking the necessary actions to bring inflation back to target
Governor Julio Velarde said last month a rate hike could not be ruled out in coming months, with any move largely depending on El Niño weather, which is already hurting fishing and crop yields
Velarde expects inflation to finish 2026 at 4.2% before returning to target in 2027 as temporary pressures fade
Source: Bloomberg
Copper stocks dip despite flattish copper prices
[11:01 am] Copper miners are lower this morning after the NYSE-listed Global X Copper Miners ETF fell 4% overnight, even as copper prices held up against a broad selloff across the commodity complex. The fall came as the US Dollar Index rose 0.4%, extending its rally since early September to 3.5% and taking it to its highest level since April 2025.
Ticker | Company | % Chg | Price | 1 week | YTD |
|---|---|---|---|---|---|
CBE | Cobre | -6.0% | $0.3 | -1.1% | -18.8% |
RIO | Rio Tinto | -2.9% | $161.9 | -0.2% | 40.0% |
AR1 | Austral Resources Australia | -2.9% | $0.1 | -2.6% | -34.4% |
AIS | Aeris Resources | -2.7% | $0.5 | -1.3% | 61.8% |
BHP | BHP | -2.5% | $60.9 | 3.6% | 23.7% |
CSC | Capstone Copper Corp | -2.4% | $13.9 | -2.8% | -23.1% |
29M | 29metals | -2.4% | $0.3 | -2.6% | 7.2% |
HCH | Hot Chili | -1.7% | $1.5 | -10.3% | -37.0% |
FFM | Firefly Metals | -1.6% | $1.6 | -2.6% | -8.0% |
SFR | Sandfire Resources | -1.0% | $22.2 | -1.0% | 33.7% |
KAN | Kantra Copper | -0.9% | $1.2 | -4.7% | -22.2% |
MC2 | Marimaca Copper | -0.8% | $8.2 | -11.7% | 19.3% |
S32 | South32 | -0.6% | $5.0 | -2.1% | 10.3% |
CYM | Cyprium Metals | 1.2% | $0.4 | -14.9% | 215.0% |
Top ASX 200 gainers
[10:33 am] The exchange operator (ASX) is higher this morning after UBS lifted its price target, while Arena REIT is extending yesterday's 13% gain. Energy and utilities stocks are also pushing higher in early trade.
Ticker | Company | % Chg | Price | 1 week | YTD |
|---|---|---|---|---|---|
ARF | Arena REIT | 5.5% | $2.5 | 17.5% | -30.3% |
ASX | ASX | 3.6% | $60.4 | 4.2% | 17.3% |
KAR | Karoon Energy | 2.9% | $1.6 | -0.6% | 2.6% |
BPT | Beach Energy | 2.4% | $0.9 | -2.3% | -26.9% |
ALD | Ampol | 2.4% | $44.3 | 1.4% | 38.8% |
RMD | Resmed | 2.1% | $32.6 | 2.2% | -9.8% |
HUB | Hub24 | 2.1% | $64.7 | 4.3% | -32.6% |
CPU | Computershare | 1.9% | $40.7 | 0.0% | 19.9% |
LNW | Light & Wonder | 1.9% | $112.4 | 4.6% | -27.5% |
XRO | Xero | 1.8% | $57.1 | -0.2% | -49.9% |
Top ASX 200 losers
[10:33 am] Uranium stocks are lower amid a broad selloff across the commodity complex and a sharp 4.4% pullback for the NYSE-listed Global X Uranium ETF overnight. This gives back the entirety of Wednesday's rally, after Google signed a 20-year power deal with Constellation Energy.
Ticker | Company | % Chg | Price | 1 week | YTD |
|---|---|---|---|---|---|
SLX | Silex Systems | -7.3% | $4.2 | 17.5% | -30.3% |
DYL | Deep Yellow | -7.3% | $1.1 | 4.2% | 17.3% |
EOS | Electro Optic Systems | -7.0% | $10.7 | -0.6% | 2.6% |
PDN | Paladin Energy | -5.9% | $8.8 | -2.3% | -26.9% |
LOV | Lovisa | -5.6% | $23.3 | 1.4% | 38.8% |
PDI | PDI Gold | -5.4% | $4.4 | 2.2% | -9.8% |
CIA | Champion Iron | -5.3% | $2.9 | 4.3% | -32.6% |
VUL | Vulcan Energy Resources | -5.1% | $1.5 | 0.0% | 19.9% |
JHX | James Hardie | -4.8% | $35.1 | 4.6% | -27.5% |
NXG | Nexgen Energys | -4.7% | $12.9 | -0.2% | -49.9% |
Ballard Mining enters trading halt pending capital raising
[9:56 am] Ballard Mining has requested a trading halt ahead of an announcement on a proposed capital raising.
Halt requested under ASX Listing Rule 17.1, pending an announcement regarding a proposed capital raising
Shares to resume trading on the earlier of the raising results announcement or the open on Monday, 12 October
This is despite a 24 September company presentation noting the company was "Funded to FID" and "de-risked balance sheet" (~$350m market cap, $62m cash at 30 June 2026).
Company page: Ballard Mining (BM1)
Black Cat hits 9.9m at 27.4g/t at Lynx as Raisebore target emerges
[9:55 am] Black Cat Syndicate continues to return high-grade hits from the near-surface Lynx Lode at Paulsens, with early drilling pointing to a second parallel structure about 600m away.
Best new Lynx intercept of 9.86m @ 27.38g/t gold from 107.44m, including 0.60m @ 186.27g/t, from surface drilling
Other Lynx results include 1.16m @ 37.78g/t from surface and 0.60m @ 19.45g/t from underground, consistent with previously reported intercepts
Initial Raisebore Vein drilling returned up to 0.30m @ 31.80g/t, with vein orientation supporting a Lynx-parallel structure
Historical Raisebore drilling included 13.10m @ 26.51g/t, with follow-up drilling planned
MD Chris Stone said the results will guide further drilling at Raisebore and "testing of other prospective structures" as mine development continues at Lynx
Company page: Black Cat Syndicate (BC8)
Titomic wins full-rate semiconductor production contract
[9:54 am] Titomic has progressed an unnamed semiconductor customer from low-rate initial production to a full-rate contract, marking a shift toward recurring manufacturing revenue.
Full-rate production contract awarded to Netherlands subsidiary Titomic Europe, following a low-rate initial production run awarded in 2025
Revenue of about $1.5m expected in 2027 at the current run rate
Potential to rise to about $3.2m in 2028, depending on customer requirements
Strategy of converting development and qualification programs into recurring production revenue, rather than relying on technology development and equipment sales
CEO Jim Simpson said Titomic is "moving from demonstrating what our technology can do to producing for customers at commercial scale"
Company page: Titomic (TTT)
Fortescue net debt more than triples as CMRG standoff weighs on sales
[9:27 am] Fortescue's balance sheet took a hit in the September quarter, with ongoing negotiations with China Mineral Resources Group (CMRG) leaving sales 3.9Mt short of shipments.
Iron ore shipments down 6% to 46.8Mt, including 2.5Mt from Iron Bridge, with maintenance and a scheduled port outload shutdown weighing on volumes
Iron ore sales of 42.9Mt fell short of shipments, reflecting ongoing negotiations with CMRG
Hematite realised price of US$80/dmt, or 82% of the average Platts 61% CFR Index
Net debt rose to US$2.8bn from US$0.9bn at 30 June, after the US$1.0bn final dividend, US$0.9bn of capex and a working capital build from higher inventory
Cash of US$3.2bn at 30 September
FY27 guidance unchanged for shipments, C1 costs and capex, subject to the CMRG negotiations
Company page: Fortescue (FMG)
Elevra signs three-year spodumene offtake with LG Energy Solution
[9:18 am] Elevra has locked in LG Energy Solution as a cornerstone customer for North American Lithium (NAL) concentrate, while keeping its exposure to spot spodumene prices.
Base volume of 240,000dmt of spodumene concentrate over three years from first shipment, expected in 2026
Deliveries ramp from 30,000dmt in 2026 to 60,000dmt in each of 2027 and 2028, then 90,000dmt in 2029
Up to 90,000dmt of optional volume on top, subject to agreement between both parties
Market-linked pricing adjusted for lithium content
CEO Lucas Dow said the deal gives Elevra "a committed customer for a meaningful portion of NAL's production" as it progresses the NAL expansion
Company page: Elevra Lithium (ELV)
Ramelius cash pile climbs to $768m as wet weather clips quarterly output
[9:16 am] Ramelius Resources built its cash and gold balance by 18% in the September quarter, while rain-delayed haulage from Penny left about 4,250oz sitting on the stockpile.
Gold production of 48,839oz, with wet weather disrupting haulage from Penny to the Mt Magnet mill and leaving 4,254 contained ounces stockpiled at the mine
FY27 guidance reaffirmed at 205,000oz to 225,000oz, with Q1 output at 23% of the 215,000oz midpoint
1Q27 underlying free cash flow of $60.2m
Cash and gold up 18% to $768.0m from $649.6m at 30 June, with the Edna May sale completing in September for $300m including $210m in cash
Buybacks of $18m in the quarter take the total to $159m of the $250m program
Rebecca-Roe Works Approval granted, leaving only routine Mining Act approvals outstanding for Roe
Company page: Ramelius Resources (RMS)
Megacap tech cushions Wall Street as leadership stays narrow
[9:14 am] The S&P 500 and Nasdaq limited their losses to 0.2% overnight as megacap tech held firm and Micron staged a sharp reversal, a reminder that market leadership remains concentrated in a handful of AI-linked names.
Amazon, Apple and Alphabet rose between 0.8% and 1.4% and Microsoft added 0.1%, even as the S&P 500 fell 0.2%
Micron jumped 4.0% to a US$1.23tn market cap, while Nvidia slipped 0.7% from its record high and Meta fell 2.3%
Micron reversed a 3.2% intraday decline, that's a ~US$85bn swing in market cap
Resource ETFs sink as US dollar hits 18-month high
[9:04 am] The US Dollar Index pushed above July highs last week, now trading at its highest since April 2025.
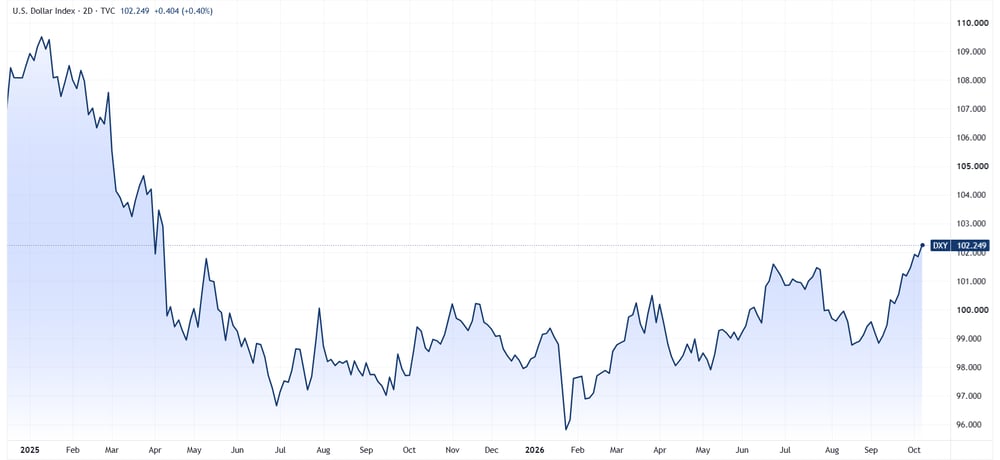
US Dollar Index (Source: TradingView)
The index rallied 0.4% overnight to 102.24, and moves of such magnitude tend to place downward pressure on resources. Palladium and platinum both tanked around 4.4% overnight, gold fell 1.2% to US$4,110/oz and copper slipped 0.2% to US$6.68/lb. This drove broad-based weakness across resource-related ETFs, including:
Global X Uranium ETF down 4.47% to $39.93
Global X Silver Miners ETF down 3.54% to $83.56
SPDR S&P Metals & Mining ETF down 3.14% to $104.84
VanEck Gold Miners ETF down 3.13% to $85.46
Global X Copper Miners ETF down 3.13% to $83.58
VanEck Rare Earth and Strategic Metals ETF down 2.99% to $61.88
Dollar nears year high as emerging markets snap rally
[8:58 am] The US dollar climbed toward its 2026 high on safe-haven demand as oil and Middle East tensions rose, ending a weekly rally in emerging market stocks and currencies.
Bloomberg Dollar Spot Index up 0.3%, paring a 0.5% gain, with nearly all G10 currencies weaker against the greenback
Euro down 0.5% to $1.12, pressured by energy prices and France's fiscal woes, after hitting its lowest since May 2025 earlier this week
Markets are pricing more than 70 basis points of Fed hikes through September 2027
MSCI EM stocks down 1%, with South Korea's Kospi down 2% in its worst session this month
India's rupee fell 0.3% despite the central bank's first rate hike in almost four years
SpaceX slips on $40bn debt raise for Nvidia chips
[8:55 am] SpaceX shares fell 2.5% on reports it is seeking $40 billion in debt to buy Nvidia chips, in what would be among the biggest debt financings of the AI buildout.
$40bn financing would be split into $10bn of bank loans and $30bn of investment-grade debt, with Apollo leading and PIMCO considering the deal
Colossus 1 and 2 data centres in Memphis are generating billions per month in recurring AI compute revenue
CFO Bret Johnsen said SpaceX is on track for $100bn ARR, with a new hosting deal adding about $13bn ARR from 1 December
Yorkville Ives' Dan Ives said Starlink cash flow and the AI backlog give SpaceX capacity to service the debt, with an Outperform rating and $225 target
Morgan Stanley's Adam Jonas called the stock cheap ahead of the Starship 15 launch in late October or November
Bitcoin slides to US$83,000 on forced liquidations
[8:51 am] Bitcoin fell to around US$83,000 as roughly US$696 million in forced liquidations hit leveraged long positions, dragging crypto-exposed stocks lower.
Bitcoin down 2.5% to US$83,463, while Ether fell 4.6% to US$2,573.61
US$696m in liquidations over 24 hours, almost entirely from long positions according to Coinglass
Coinbase, Robinhood and Strategy fell alongside the token
Glassnode flagged unusually low volumes across spot exchanges and US ETFs, with the market leaning on positioning over fresh demand
Levi Strauss lifts profit guidance on tariff refunds but trims sales outlook
[8:50 am] Levi Strauss raised its full-year earnings guidance on the back of tariff refunds but cut its revenue growth forecast to the bottom of its range, leaving shares roughly flat after hours.
Revenue up 4% to $1.61bn vs $1.62bn ests (1% miss)
DTC revenue up 2% with comparable sales flat, while wholesale revenue rose 6%
CEO Michelle Gass said DTC performance "fell short of our expectations," with targeted actions already taken
Operating margin of 13.8% vs 10.8% a year ago, with tariff refunds contributing 4.9 percentage points
Net income down 23% to $168.6m
Adjusted EPS of 48c vs 36c ests (33% beat), including a 16c tariff refund benefit
FY26 adjusted EPS guidance raised to $1.54 to $1.56 from $1.46 to $1.52, with the $1.55 midpoint in line with ests
FY26 revenue growth guidance lowered to 7%, the bottom of its previous 7% to 7.5% range
Source: CNBC
Treasury yields hit 24-year highs as strategists split on the peak
[8:48 am] The 10-year Treasury yield touched its highest level since 2002, with Wall Street strategists divided on whether yields roll over by year end or keep climbing.
10-year yield hit 5.36% intraday, its highest since April 2002, before closing little changed at 5.28%
30-year yield hit 5.73%, its highest since May 2002, before closing at 5.66%
$39bn 10-year auction drew solid demand, helping yields come off session highs
Barclays lifted its forecast for the 10-year yield to 5.25% from 5% for 3Q27 and sees the 30-year reaching 6% if the economy stays resilient
Year-end 10-year forecasts sit at 4.75% for Goldman, 4.8% for Morgan Stanley and Deutsche, 5% for Citi and BofA and 5.05% for JPMorgan
30-year mortgage rate rose 19 basis points to 7.49%, the highest since November 2023
Source: Bloomberg
Oil back above US$100 as Iran steps up Hormuz attacks
[8:46 am] Brent crude nudged back above US$100 a barrel as Iran ramped up attacks on tankers in the Strait of Hormuz and the Houthis escalated strikes on Saudi Arabia.
Brent briefly topped US$102 before settling at $100.88
At least nine attacks in Hormuz so far in October according to UK officials, even as flows through the strait return to near prewar levels
Supertanker rates hit a record $77m to ship US crude to Asia, vs a 2025 average of $9.2m, adding about $38.50 a barrel in delivery costs
Houthis struck two Saudi airports in Riyadh and Abha, killing three, and have announced a blockade on Saudi ports
Saudi-backed counter-offensive has retaken territory near the Bab el-Mandeb strait, including the Red Sea port of Mokha
US blockade of Iranian ports has left Iran barely able to export oil, with no sign yet of restarted peace talks
Tropical Storm Isaias could make landfall on the Gulf Coast as a hurricane by Friday, with Chevron evacuating nonessential offshore staff
Fed minutes flag another rate hike by year end
[8:45 am] All 19 Fed officials backed September's rate hike and most see another increase as likely appropriate by year end, though markets are betting on December rather than this month.
September hike was unanimous, lifting the target range by 25 basis points to 3.75% to 4%, the first increase since July 2023
Most participants assessed another hike would likely be appropriate by year end, with no timing given
Several officials viewed the policy rate as not restrictive or only mildly restrictive, suggesting support for multiple hikes
Financial conditions were seen as supportive of growth despite higher long-term yields, citing strong equity gains and narrow corporate bond spreads
October hike odds sit around 17% to 20%, down from about 70% after the September decision, with futures pointing to a December move
One-year inflation expectations rose to 3.9% in September from 3.6%, the highest since May 2023, ahead of CPI data on 14 October
Wall Street retreats from records as bond yields hit 24-year highs
[8:44 am] US stocks snapped a record-breaking run as oil back near $100 a barrel and multi-decade-high Treasury yields revived inflation and rate hike fears.
S&P 500 down 0.2% to 7,801.77 and the Nasdaq down 0.2%, both falling from record highs, while the Dow fell 0.7%
Russell 2000 down 1.3%, lagging the large-cap benchmarks
Nvidia and AMD slipped less than 1% from all-time highs, with the top three S&P 500 holdings (Nvidia, Apple, Microsoft) now around a fifth of the index
Deere and farm equipment makers fell after the FTC and USDA launched an inquiry into potential anti-competitive conduct
BofA's Savita Subramanian said equities face a genuine rival in bonds for the first time in decades, with elevated sentiment leaving stocks exposed to disappointment
Good morning!
[8:28 am] ASX 200 futures are down 53 pts (-0.60%). Here's what happened overnight:
Wall Street snapped its record run as long-dated Treasury yields touched their highest levels since 2002, with small caps doing the heavy lifting on the downside
S&P 500 (-0.22%), Equal-weight S&P 500 (-0.81%)
Nasdaq (-0.22%), Dow (-0.66%) and Russell 2000 (-1.31%)
Fed minutes kept a year-end hike on the table, though traders still see only slim odds of a move at the late-October meeting
Oil hovered near US$100 a barrel as Iran stepped up attacks on Hormuz shipping, pushing the US dollar toward a fresh 2026 high