ASX 200 Live Today - Tuesday, 13th October
The S&P/ASX 200 is slipping as tech, miners and property retreat, while energy rallies on higher oil. Here are today’s top stories.
Today’s ASX 200 Updates
The live blog has wrapped up for Tuesday, October 13. Thanks for following along, and we’ll be back tomorrow morning. Let us know how we can make it even better.
ASX 200 pares losses as Asian chip rout hits tech and miners
[2:05 pm] The ASX 200 is down 15 points or 0.17%, recovering from session lows of 0.51%. Energy and defensives are outperforming, while tech has given back its two-day rally of about 3% and materials have undercut recent lows to trade at their weakest since 5 August.
The selloff comes against a rough backdrop in Asia:
Kospi fell 7%, briefly triggering a halt to program trading for the first time since August, and is now down a third from its June record
Samsung and SK Hynix each dropped more than 8% after a report that Chinese rival CXMT has made progress on a new memory architecture both companies are also developing
Japan’s Kioxia shed more than 12%, while a gauge of Chinese tech stocks fell as much as 3.6%
Broadcom CEO Hock Tan likened AI investing to a casino and warned financing the buildout may be a bigger problem than chip shortages
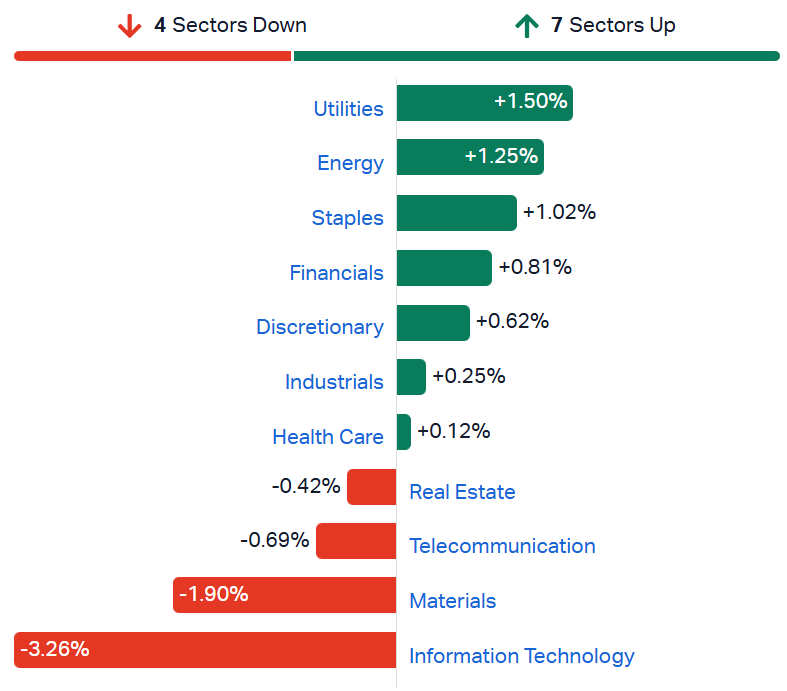
S&P/ASX 200 sectors (Source: Market Index)
Today’s session reinforces a recent trend, with large caps and a handful of select stocks holding up the market. The ASX 20 and ASX 50 are up 0.19% and 0.05% respectively, while the Small Ords and Emerging Companies indices are down 1.22% and 1.67%.
Earlier today, we looked at how solid markets and high yields can co-exist, provided earnings growth holds up. Chinese competition and AI financing concerns are now weighing on sentiment and growth expectations, but luckily for the ASX, there wasn’t much growth priced in to begin with. We’re entering an awkward juncture where the high-flying AI trade is taking a breather, or perhaps rolling over, and dragging bond yields lower with it. Australian yields are down across the curve, with the 3-year down 2 bps to 4.89%, the 10-year down 4bps to 5.30% and the 30-year down 5 bps to 5.76%. The market has been eager to see yields fall, but the catalyst needed to be lower inflation, not slower growth.
Lithium and data centre stocks extend losses as defensives firm
[2:00 pm] Lithium stocks are leading the intraday losers, with Vulcan Energy, Mineral Resources, Elevra, PLS and IGO down between 4.6% and 7% from the open as lithium prices tumble. Data centre names NextDC and Megaport are also sliding amid the global chip selloff, while Zip has shed 6.7% since the open.
Ticker | Company | % Chg | Chg from Open | Price |
|---|---|---|---|---|
VUL | Vulcan Energy Resources | -10.4% | -7.0% | $1.23 |
ZIP | Zip Co | -5.9% | -6.7% | $2.15 |
NXT | Nextdc | -6.5% | -6.3% | $9.49 |
MIN | Mineral Resources | -6.3% | -5.5% | $46.00 |
LYC | Lynas Rare Earths | -3.7% | -5.2% | $11.57 |
MP1 | Megaport | -4.1% | -5.1% | $18.88 |
ELV | Elevra Lithium | -6.6% | -4.9% | $4.26 |
PLS | PLS Group | -7.6% | -4.7% | $3.12 |
IGO | IGO | -5.3% | -4.6% | $5.58 |
DYL | Deep Yellow | -6.1% | -4.6% | $0.88 |
On the flip side, Lovisa leads the intraday gainers, up 4.3% from the open, while Brambles, ARB, AGL and Lottery Corp have each added more than 2% as investors favour defensives and select consumer names.
Ticker | Company | % Chg | Chg from Open | Price |
|---|---|---|---|---|
LOV | Lovisa | 2.4% | 4.3% | $24.43 |
BXB | Brambles | 1.5% | 2.4% | $19.68 |
ARB | ARB Corp | 2.5% | 2.2% | $17.33 |
AGL | AGL Energy | 2.5% | 2.2% | $8.77 |
TLC | Lottery Corp | 1.9% | 2.1% | $5.21 |
REA | REA Group | 1.9% | 2.0% | $157.42 |
BOQ | Bank Of Queensland | 2.5% | 1.8% | $6.66 |
REH | Reece | 2.1% | 1.6% | $17.28 |
WBC | Westpac | 1.1% | 1.5% | $35.01 |
STO | Santos | 1.5% | 1.2% | $8.91 |
UBS says card surcharge ban could add 0.2% to CPI, double RBA estimate
[1:20 pm] UBS believes the RBA is underestimating the inflation hit from the card surcharge ban, though rising fuel prices remain the bigger driver of inflation.
RBA estimates a small, one-off 0.1% lift to CPI, based on $1.6bn in card surcharges against $1.4tn of household consumption
UBS sees a 0.2%+ impact as a more plausible baseline, with merchants potentially using the ban as cover to pass through broader cost pressures
Round-up pricing on items such as coffee suggests pass-through could exceed the surcharge itself, with 17% of cafes lifting prices by an average of about 49c
Fuel prices are tracking 7% higher month-on-month in October, contributing 23bps to monthly CPI
Q4 CPI forecasts of 3.9% headline and 3.5% trimmed mean year-on-year carry upside risk, already above the RBA’s 3.6% and 3.3%
UBS still expects a 25bps hike in November, with a stronger October CPI raising the risk of a December hike if the RBA pauses
Source: UBS
NAB business confidence slumps to bottom 5% of history
[12:42 pm] Business confidence fell for a third straight month as higher interest rates, global uncertainty and elevated fuel costs weigh on firms.
Business confidence fell 4pts to -13, now 18pts below its long-run average and in the bottom 5% of readings in the survey’s history
Business conditions held at -1, 7pts below the long-run average
Employment index fell 3pts to its lowest level in five years, signalling a risk that labour demand slows from here
Capacity utilisation eased 0.2ppts to 82.3% but remains about 1ppt above its long-run average
Purchase cost growth edged up to 2.4% in quarterly terms while final price growth held at 0.8%, further squeezing margins
Forward orders fell 1pt to -1, around 7pts below pre-conflict levels, even as capex rose above its long-run average
Source: NAB
Kospi tumbles 6% as global chip selloff deepens
[1238 pm] South Korea’s chip-heavy market sank as concerns over Chinese competition and stretched AI valuations intensified.
Kospi fell as much as 6.2% and is now down a third from its June record, trading below its 200-day moving average
Samsung and SK Hynix each fell more than 7%, on track for a fifth straight loss, with Samsung’s record earnings last week failing to lift the stock
CXMT plans a higher-density server memory product by the end of 2026, reviving fears about Chinese competition
Foreign investors have net sold more than US$6bn of Kospi shares in October
Broadcom CEO Hock Tan said many AI investors “have no clue what they are investing in”, adding financing may be a bigger problem than chip shortages
Source: Bloomberg
ASX 200 slips as tech, miners and property retreat
[12:17 pm] The ASX 200 is down 30 points or 0.35%, with weakness across tech, miners and real estate. It’s not a great look for tech, which has failed to follow through on a two-day rally despite US software stocks returning to year-to-date highs. Miners have undercut their recent low to sit at a two-month low, while real estate stocks have handed back half of last week’s 4% four-day rally, which came after the sector bounced off its lowest level since January 2024. The session has a defensive tilt, with energy and utilities broadly higher on rising oil prices, and staples and financials also outperforming.
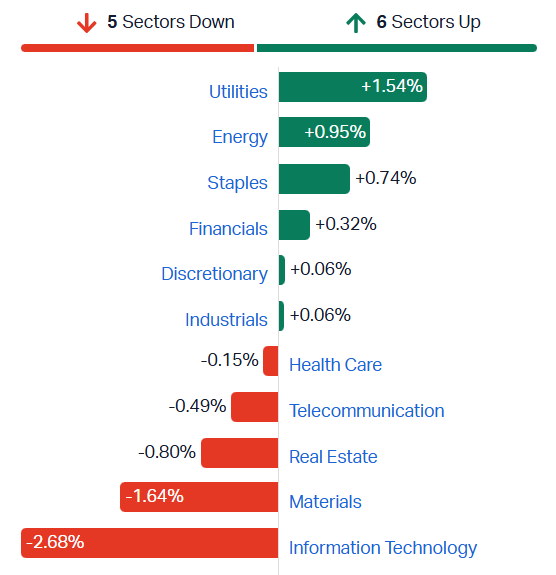
S&P/ASX 200 sectors (Source: Market Index)
XRF Scientific jumps 16% on strong September quarter
[12:12 pm] XRF Scientific shares opened 5.1% higher at $1.74 and have since extended gains to 15.7% at $1.91, though the stock remains 5% lower year-to-date.
Revenue up 38% to $21.1m, or up 25% excluding a one-off $2.05m precious metals sale
Consumables revenue up 27% to $5.6m, with conditions remaining positive into October
Capital equipment revenue up 18% to $5.9m, with Orbis up 66% to $2.4m on demand from commercial labs and the gold sector
Precious metals revenue up 63% to $9.6m, including the one-off sale tied to the closure of a platinum inventory lease
Profit before tax up 30% to $4.4m, including unadjusted CGA integration costs
December quarter is expected to be another strong period, with new CGA instrument revenue and significant growth from Orbis
Company page: XRF Scientific (XRF)
BlackRock downgrades US stocks, turns bullish on short-term Treasuries
[12:11 pm] BlackRock has unwound an underweight call on Treasuries first made in October 2020, when the US 10-year yield was near 0.9%, after it surged above 5.2%.
Short-term Treasuries upgraded to overweight and longer-term debt to neutral from underweight
US equities downgraded to neutral from overweight on potential volatility around the AI buildout, with US agency mortgage-backed securities also cut to neutral
Fed hike expectations look excessive to BlackRock, with swaps pricing at least three quarter-point hikes over the next 12 months
Bond yields could rise another 75bps over 12 months before Treasury total returns turn negative
AI conviction remains intact, with BlackRock still favouring AI-related companies and listed infrastructure and ready to add risk at better entry points
Source: Bloomberg
RBA minutes point to greater domestic capacity pressures
[11:50 am] The full minutes show the RBA increasingly sees inflation being driven by an overheating domestic economy, not just higher oil prices.
Unanimous decision to lift the cash rate 25bps to 4.60%, with the board ready to increase it further if required
July’s inflation surprise more likely reflected domestic capacity pressures than pass-through from the Middle East conflict, staff assessed
Staff are questioning whether the unemployment rate consistent with the inflation target is higher than thought, with the jobless rate at 4.6% in August
Market pricing at the meeting implied another 15bps of hikes by year-end and a further 30bps in the first half of 2027
Australian equities fell about 5% between meetings on weaker earnings expectations for banks, real estate and consumer discretionary
AI valuations were flagged as a global financial stability risk, with some pricing embedding very favourable long-run earnings assumptions
Source: RBA
NSW backs gas over batteries in latest firming tender
[11:48 am] New South Wales has effectively shut batteries out of its latest tender for backup power as it prepares for its ageing coal plants to close.
Tender for 1,500MW of firming capacity, most of which is expected to come from gas peaking plants
Bidders must be net energy contributors and able to supply for at least eight hours, ruling out most storage systems
Gas lost out in the state’s previous backup tenders, mainly to battery storage
Origin delayed the closure of Eraring, Australia’s largest coal-fired power station, by almost two years to 2029 after the grid operator flagged reliability risks
NSW Energy Minister Penny Sharpe said “We’re building the airplane as it’s flying, and we can’t afford to have loss of reliability”
Source: Bloomberg
Lithium stocks smashed as spodumene sinks 12%
[11:08 am] Lithium prices tumbled across the board after the EU moved to cap Chinese hybrid imports, dragging ASX lithium stocks sharply lower.
Spodumene 6% (FOB Australia) fell 12.4% to US$1,485 a tonne, down 31.4% over three months
Lithium carbonate and hydroxide in China both fell 8.3%, to US$16,433 and US$14,790 a tonne respectively
Wuxi lithium carbonate index dropped 12.8% and Guangzhou futures 10.5%, both down more than 30% over three months
EU cap limits Chinese hybrid imports to 350,000 a year from as early as 1 December, roughly 45% below this year’s run rate
Goldman expects lithium markets to shift from deficit to near-balance in Q4, then into surplus over the next two years
Ticker | Company | % Chg | Price | 1 Week | YTD |
|---|---|---|---|---|---|
VUL | Vulcan Energy Resources | -8.0% | $1.26 | -25.2% | -71.4% |
PLS | PLS Group | -5.2% | $3.20 | -15.9% | -23.9% |
IGO | IGO | -3.4% | $5.69 | -11.6% | -30.5% |
MIN | Mineral Resources | -3.0% | $47.60 | -6.4% | -12.5% |
PMT | PMET Resources | -2.6% | $0.37 | -14.0% | -37.8% |
EUR | European Lithium | -2.0% | $0.36 | -11.6% | 133.9% |
LTR | Liontown | -1.3% | $0.74 | -9.8% | -52.9% |
GL1 | Global Lithium Resources | -0.5% | $1.00 | -0.5% | 57.9% |
CXO | Core Lithium | 0.0% | $0.23 | -23.3% | -16.4% |
INR | Ioneer | 2.4% | $0.11 | -2.3% | -41.9% |
DLI | Delta Lithium | 3.0% | $0.17 | 1.8% | -22.7% |
Top ASX 200 gainers
[10:41 am] Electro Optic Systems tops the leaderboard after a volatile few sessions. The company announced its largest contract on record, a £370m (about $700m) deal to supply a nationwide counter-drone defence system to the Kuwaiti government. Shares surged as much as 22% on the day (9-Oct) before reversing to close 4.2% lower, then fell another 4% the following session. Elsewhere, energy stocks are catching a bid, while Arena REIT extended its rebound after Edge Early Learning’s administrator found buyers for the last seven Edge-operated centres on Arena’s properties, meaning all 27 now have proposed replacement operators.
Ticker | Company | % Chg | Price | 1 Week | YTD |
|---|---|---|---|---|---|
EOS | Electro Optic Systems | 4.9% | $10.21 | -14.8% | 8.2% |
ARF | Arena Reit | 4.0% | $2.46 | 22.1% | -31.0% |
GDG | Generation Development Group | 2.6% | $2.79 | 4.9% | -52.6% |
ORG | Origin Energy | 2.5% | $11.53 | 5.9% | 0.2% |
STO | Santos | 2.5% | $8.99 | 4.9% | 45.5% |
MI6 | Minerals 260 | 2.1% | $0.85 | -0.3% | 101.8% |
BOQ | Bank Of Queensland | 2.1% | $6.64 | 2.9% | 1.1% |
RMD | Resmed | 1.9% | $33.57 | 5.6% | -7.0% |
BPT | Beach Energy | 1.8% | $0.87 | 3.6% | -26.1% |
WDS | Woodside Energy Group | 1.7% | $32.72 | 5.2% | 37.9% |
Top ASX 200 losers
[10:41 am] Software stocks experience a pullback after a sizeable two-day rally, while lithium and uranium stocks continue to spiral lower.
Ticker | Company | % Chg | Price | 1 Week | YTD |
|---|---|---|---|---|---|
IPX | Iperionx | -6.9% | $2.17 | -10.7% | -60.6% |
VUL | Vulcan Energy Resources | -5.8% | $1.29 | -23.4% | -70.7% |
SLX | Silex Systems | -5.1% | $3.84 | -10.8% | -54.5% |
PLS | Pls Group | -3.7% | $3.25 | -14.6% | -22.7% |
PNR | Pantoro Gold | -3.7% | $2.90 | -0.3% | -40.8% |
ZIP | Zip Co | -3.5% | $2.20 | 4.8% | -32.7% |
DYL | Deep Yellow | -3.5% | $0.91 | -18.6% | -50.7% |
WTC | Wisetech Global | -3.4% | $32.92 | -0.5% | -51.9% |
S32 | South32 | -3.3% | $4.85 | -2.9% | 36.5% |
TNE | Technology One | -3.2% | $30.12 | -2.5% | 9.3% |
Raiz plunges 48% on historical tax compliance failures
[10:13 am] Raiz Invest shares plunged 48% to 26 cents, taking year-to-date losses to 66%, after the company flagged potentially material tax liabilities dating back to 2015.
Tax withholding was not applied and related reports were not lodged with the ATO for certain Raiz funds since 2015, identified in a review by new CEO Craig Keary
Potential liabilities include penalties, general interest charges and remediation costs, with the Board flagging a possible material impact it cannot yet estimate
Independent review by WTS Australia is continuing and may identify further matters, with the number of affected account holders not yet quantified
Customer funds remain secure with independent custodians, with ASIC and the ATO notified and super fund members unaffected
FY26 underlying EBITDA of $5.5m and free cash flow of $2.7m, with cash of $15.4m at 30 June
Company page: Raiz Invest (RZI)
EDU Holdings enrolments hit record as domestic intake offsets visa curbs
[9:55 am] EDU Holdings’ shift towards domestic and postgraduate students is cushioning the hit from tighter international student rules.
Group enrolments up 26% to a record 7,489 in T3'26, with Higher Education now 88% of the total from 75%
Higher Education enrolments up 45% to a record 6,571
Higher Education new student enrolments flat at 1,074, as a 78% jump in domestic commencements offset a 10% fall in international
Domestic students made up 20% of Ikon’s T3'26 intake from 11%, while postgraduate students rose to 28% of Higher Education enrolments from 14%
VET enrolments down 36% to 918 in T4'26 amid an ongoing contraction in the international VET market
Student visa reforms from 2 October require most applicants to apply offshore and double the restricted transfer period to 12 months, which may reduce onshore transfers
EDU is a rather intriguing small cap. The stock is up 33% YTD (and a 10-bagger since 2025). Earnings have surged, with the latest 1H26 result showed NPAT up 49% to $9.3m, with $24m in cash and no debt, and the interim dividend tripled to 3cps from 1cps a year earlier.
Company page: EDU Holdings (EDU)
Baby Bunting reaffirms FY27 guidance as comp sales slow
[9:52 am] Baby Bunting held its FY27 profit guidance at its AGM, though early trading is running below its full-year sales growth target as stores close for refurbishment.
FY27 pro forma NPAT guidance of $19-21m maintained, on total sales of $585m to $600m
Comparable store sales up 2.2% in the first 14 weeks vs the full-year target of 3% to 5%, having moderated from 4.3% at week 6
Store of the Future refurbishments are delivering an average 20% sales uplift, with 10 to 12 planned in FY27 and six in the first half
Gross margin is tracking to plan for the 42% FY27 target, up from 41.2% in FY26
Long-term EBITDA margin target of more than 10% vs 6.8% in FY26
Management is closely monitoring trading given interest rate rises and cost-of-living pressures ahead of November, Boxing Day and the June Storktake
Company page: Baby Bunting (BBN)
GQG outflows ease in September, Macquarie stays Neutral
[9:48 am] GQG Partners’ September outflows were the smallest in four months, though Macquarie remains cautious on longer-term flows given persistent fund underperformance.
Net outflows of US$2.3bn vs US$2.4bn ests (4% beat), improving from US$4.3bn in August and US$4.5bn in July
Emerging Markets led outflows at US$1.0bn, equal to 35% of FUM annualised
FUM of US$149.2bn vs US$148.0bn ests (1% beat), flat on August
Relative fund performance remains weak, with Emerging Markets trailing its benchmark by 16.3% over one year and 11.7% over three years
EPS ests lifted 0.3% for FY26 and 1.2% for FY27, with flow assumptions unchanged at average monthly outflows of US$3.7bn
Target unchanged at $1.10 with Neutral retained, with the implied 11% TSR including a 14.5% unfranked yield
Source: Macquarie
Arena REIT now has buyers lined up for all 27 Edge centres
[9:44 am] All 27 Arena-owned centres operated by collapsed childcare provider Edge Early Learning now have proposed replacement operators, removing much of the vacancy risk that hammered the stock.
Final seven centres are among 22 Edge businesses being sold to six parties, including Montessori Academy at two SA centres, after Goodstart agreed to take over 20 Arena centres on 7 October
Rent is being received on all 27 centres while the sales progress, though all deals remain subject to due diligence, regulatory approvals and lease assignments
Of the four centres Arena controls directly, one has an executed lease and two have term sheets with Montessori Academy
Bank guarantee and security deposits of about $4m are held over the Edge leases
Shares fell 31% over 10-11 August when Edge’s troubles emerged and were down as much as 39.5% by 5 October, before rallying 13% on the Goodstart deal, leaving them 28% below pre-news levels
Company page: Arena REIT (ARF)
Macquarie lifts Southern Cross Electrical target on Entire acquisition
[9:34 am] Macquarie views Southern Cross Electrical’s $112 million purchase of Entire Operations as a strategically sensible deal close to its core business that should be margin accretive over time.
Purchase price of $112m equals 6.4x EV/EBIT, or 4.0x on the $70m upfront component, vs Southern Cross trading at 12.8x FY27e EV/EBIT
Entire delivered FY26 EBIT of $17.5m on revenue of $191m, a 9.2% margin
Deferred consideration of $41m includes $26m if Entire delivers at least $17m EBIT across FY27-29, with the balance tied to targets implying 16% EBIT CAGR
FY27 underlying EBITDA guidance lifted to at least $110m vs $119m ests
EPS ests lifted 10% for FY27 and 13-14% for FY28-31, with a 3-year EPS CAGR of more than 35%
Target lifted 7% to $6.00 from $5.60 with Outperform retained, with the stock on 15.8x FY28e PE vs domestic peers on 18.5x
We noted the napkin maths in the blog yesterday: "SCEE’s deal looks very accretive at first glance, with up to $112.1m paid from cash (under 8% of its $1.43bn market cap) delivering at least 18% EPS accretion from FY27. Wouldn't be surprising to see a strong market reaction this morning". The stock opened the session 3.6% higher ($4.80) and finished up 7.7% to $4.99.
Company page: Southern Cross Electrical Engineering (SXE)
Copper hits two-week high as Codelco avalanche adds to Chile supply woes
[9:24 am] Copper rallied on hopes that higher bond yields will limit further central bank rate hikes, while fresh disruptions in Chile added to supply concerns.
Copper advanced 0.8% overnight to US$6.81/lb, within 2% of the 22-Sep record close of US$6.92/lb
Cash copper premium over three-month prices reached $170 a tonne, the highest since early September and a sign of tight near-term supply
Two workers died in an avalanche at Codelco’s El Teniente mine, with the open pit halted, though it accounts for less than 10% of the mine’s output
Chilean labour tensions are adding to supply risks, with a strike at Antofagasta’s Centinela and a wage dispute at BHP’s Escondida
China’s import demand gauge hit a four-year high last week, while inventories remain low after the national holiday
Copper may be trading near record highs, but miners aren’t buying it. The Global X Copper Miners ETF rose just 0.4% overnight and remains 13% below its 27 August record close, showing a clear reluctance to underwrite the recent rally in the metal. The reason isn’t clear, it could be macro headwinds (soaring US dollar, elevated yields, Brent at US$105), scepticism that the price strength won't last given the threat of US tariffs on refined copper, or simply a lack of risk appetite.
Wia drilling extends Kokoseb underground target by 470m
[9:22 am] Wia Gold’s latest results are building the case for an underground operation beneath the planned open pit at its 3.78Moz Kokoseb gold project in Namibia.
Central Underground Exploration Target extended by about 470m, including 170m to the northeast and 300m of confirmed continuity to the southwest
Underground Resource Envelope drilling returned a best hit of 15.5m at 6.53g/t gold from 499.5m, including 3m at 27.93g/t
Intermediate and Deep High-Grade target returned 29m at 1.91g/t from 755m and 6m at 6.06g/t from 623m
Southern Underground Exploration Target continues down-plunge and remains open at depth, with 18m at 2.78g/t from 606m
Six diamond rigs are still turning, with results reported from 33 holes for 18,476m
Company page: Wia Gold (WIA)
Minerals 260 grade control drilling backs Bullabulling resource
[9:21 am] Initial grade control results at Minerals 260’s 6.2Moz Bullabulling gold project near Coolgardie are tracking in line with resource modelling.
Grade control results at the 2.3Moz Phoenix deposit are consistent with the resource model, supporting an upgrade of Inferred material to Indicated
Bacchus returned 1.1m at 290g/t gold from 170m
Shallow Phoenix hits include 7m at 10.9g/t from 7m and 6m at 17.1g/t from 19m
Widest grade control hit of 21m at 3.4g/t from 27m, including 1m at 52.6g/t
Latest results cover 53 infill and extensional holes for 11,674m and 320 grade control holes for 25,970m
Company page: Minerals 260 (MI6)
Cobre maps staged path to 25,000tpa copper at Sierra Atacama
[9:14 am] Cobre has outlined a fully funded, modular expansion of Sierra Atacama that leans heavily on refurbishing existing processing infrastructure.
Stage 1 targets about 18,000tpa of copper cathode by refurbishing the existing SX circuit and recommissioning the idle second electrowinning bay, with tender award expected by quarter end
Stage 2 targets about 25,000tpa by recommissioning the unused second SX line and building a new electrowinning bay, with conceptual engineering underway
Stage 3 will evaluate a larger case of up to about 50,000tpa once the 40,000m drilling program, updated resource and expanded open-pit design are complete
Environmental approval for the 25,000tpa case, covering grid power, water supply and additional open-pit areas, is targeted for submission by the end of 2026
No capex or production timeline has been disclosed for any stage
Company page: Cobre (CBE)
Vection lands $19.5m Italian supply deal
[9:13 am] The minimum commitment equals close to half of Vection’s roughly $40 million market cap, though it is spread out to mid-2030, so not as punchy as the headline suggests.
Retelit Digital Service has committed to at least $19.5m in cumulative revenue on Vection’s Algho AI, Renderia and 3DFrame platforms and its kiosk and appliance hardware
Revenue milestones of $5m by 31 December 2027, a further $6.5m by 30 June 2029 and a further $8m by 30 June 2030
Agreement runs to 30 June 2030 with no automatic renewal
RDS has been appointed a Tier 1 partner under Vection’s global partner program, authorised to sell across Italy and Europe through its dealer network
Company page: Vection Technologies (VR1)
Wildcat’s September quarter: $76m cash ahead of DFS and maiden resource
[9:11 am] Wildcat Resources is approaching a catalyst-heavy end to 2026, with its Tabba Tabba definitive feasibility study and a maiden Bolt Cutter Central resource both due this half.
Cash of $76.1m at 30 September vs a market cap of about $390m, after Tranche 1 of a $60m placement raised $56m before costs
Tabba Tabba DFS is on track for completion in CY2026, with placement funds going towards development and early works
Pegmatite rights over E45/2364 add about 7km of the Tabba Tabba Shear, tripling the explorable strike length
Tabba Tabba drilling returned 13.9m at 2.0% Li2O from 45.2m and 25.1m at 1.2% Li2O from 56.5m
Bolt Cutter Central has a mineralised footprint of about 2.3km by 0.8km that remains open, with hits including 16m at 1.5% Li₂O from 116m
Company page: Wildcat Resources (WC8)
Chinese lithium futures slump on EU hybrid cap
[8:58 am] Chinese lithium futures sank after the EU moved to cap Chinese hybrid imports, adding to concerns about softening battery demand.
Chinese lithium carbonate futures fell 8.4% to 108,760 yuan a tonne, now down 48% from the mid-May high of 209,880 yuan a tonne
EU cap limits Chinese hybrid imports to 350,000 a year from as early as 1 December, roughly 45% below this year’s run rate of 650,000
Quota rises 6% a year to about 417,000 by year four, around eight times the annualised import level of October 2024
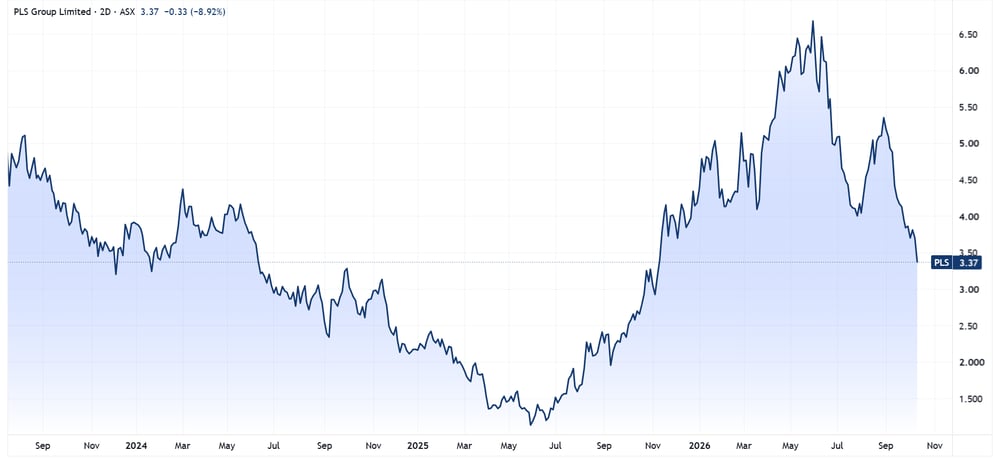
The bellwether PLS Group ran almost 500% from its 30 May 2025 low of $1.13 to a record high of $6.68 by 29 May 2026. The stock has since halved to $3.37 and down 19% year-to-date.
PLS Group price chart (Source: TradingView)
Strong earnings can outrun rising yields, Goldman data shows
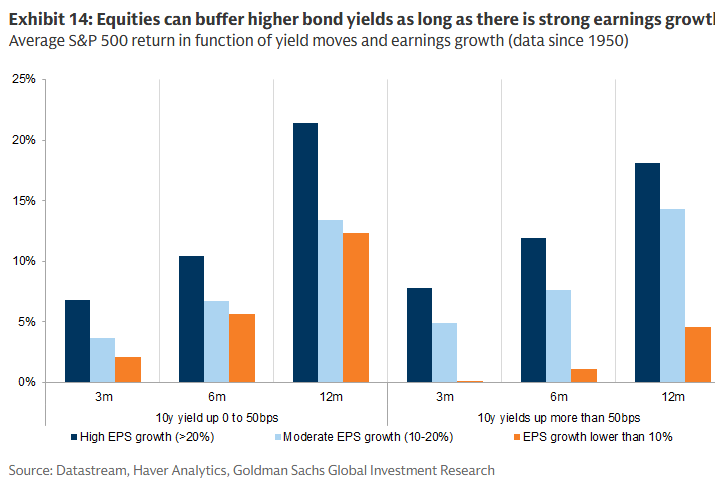
[8:50 am] Goldman’s data since 1950 shows that even when 10-year yields rise more than 50bps, the S&P 500 has averaged a 12-month return of about 18% when earnings growth tops 20%, compared with under 5% when earnings growth is below 10%.
So really, solid markets and rising yields can co-exist, as long as earnings growth/momentum remains strong (and probably why the ASX is going nowhere).
Goldman lifts Brent forecast to US$90 as risks skew higher
[8:49 am] Goldman Sachs still expects Gulf supply to adapt and pull crude prices lower over time, but ongoing supply risks are slowing the easing in the risk premium.
Brent Dec26 forecast raised to US$90 a barrel from US$85, with the risk premium estimated at just over US$20, while the 2027 average of US$80 is unchanged
Persian Gulf exports, including dark exports, have recovered to their 2025 average, with the global market roughly balanced in September
Restocking demand from low inventories outside OECD commercial storage lifts Goldman’s September Brent fair value by US$6 to US$80
Upside scenario sees Brent averaging around US$125 in 2027 if Gulf output stays 5mb/d below Feb26 levels
Downside scenario sees Brent falling into the US$60s in 2027 if Gulf output rises 1mb/d above Feb26 levels
Brent nears US$106 as Houthi strikes on Saudi Arabia escalate
[8:44 am] Oil climbed to its highest in almost a month as attacks on Saudi Arabia and Gulf shipping outweighed the prospect of extra Russian supply.
Brent up 1.5% to US$105.89 a barrel
Houthi strike on Riyadh’s main airport killed 12 and injured more than 300, with further drone and missile attacks on Saudi Arabia on Sunday and Monday
Trump is considering joining Saudi retaliation against the Houthis in Yemen
At least 10 VLCCs and several Suezmax tankers heading to Fujairah stopped or reversed course, threatening the transfer workaround that restored Gulf exports to near prewar levels
Saudi Arabia plans to lift pipeline capacity bypassing Hormuz by 40% to 10m barrels a day within two to three years
Zelenskyy said Russia violated Trump’s energy ceasefire by attacking a Ukrainian gas facility
UK PM Burnham said Iran’s IRGC “almost certainly” directed the alleged terror plot at RAF Fairford, with two Iranian nationals sanctioned
India inflation hits near two-year high, backing RBI hikes
[8:42 am] India’s inflation is closing in on the top of the RBI’s 2% to 6% target band, reinforcing last week’s first rate hike in almost four years.
CPI rose 5.54% year-on-year in September vs 5.58% ests (in line), up from 4.83% in August and the highest since late 2024
Food inflation climbed to 7.74% from 5.97%, with deficient rainfall expected to add pressure
RBI hiked 25bps to 5.50% last week and expects inflation to average 6% in the December quarter, with Elara Securities tipping two more hikes by end-March
India 10-year yield rose about 10bps to 7.40%
Amundi sees a rebound in Indian equities once the Iran war ends, after the Nifty 50 fell nearly 14% this year on more than US$30bn of foreign outflows
Source: Bloomberg
Microsoft to deploy over a million in-house AI chips next year
[8:41 am] Microsoft unveiled its third-generation Maia 300 AI chip as it looks to power its AI software with mostly homegrown hardware.
Deployment of potentially more than a million Maia 300 chips is planned next year, in “multi-gigawatt deployments”
Efficiency claim of about 40% more useful computing per megawatt than leading GPU-based systems, though Microsoft did not name the comparison
Each rack holds 96 chips using about 167 kilowatts, vs 142 kilowatts for Nvidia’s 72-GPU GB300 racks
Chiplet design uses TSMC 2-nanometre technology for key compute and cheaper 3-nanometre for data movement
Capex is expected to top US$175bn this calendar year
Source: Bloomberg
Micron, SK Hynix slide as China’s CXMT flags memory breakthrough
[8:40 am] Memory chip stocks fell after Chinese rival ChangXin Memory Technologies reported progress on a new cell design also being pursued by the industry’s biggest players.
Micron fell 3.9%, SK Hynix’s US listing dropped 4% and Sandisk slid 6%, while Samsung fell 4% as the Kospi dropped 3.65%
CXMT plans to launch a new server memory product built on the architecture by the end of 2026
Micron is down about 16% from its June all-time high
Firmus IPO collapse raises bar for Asian AI infrastructure deals
[8:39 am] The pulled float of Nvidia-backed Australian data centre operator Firmus Grid is forcing investors to separate AI infrastructure names with earnings from those still building.
Firmus withdrew a raise of up to US$5.5bn after investors baulked at a US$30bn valuation, and is now exploring a private round with existing investors
Only 46MW of its 912MW pipeline has been built
Asia-Pacific equity raisings have hit nearly US$250bn this year, after about US$260bn in 2025
Recent debuts are struggling, with Luxshare down 20% and Zhongji Innolight down 7% since July, and Z.AI and MiniMax down more than 70% from record highs
Future IPOs will need stronger contracted offtake, clearer visibility on energised megawatts and more conservative leverage, says NYU’s Winston Ma
Source: Bloomberg
US bank stocks slump into correction ahead of earnings
[8:38 am] US bank shares have tumbled despite 10-year yields above 5%, upending the view that the sector benefits from higher rates.
Over the past month JPMorgan is down 6%, Citi 6.5%, Wells Fargo 7%, Morgan Stanley 11%, Goldman Sachs 12% and Bank of America 13%
KBW Nasdaq Bank Index is more than 14% below its August peak
Deal pipeline concerns are weighing, with OpenAI’s IPO pushed to 2027 and Oura’s listing delayed, according to Evercore ISI
AI disruption fears include deposit competition from AI cash-yield tools and new agentic trading features at Robinhood and Coinbase
In a nutshell: Wall Street flat as chipmakers slide
[8:37 am] US stocks drifted on the slowest trading day of 2026 as investors held fire ahead of the earnings season and Wednesday’s CPI print.
S&P 500 down 0.06% to 7,807 and the Nasdaq fell 0.44%, while the Dow rose 0.38% as chipmakers posted their longest losing streak since July
Earnings season kicks off Tuesday with JPMorgan, Goldman Sachs, Citi and Wells Fargo, with S&P 500 Q3 earnings ests between 25% and 30% growth year-on-year
Goldman Sachs upgraded global stocks to overweight from neutral on a three-month view, citing a valuation de-rating and healthy profit outlook
Cleveland Fed’s Hammack said a restrictive stance is appropriate and favoured smaller, quicker adjustments, but stopped short of backing an October hike
Energy sector ETF hit a record high on rising oil, while Salesforce rose 2% after a Bank of America double upgrade to buy with a target of US$285 from US$160
Good morning!
[8:28 am] ASX 200 futures are up 9 pts (+0.10%). Here's what happened overnight:
Wall Street finished mixed and fairly flattish as renewed chipmaker weakness drove a rotation into defensives and value
S&P 500 (-0.06%), Equal-weight S&P 500 (+0.07%)
Nasdaq (-0.44%), Dow (+0.38%), Russell 2000 (-0.45%)
China's memory breakthrough hit Micron, SK Hynix and Samsung, adding to the AI hardware wobble
US Dollar Index climbed 0.3% to 102.58, the highest since April 2025, while US Treasury market was shut for Columbus day
Brent pushed above US$105 as Houthi attacks on Saudi Arabia outweighed Trump's Russia-Ukraine energy ceasefire