ASX 200 Live Today - Tuesday, 3rd November
The ASX 200 is trading higher after the RBA hiked rates by 25 bps for a fifth time this year. Here are today's top stories.
Today’s ASX 200 Updates
Welcome to our live ASX coverage for Tuesday, November 3. Expect a high volume of posts pre-market and more periodic updates throughout the day. We'll be wrapping the blog up around 2:30 pm AEDT, after the RBA decision. Let us know how we can make it even better.
ASX 200 rallies as bond yields fall despite RBA hike
[2:50 pm] That’s a wrap! The ASX 200 is up 24 points (+0.28%) after a sharp uptick in the wake of the RBA’s hawkish hike, with the Board noting: “The Board is conscious of the period in which inflation has been too high. Given the revised inflation outlook and the continuing upside risks, the Board judged that a further tightening in financial conditions is warranted to support the return of inflation to target.”
Despite the hawkish tone, the policy-sensitive 3-year yield has tanked 8 bps (and is still falling) since the decision. The market may be zeroing in on the more dovish takeaways, with the RBA acknowledging the “economy is slowing, housing prices have fallen significantly and the unemployment rate has risen”. It still expects employment to keep growing, but “the unemployment rate is projected to rise by more than expected in the August forecasts”.
On the sector front, the market is holding a relatively defensive posture, with yield-sensitive and consumer-facing sectors like Real Estate, Staples and Discretionary leading the way. Energy is getting hit after oil’s ~8% fall overnight, while Healthcare is on the back foot after a weak lead from Wall Street, where the S&P 500 biotech sector fell 2.5%. Materials are higher even as commodities give back their tentative overnight bounce, with copper down 1.4% to US$6.51/lb, iron ore futures down 0.5% to US$90.80/t and gold down 0.4% to US$3,927/oz.
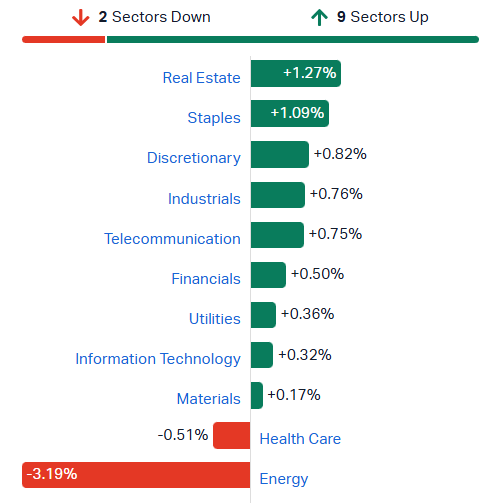
S&P/ASX 200 sectors (Source: Market Index)
ASX 200 off lows, 3-year yield tumbles
[2:38 pm] The ASX 200 bounced off session lows of -0.15%, now trading around breakeven, while the Aussie 3-year yield is down 5 bps despite the RBA's hawkish hike. The Australian dollar is also trading sharply lower, while the 10-year is relatively unchanged.
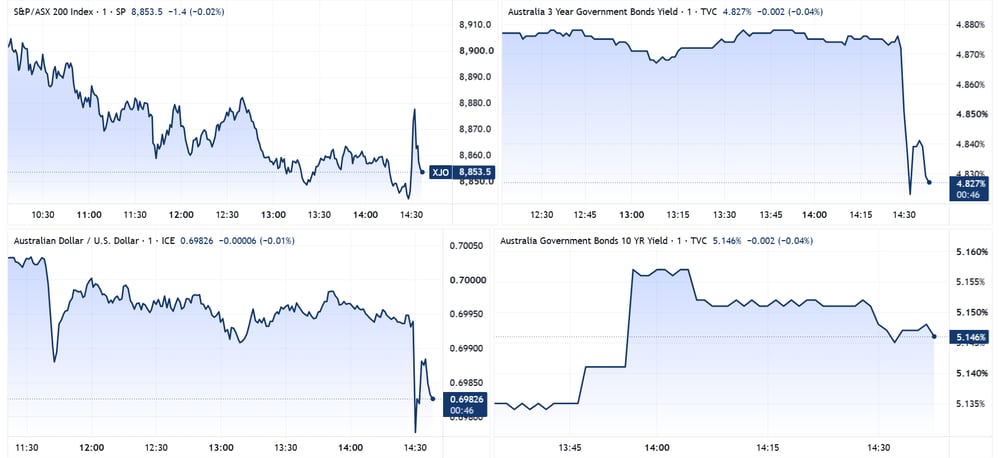
S&P/ASX 200 (top left), Australian 3-year yield (top right), Australian/US dollar (bottom left) and Australian 10-year yield (bottom right) | Source: TradingView
RBA hikes to 4.85% in split vote as inflation outlook worsens
[2:30 pm] The RBA has lifted the cash rate again, warning inflation won’t return to the top of its target band until late 2027 and that higher inflation expectations risk becoming embedded.
The cash rate was raised 25bps to 4.85%, with six board members voting for the hike and three preferring to hold at 4.60%
Inflation is now forecast to stay above 3% over the coming year and not reach the top of the 2–3% band until late 2027, around three quarters later than previously expected
Higher fuel and commodity prices from the Middle East conflict are being passed through to other goods and services, while AI-related investment is driving rapid price growth for technology goods
Capacity pressures are a little tighter than previously estimated, with liaison showing many firms are lifting or looking to lift prices in response to rising costs
The economy is slowing, with house prices down significantly and unemployment now projected to rise by more than in the August forecasts, though data centre investment is set to support near-term business investment
The board gave no explicit guidance on further moves, saying it will do what it considers necessary to bring inflation sustainably back to target
Source: RBA
Morgan Stanley backs Santos and Karoon as energy earnings run well ahead of consensus
[1:54 pm] Here’s an interesting Morgan Stanley note from Monday, where the analysts highlight the key debate for ASX energy producers is how long the current supply disruption lasts, with forward curves pricing oil higher for longer.
Santos and Karoon Energy are its preferred picks among ASX oil and gas producers, with Beach Energy and Origin Energy least preferred
Morgan Stanley’s 2027 producer EPS estimates sit about 35% above consensus, a gap it attributes to using the forward curve for its price deck
Share prices imply undemanding oil prices of US$60–70/bbl across its covered producers
Active managers remain about 10bps underweight ASX Energy, a further 3bps reduction on the prior month
The ASX 200 Energy sector is up 30% YTD, lagging MSCI Europe Energy (up 49%) and S&P 500 Energy (up 51%)
Woodside’s Capital Markets Day on 5 November is expected to unveil a revamped capital allocation framework
Pimco CEO warns AI financing is heading towards ‘too much’
[1:53 pm] Pimco CEO Emmanuel Roman says AI-related financing could swell to about US$10 trillion over the next five years, eventually reaching excessive levels.
Roman estimates about US$2tn a year of financing could be needed over the next five years to fund AI capex, compared with a US bond market of about US$12tn
“At some point in time, there’s going to be a downturn, and then things are going to break,” Roman said at a Hong Kong investment summit
Potential triggers range from rising US interest rates and war in the Middle East to a eurozone crisis, according to Roman
Roman said the bigger mistake in portfolio construction today would be taking on too much risk rather than being too cautious
Blackstone President Jon Gray was more bullish, saying some scepticism is healthy but “underestimating the productivity gains that are coming and the change in consumer and businesses, that’s a mistake”
Source: Bloomberg
ASX earnings expectations slump at fastest pace since COVID as consumer stalls
[1:08 pm] UBS says the latest round of AGM trading updates confirms the Australian consumer is slowing sharply, with retailer sales now flat and volumes going backwards.
Retailer sales growth is tracking roughly flat vs pcp over the seven weeks since early September, down from 2.2% in August updates and 3.5% in February, implying falling volumes with inflation still above 4%
FY27 ASX 200 EPS growth expectations have fallen to just under 7% from almost 13% four months ago, the sharpest deceleration over a similar period since March 2020
Excluding resources, FY27 EPS growth now sits at 5.3%, down from 8.2% four months ago, with Consumer Discretionary and Real Estate copping the heaviest downgrades since June while higher oil prices drove Energy upgrades
Banks have been the standout performers through the AGM season, which UBS puts down to rotation out of AI trades and high-AI-beta Asian markets rather than any stellar profit updates
Real Estate has also outperformed as investors look through to a possible valuation trough, while Consumer Discretionary and Staples lagged on soft trading updates and Miners suffered as commodity price momentum faded
UBS economics still expects a 25bp RBA rate hike, very likely in November, with the risk of another in February, and sees dwelling prices falling a cumulative 10% as tighter policy starts to bite
Tech stocks catch a bid near seven month lows
[1:06 pm] The S&P/ASX 200 Tech Index is currently up 1.0% as it continues to trade near seven-month lows. The index is on track to snap a three-day losing streak where its given back 3.2%. Fund administrator, battered data centre plays and a few 'old guard' names like Wisetech, Life360 and Xero are all trading broadly higher.
Ticker | Company | % Chg | Price | 1 Week | YTD |
|---|---|---|---|---|---|
PPS | Praemium | 5.4% | $0.59 | 7.3% | -25.8% |
NXT | NextDC | 5.3% | $6.27 | 11.5% | -49.1% |
DGT | Digico Infrastructure REIT | 4.0% | $2.36 | 15.1% | -15.4% |
WTC | Wisetech Global | 3.7% | $42.00 | 3.8% | -38.7% |
ZIP | Zip Co | 3.6% | $1.88 | 16.0% | -42.5% |
NXL | Nuix | 3.4% | $1.84 | -0.3% | 1.4% |
IRE | Iress | 2.7% | $5.69 | -0.7% | -32.1% |
OCL | Objective Corporation | 2.1% | $6.38 | -2.7% | -61.5% |
DDR | Dicker Data | 2.0% | $14.79 | -1.3% | 43.7% |
360 | Life360 | 1.9% | $21.38 | 1.0% | -33.6% |
XRO | Xero | 1.5% | $62.59 | -3.8% | -45.0% |
TNE | Technology One | 0.9% | $31.80 | -2.9% | 15.4% |
BVS | Bravura Solutions | 0.7% | $3.40 | 0.7% | 32.1% |
CAT | Catapult Sports | 0.7% | $3.42 | 3.5% | -17.9% |
HSN | Hansen Technologies | 0.7% | $3.55 | -2.9% | -32.9% |
AD8 | Audinate Group | 0.5% | $2.07 | -0.5% | -49.0% |
IFT | Infratil | 0.4% | $10.00 | 0.5% | 4.4% |
MAQ | Macquarie Technology Group | 0.0% | $50.20 | 6.8% | -25.1% |
DTL | Data#3 | -0.1% | $14.78 | 10.3% | 64.8% |
PME | Pro Medicus | -0.3% | $192.75 | -4.4% | -12.6% |
SDR | Siteminder | -0.4% | $3.37 | 18.9% | -45.1% |
CDA | Codan | -1.8% | $58.88 | 4.2% | 107.2% |
MP1 | Megaport | -2.8% | $17.21 | 5.3% | 51.7% |
WBT | Weebit Nano | -4.9% | $2.25 | -6.5% | -55.1% |
AMP sinks as China partnership growth stalls
[1:02 pm] Finally, an explanation as to why AMP is down 15.3% in the last two sessions.
UBS has cut its AMP earnings forecasts after the latest solvency report from China Life Pension Company (CLPC), AMP’s 19.99%-owned Chinese pension business, showed profit growth stalling in the September quarter.
China partnerships contributed $56m in 1H26, up 107% from $27m and almost a third of group underlying profit, with CLPC the main driver
CLPC’s 3Q26 NPAT slipped 0.3% year-on-year to $486m yuan, a sharp slowdown from 58% growth in 2Q26 and 96% in 1Q26, implying about $20m for AMP’s stake
On a quarterly basis, CLPC profit fell 9.5% from RMB537m in 2Q26, its second straight quarterly decline after a 24% drop from 1Q26’s RMB711m
Weaker equity markets are the likely cause, with the CSI 300 down 12.5% in 3Q26 and down another 8% so far in 4Q26
AMP’s unchanged FY26 guidance of a 12–15% annualised partnership ROI implies $56m of 2H26 contribution at the midpoint, below the $65m consensus and pointing to 6% downside to 2H26 group consensus
EPS forecasts cut 4.6% for FY26 and 4.8% for FY27, with Neutral retained and the price target trimmed to $2.60 from $2.61 as higher platform peer multiples largely offset the earnings cut
Westpac’s cost discipline offsets margin squeeze, but brokers stay cautious
[12:54 pm] Brokers gave Westpac’s FY26 result a lukewarm reception, with cost discipline and lower bad debts offsetting a weak exit margin that leaves them wary on revenue into FY27.
Net interest income up 1.5% to $9.9bn vs $10.0bn ests (1% miss)
Group NIM down 3bps to 1.86% vs 1.89% ests, with core NIM also down 3bps to 1.75%
Costs down 1.6% to $5.8bn vs $6.0bn ests (3% beat)
Impairment charges of $421m, or 9bps of loans vs 10bps ests
2H26 NPAT (ex notables) flat at $3.6bn vs $3.6bn ests (in line)
Final dividend of 77cps fully franked vs 78cps ests (1% miss)
CET1 ratio of 12.5% vs 12.3% ests, with about 22bps of buyback impact still to come
FY27 outlook targets more than $600m of productivity benefits with cost growth similar to FY26, while housing credit growth expectations were cut to 3.8% from 4.7%
Here are the key takeaways from brokers:
UBS says weaker 2H26 revenue was offset by cost discipline and lower than expected bad debts, but deposit and lending competition shaved 5bps off core NIM and is likely to carry into FY27. With UNITE spend and execution risk ramping up, it sees little room for cost slippage, and notes Westpac trades at 17.4x two-year forward earnings, more than one standard deviation above its historical average
Morgan Stanley (Underweight, $30 target) called it a solid result, with a 1% revenue miss offset by lower loan losses, costs 1% better than expected and CET1 15bps ahead of its forecast. The concern is the core margin, which implies a 5bps fall to 1.73% in 4Q26, a trend the broker expects will draw questions given Westpac didn’t disclose an exit margin
Macquarie (Underperform, $30 target) says costs look in hand, but sector-wide revenue pressure leaves downside risk to earnings and consensus. Consumer impairments tripled to $238m and mortgage arrears rose about 5bps, while a $70m cut to provision coverage effectively accounted for the impairments beat. It sees the read-through as supportive for ANZ, with CBA most exposed to weaker retail banking conditions
Company page: Westpac (WBC)
Kospi slides 3% as US chip rout spills into Asia
[11:57 am] Asian markets opened lower as the selloff in US chipmakers deepened, with a plunge in oil prices doing little to revive appetite for tech.
The MSCI Asia Pacific index fell 0.4% and South Korea’s Kospi dropped almost 3%, while Japan is closed for a holiday
US stock futures rose 0.2% and Hang Seng futures gained 0.7%, a sign some investors are buying the dip
China’s central bank said it will encourage financial institutions to make greater use of its stock-support tools and improve their terms to bolster market stability
The Nasdaq Golden Dragon China Index rose 2.3% in US trade, its biggest gain since 9 October, though Citi’s Xiangrong Yu expects the measures to stabilise the market rather than spark a durable rally
The CSI 300 fell 8.5% in October, its worst month in more than a decade, after earlier support efforts including national team buying fell short
“Lower oil should be a tailwind for tech, but the fact that stocks could not hold the open even with crude plunging shows how little conviction is left even after last week’s carnage,” said Roundhill Financial CEO Dave Mazza
Source: Bloomberg
Top ASX 300 gainers and losers
[11:16 am] Looking slightly outside the ASX 200, you've got names like Chalice Mining bouncing (despite palladium falling a further 1.0% overnight to US$970/oz), Virgin outpacing Qantas amid the oil price pullback and battered data centre plays also catching a bounce.
Ticker | Company | % Chg | Price | 1 Week | YTD |
|---|---|---|---|---|---|
CHN | Chalice Mining | 7.9% | $1.02 | 12.1% | -51.9% |
VGN | Virgin Australia | 7.3% | $2.66 | 11.8% | -24.2% |
QAN | Qantas Airways | 5.9% | $9.32 | 10.8% | -10.4% |
SBM | St. Barbara | 4.6% | $0.74 | -5.4% | 29.1% |
NXT | NextDC | 4.0% | $6.19 | 10.1% | -49.7% |
DGT | Digico Infrastructure REIT | 4.0% | $2.36 | 15.1% | -15.4% |
ZIP | Zip Co | 3.7% | $1.88 | 16.2% | -42.4% |
NWL | Netwealth Group | 3.7% | $18.91 | 9.9% | -25.9% |
AAI | Alcoa Corporation | 3.7% | $57.36 | 4.2% | -28.5% |
AEF | Australian Ethical Investment | 3.7% | $4.54 | 8.1% | -10.3% |
AMP still tops the laggards, along with the entire energy complex, spanning oil and gas, uranium, coal and refiners.
Ticker | Company | % Chg | Price | 1 Week | YTD |
|---|---|---|---|---|---|
AMP | AMP | -7.7% | $2.17 | -11.4% | 19.6% |
PYC | PYC Therapeutics | -5.8% | $1.79 | 2.3% | 8.3% |
YAL | Yancoal Australia | -4.9% | $5.78 | -6.7% | 16.0% |
NXG | Nexgen Energy | -4.6% | $11.30 | -4.0% | -19.2% |
SMR | Stanmore Resources | -4.6% | $2.39 | -11.3% | 2.4% |
WDS | Woodside Energy Group | -4.4% | $31.94 | -3.7% | 34.6% |
WHC | Whitehaven Coal | -4.4% | $7.38 | -6.0% | -5.0% |
NHC | New Hope Corporation | -4.4% | $5.67 | -6.4% | 41.4% |
AEL | Amplitude Energy | -4.4% | $1.86 | -2.4% | -36.0% |
VEA | Viva Energy Group | -4.3% | $2.77 | -4.0% | 33.6% |
Apple slips 3% as margin outlook overshadows upbeat holiday forecast
[11:15 am] Apple shares fell about 3% after hours in CEO John Ternus’ first result, with rising memory costs and spending on the new Siri set to squeeze gross margins over the holiday quarter.
Revenue up 12% to US$114.50bn vs US$113.39bn ests (1% beat)
iPhone revenue up 17% to US$57.58bn vs US$56.48bn ests (2% beat), despite only the iPhone 18 Pro line launching in September
Greater China revenue up 21% to US$17.54bn vs US$18.55bn ests (5% miss)
December quarter revenue growth guidance of 7–10%, with the 8.5% midpoint above ests of 6.1%
December quarter gross margin guidance of 45–46%, with the midpoint 1.5 percentage points below ests of 47%, down from above 50% in the June quarter
Source: Bloomberg
Top ASX 200 gainers
[10:19 am] Qantas is trading sharply higher thanks to the oil pullback, while mining services, gold and copper names catch a bid in early trade.
Ticker | Company | % Chg | Price | 1 Week | YTD |
|---|---|---|---|---|---|
QAN | Qantas | 5.8% | $9.31 | 10.7% | -10.5% |
IPX | Iperionx | 3.7% | $2.24 | 22.1% | -59.3% |
IMD | Imdex | 3.7% | $3.38 | 6.6% | -1.5% |
RSG | Resolute Mining | 3.6% | $1.14 | 5.1% | -6.9% |
ZIP | Zip | 3.6% | $1.88 | 16.0% | -42.5% |
GMD | Genesis Minerals | 3.5% | $6.57 | 2.2% | -8.2% |
AMC | Amcor | 3.4% | $69.29 | 5.0% | 10.8% |
KCN | Kingsgate | 3.4% | $3.95 | -5.3% | -29.5% |
VAU | Vault Minerals | 3.4% | $5.48 | 3.2% | 0.7% |
CSC | Capstone Copper | 3.3% | $11.64 | 1.2% | -23.2% |
Top ASX 200 losers
[10:19 am] AMP is extending its slide after Monday’s 7.5% fall (still no idea why), while the broader energy complex, from oil and gas producers to refiners, uranium and coal names, trade lower across the board.
Ticker | Company | % Chg | Price | 1 Week | YTD |
|---|---|---|---|---|---|
AMP | AMP | -5.5% | $2.22 | -9.4% | 22.3% |
KAR | Karoon Energy | -4.7% | $1.63 | -2.7% | 5.8% |
NXG | NexGen Energy | -4.0% | $11.38 | -3.3% | -18.6% |
VEA | Viva Energy Group | -3.6% | $2.79 | -3.3% | 34.5% |
STO | Santos | -3.5% | $8.81 | -4.3% | 42.5% |
WDS | Woodside Energy Group | -3.4% | $32.30 | -2.6% | 36.1% |
ALD | Ampol | -3.3% | $37.71 | -4.6% | 18.1% |
YAL | Yancoal Australia | -3.3% | $5.87 | -5.2% | 17.9% |
WHC | Whitehaven Coal | -3.2% | $7.47 | -4.8% | -3.9% |
HLI | Helia Group | -3.0% | $4.84 | -9.7% | -14.6% |
ASX 200 higher as miners bounce and energy stocks slump
[10:16 am] The S&P/ASX 200 is up 38 points (+0.43%) in early trade, with miners bouncing after a strong overnight session for commodities outside of energy. REITs are higher again and now sit about 6.8% above their early October lows as bond yields continue to roll over, while Discretionary stocks are still catching a bid. On the flip side, Energy stocks have opened sharply lower after oil tumbled about 8% overnight, and recent high-flyers like Staples and Healthcare are taking a breather.
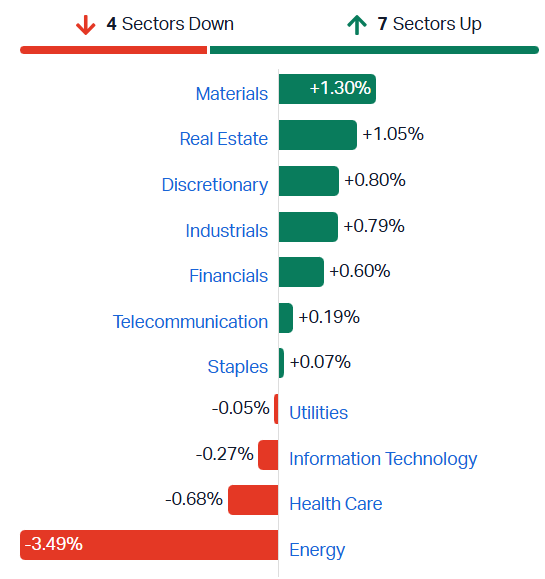
S&P/ASX 200 sectors (Source: Market Index)
Anthropic taps Macquarie and CommSec for Australian retail IPO offer
[9:58 am] Australian retail investors will be able to buy into Anthropic’s Nasdaq float, with the Claude maker naming eight local brokers and platforms to handle its retail offer.
The selling agents are Macquarie, CommSec, Morgans, Bell Potter, LGT Wealth Management, Stake, Morgan Stanley Wealth Management Australia and Sharesies
Australia is one of only a few markets outside the US where shares will be sold directly, alongside Japan, Canada and parts of Europe
The retail offer will open once Anthropic lodges an Australian prospectus with ASIC, which will be posted on its Australian IPO website
Sophisticated and professional investors can participate directly in the US offering without waiting for the Australian filing
Anthropic is set to list before US Thanksgiving on 26 November and is aiming to match or exceed SpaceX’s US$86.2bn debut earlier this year
Source: Bloomberg
Sigma Lithium refinances with $100m convertible as cash dips to $10m
[9:42 am] Brazilian lithium producer Sigma Lithium has replaced its expensive secured debt with a US$100 million convertible bond, as operations restart following a shutdown during the September quarter.
TSX-listed Sigma Lithium shares tumbled 24.2% to C$7.21, now down 67% YTD.
The five-year convertible bond carries a 7.0% fixed coupon, replacing an 11.45% floating rate, with a 25% conversion premium into its ASX-listed CDIs and no conversion in the first 12 months
Proceeds will repay senior secured debt with Synergy Capital, cutting short-term debt by 78% to US$28m from US$125m and pushing maturities out to 2031
Cash of US$10m at 30 September, with a further US$62m in potential short-term liquidity from inventory sales and offtake instalments
3Q26 production of 7,293t of high-grade lithium concentrate, with 21,000t of lower-grade material left unprocessed due to the shutdown
CIF China cash costs down 5% to US$518/t from US$543/t in 3Q25, with gross margin of 32%
FY26 AISC guidance cut 6% to US$668/t from US$710/t, while FY27 guidance of US$620/t was maintained
Production guidance of 240kt over the next 12 months was reiterated, rising to an annualised 330kt in FY27
Company page: Sigma Lithium (SGML)
Coast Entertainment flags 20%-plus returns on Dreamworld hotel precinct
[9:38 am] Dreamworld owner Coast Entertainment has told its AGM it intends to lead development of a hotel and entertainment precinct on its Coomera land, as it looks to close a steep discount to the value of its assets.
The market implies a value of about $165m for Dreamworld and SkyPoint after adjusting for $35m in cash, a 55% discount to their independent fair value of about $348m
A Barrenjoey review found developing the hotel and entertainment, dining and retail precinct itself is the most attractive option, though Coast remains open to capital partners
The analysis points to levered IRRs above 20% across the hotel and precinct, with an estimated value on completion of about $330m
Coast is not yet committing to build, with the project subject to technical studies, cost validation and a final investment decision, and the parks funded ahead of any development spend
The core business has delivered four consecutive years of positive Theme Parks and Attractions EBITDA, with attendance still below historical levels
“Doing nothing is not risk-free either. It means choosing to leave that value on the table. Waiting has a cost of its own. It will almost certainly never be cheaper to build than it is today”
Company page: Coast Entertainment (CEH)
Tivan upgrades Speewah fluorite resource to Indicated ahead of DFS
[9:37 am] Critical minerals developer Tivan has upgraded the majority of its Speewah fluorite resource in WA’s Kimberley to the Indicated category, a key step towards declaring Ore Reserves for its Detailed Feasibility Study.
Total resource up 4% to 45.0Mt at 7.8% CaF2 (fluorite) for 3.5Mt of contained CaF2, with grade and contained metal broadly in line with the February 2026 estimate
The majority of the resource is now classified as Indicated, which is required before it can be converted into Ore Reserves
The high-grade component stands at 8.6Mt at 22.3% CaF2 for 1.9Mt of contained CaF2
The update follows about 14km of infill, extension and metallurgical drilling in 2026, with a best hit of 76m at 21.6% CaF2 from surface, including 22m at 39.0%
The upgraded resource will feed mine planning and production scheduling for the DFS, which is focused on producing acid-grade fluorspar (>97% CaF2) for export
Company page: Tivan (TVN)
Arena REIT firms up FY27 distribution guidance at 20cps
[9:37 am] Childcare and healthcare landlord Arena REIT has firmed up its FY27 distribution guidance after making substantial progress on resolving its exposure to tenant Edge Early Learning.
FY27 distribution guidance of 20.0cps implies 3.9% growth on FY26, towards the top of the range provided on 19 October
The guidance assumes all announced transactions on Edge centres receive service approvals and lease assignment consents, with no new acquisitions
Two more early learning centres were contracted for sale in October, taking FY27 divestment proceeds to $23.1m at a 7.9% premium to book value
Operating early learning centres sold so far have transacted at a weighted average passing yield of 5.35%
Arena is still weighing how to use the proceeds from its capital recycling program, having regard to its balance sheet, cost of capital and capital management program
Company page: Arena REIT (ARF)
Airlines and homebuilders lead US sector gains as energy stocks slump
[9:30 am] Falling oil prices sparked a rotation across US sectors, with fuel-sensitive airlines rallying while energy producers sold off.
This is my overnight ETF watchlist, which helps me gauge how specific sectors performed in response to overnight conditions.
Ticker | Company | % Chg | Price | 1 Week | YTD |
|---|---|---|---|---|---|
JETS | US Global Jets | 4.2% | $28.05 | -1.8% | 16.0% |
XHB | State Street S&P Homebuilders | 3.6% | $104.58 | 6.3% | -0.4% |
GDX | Vaneck Gold Miners | 2.7% | $79.15 | -10.2% | 8.6% |
EBIZ | Global X E-Commerce | 2.4% | $29.42 | 6.4% | -12.6% |
ITA | Ishares US Aerospace & Defence | 2.4% | $214.68 | 2.5% | -0.4% |
SIL | Global X Silver Miners | 1.5% | $72.32 | -17.0% | 7.0% |
COPX | Global X Copper Miners | 1.2% | $72.84 | -13.7% | 18.3% |
SLX | Vaneck Steel | 1.2% | $100.55 | -1.7% | 27.6% |
FINX | Global X Fintech | 0.8% | $24.07 | -2.8% | -26.8% |
NIKL | Sprott Nickel Miners | 0.6% | $10.54 | -20.8% | -26.2% |
REMX | Vaneck Rare Earth And Strategic Metals | 0.5% | $50.26 | -20.4% | -28.7% |
LIT | Global X Lithium & Battery Tech | 0.4% | $60.05 | -12.7% | -3.4% |
COAL | Range Global Coal Index | -1.2% | $23.44 | -1.7% | 4.2% |
HYDR | Global X Hydrogen | -1.2% | $34.52 | -22.4% | -22.1% |
IBB | Ishares Biotechnology | -1.8% | $213.79 | 3.4% | 36.4% |
IGV | Ishares Expanded Tech-Software Sector | -2.3% | $101.90 | -7.0% | -11.1% |
URA | Global X Uranium | -2.4% | $32.93 | -17.9% | -41.7% |
CLOU | Global X Cloud Computing | -2.4% | $27.35 | -6.5% | 14.8% |
XBI | State Street S&P Biotech | -2.5% | $152.05 | -2.8% | 35.9% |
XLE | State Street Energy Select Sector | -4.0% | $67.25 | 8.7% | 53.4% |
Oil and gas slump on Iran peace hopes, gold and silver rally
[9:27 am] Energy prices tumbled overnight as the US and Iran signalled openness to talks, while precious metals pushed higher.
Brent crude fell 8.1% to US$104.19 a barrel and WTI dropped 6.5% to US$96.25
European TTF gas futures fell 8.7% to €94.86 per megawatt hour
Gold rose 1.8% to US$3,946.50/oz, while silver jumped 3.1% to US$50.64/oz
Copper rose 0.8% to US$6.61/lb and nickel gained 1.5% to US$15,428/t
Iron ore futures were flat at US$91.25/t
Macquarie’s quants back Point of Law to win the Melbourne Cup
[9:13 am] Macquarie’s quant desk has named Point of Law as its 2026 Melbourne Cup pick, with both its traditional and enhanced models landing on the same horse.
Point of Law scored 81.3 points on Macquarie’s traditional quant model, ahead of So You Are on 80 and Juja Kibo on 78.8
The enhanced model, which adds a market narrative overlay, also picks Point of Law, with Shockletz and Hopewell Rock placing second and third
The pick is hardly contrarian, with Point of Law, a three-year-old sold by King Charles to an Australian syndicate including John Wylie, already the top pick of several bookmakers
The quants are on a decent streak, having correctly picked Half Yours in 2025 and Without A Fight in 2023, with the note now in its 19th year
“This year, concentrated equity markets reminded investors that dismissing market leadership can be costly, so we give greater recognition to the Cup favourites,” the analysts wrote
Source: AFR
Prediction markets back Democratic sweep as US midterms get underway
[9:10 am] Americans head to the polls with prediction markets pricing a strong chance Democrats win both chambers of Congress, though full results could take days to land.
Kalshi, the largest prediction market by volume, gave Democrats a 94% chance of winning the House and 75% for the Senate as of Monday afternoon US time
Democrats need a net gain of three seats to win the House and four for the Senate, where Republicans need only 50 seats given Vice President JD Vance’s tie-breaking vote
The first polls close in Kentucky and Indiana at 6pm New York time, or 10am AEDT Wednesday, with Alaska’s final polling place closing at 5pm AEDT
Control of the House took eight days to call in 2022, and a close result could again hinge on California, which counts mail ballots arriving up to seven days after election day
Senate control could take longer, with Alaska’s ranked-choice count unable to begin until 18 November once all mail ballots arrive
Source: Bloomberg
Apple tops estimates on record iPhone sales, but China misses
[9:01 am] Apple posted a record September quarter revenue of US$114.5 billion, though tariff refunds flattered its earnings beat and Greater China fell well short.
The result was released after the bell, with Apple shares up 0.8% after hours.
Revenue up 12% to US$114.50bn vs US$113.39bn ests (1% beat)
iPhone revenue up 17% to US$57.58bn vs US$56.48bn ests (2% beat)
Services revenue up 10% to a record US$31.57bn vs US$31.58bn ests (in line)
Greater China revenue up 21% to US$17.54bn vs US$18.55bn ests (5% miss)
EPS of US$2.10 vs US$1.99 ests (6% beat), including a US$0.05 boost from tariff refunds that also added 1 percentage point to gross margin
Palantir beats and raises as US commercial revenue jumps 148%
[8:58 am] Palantir CEO Alex Karp says the company has essentially doubled its business in a year, with US commercial revenue now overtaking government sales for the first time.
The result was released after the bell, with Palantir shares up 1.0% after hours.
Revenue up 96% to US$2.31bn vs US$2.18bn ests (6% beat)
US commercial revenue up 148% to US$984m vs US$943m ests (4% beat)
Adjusted operating income of US$1.43bn vs US$1.26bn ests (13% beat)
4Q26 revenue guidance of US$2.649–2.653bn, with the midpoint 8% above ests
FY26 revenue guidance raised to US$8.530–8.534bn, with the midpoint 4% above ests
US voters head to midterms in sour mood despite solid growth
[8:57 am] Americans go to the polls frustrated by the cost of living, even as economic growth and the jobs market hold up.
US GDP grew at a 3.4% annualised pace in the September quarter, its strongest this year, with business investment up 12.7% on AI demand
Unemployment was 4.2% in September and has not topped 4.5% for five straight years, the longest stretch on record
October payrolls due Friday are forecast to more than double to 65,000, with unemployment steady at 4.2%
Consumer prices and average hourly earnings have both risen about 5.5% since January 2025, leaving real wages flat over Trump’s second term
The University of Michigan sentiment index sits near a record low, while the Conference Board’s confidence measure improved in October
Construction spending fell 1.9% in September vs ests of a 0.4% rise, its steepest monthly drop since April 2020, led by a 5.5% slide in residential
The Fed held rates at 3.75–4.00% last week after hiking in September, and is expected to raise again in December, with 30-year mortgage rates above 7%
Source: Reuters
US manufacturing beats expectations but price pressures stay hot
[8:56 am] US factory activity picked up more than expected in October on strong domestic and AI-related demand, though input costs remain elevated and sentiment soured for a third straight month.
The ISM manufacturing PMI rose to 55.5 from 54.5 in September vs ests of 54.5
Production jumped 2.3 points to 59, its highest reading since November 2021, while new orders edged up to 55.5 from 55.3
The prices paid index eased to 75.2 from 77.9, with aluminium, copper, diesel and memory chips still rising in price
Employment eased to 52.4 from 52.7
ISM’s Susan Spence said general sentiment worsened for a third month, with 66% of respondent commentary negative, led by pricing volatility, longer lead times, tariffs and the war
US automakers push Congress for permanent ban on Chinese cars
[8:55 am] A lobby group representing nearly all major automakers is urging US lawmakers to pass a permanent ban on Chinese vehicles in the short post-midterm session.
The Alliance for Automotive Innovation, which represents General Motors, Toyota and Volkswagen among others, wants the bill passed when Congress returns next week
The bill passed a Senate committee in July and the House version has more than 100 co-sponsors
Aides and lobbyists warn there may not be time to pass it before the session ends in December if Democrats win control of Congress
The EU imported more than 1.1 million Chinese vehicles in the first eight months of 2026, more than in all of 2025
Trump said in September he would accept Chinese carmakers building cars in the US, though a Biden-era rule effectively bars them and Chinese EVs face tariffs above 100%
Source: Reuters
Anthropic quarterly revenue jumps twelve-fold to $17bn ahead of IPO
[8:53 am] Claude maker Anthropic disclosed about US$17 billion in third quarter revenue in its amended IPO prospectus, though quarterly growth slowed sharply and spending commitments swelled to almost US$900 billion.
Third quarter revenue up about 1,127% year-on-year to roughly US$17bn
Quarter-on-quarter growth slowed to about 47%, from 144% in 2Q26 and 132% in 1Q26
Nine-month revenue up about 1,200% to US$33.24bn
Third quarter net loss almost doubled to US$23.29bn
Nine-month net loss of US$104bn vs US$25.1bn in the same period of 2025, mostly due to fair value changes on convertible notes and derivative liabilities
Purchase commitments and leases total about US$895.4bn, substantially all tied to compute and infrastructure
Compute and infrastructure expenses up 329% over the nine months, an increase of US$14.4bn
Oracle leads Big Tech’s return to bond market with $20bn raise
[8:52 am] Big Tech is back in the US bond market after an almost three-month absence, with Oracle raising US$20 billion across debt and equity as investors demand higher premiums to fund the AI buildout.
Oracle shares fell 8.8% to US$119.22 after it launched US$10bn of bonds alongside a US$10bn share sale
Peak demand for the bond deal reached about US$38bn, nearly four times its size, with Oracle paying roughly 0.3 percentage points over its existing debt
Meta is eyeing at least US$20bn from a multi-currency sale including its debut euro deal, after S&P Global revised its credit outlook to negative on AI capex
Microsoft sold US$25bn of bonds last Thursday, its first US offering since 2017, while Alphabet paid up for a €6bn euro bond after its earnings miss
The average spread on US investment-grade tech bonds has widened to 1.08 percentage points from 0.76 at the end of 2025
“Oracle’s AI strategy carries material credit risks given the aggressive spending and uncertain path to positive cash flow,” said S&P Global Ratings
Source: Bloomberg
Morgan Stanley says US correction in its ‘final innings’
[8:51 am] Morgan Stanley’s Mike Wilson says the US market correction that began in June is close to an end, with Tuesday’s midterm elections set to clear a major overhang.
Wilson noted 60% of Russell 3000 stocks have already fallen at least 20% since June, as the S&P 500 catches down to weak breadth, typically the last stage of a slump
Large caps have typically gained 15% in the six months after midterm results, with Morgan Stanley saying a Democratic sweep is already priced in
Wilson sees the S&P 500 heading toward 8,000 regardless of the outcome, about 6% above Monday’s close
Morgan Stanley flagged renewed military escalation with Iran or new tariffs as the bigger risks after the vote
Wilson does not expect the Fed to rush to cut rates, but sees relief from the US Treasury drawing its cash pile down to about US$850bn by year-end from about US$1.05tn
“We expect near-term clearing events to provide an attractive opportunity to add risk to quality cyclicals that have de-rated as we head into 2027,” Wilson said
Source: Reuters
Oil sinks 8% as Iran’s supreme leader backs peace talks
[8:40 am] Oil posted its biggest daily fall since July after Iran’s supreme leader gave the government the green light to negotiate, stripping out much of the risk premium built up ahead of the US midterms.
Brent fell 8.0% to US$104.30 a barrel
Oil had rallied more than 10% in October to a six-month high as traders priced in a post-election escalation, with Trump repeatedly threatening to resume strikes after the vote
Iranian President Masoud Pezeshkian said Supreme Leader Mojtaba Khamenei has granted the government certain powers to resolve the conflict through dialogue
Trump told reporters Iran wants to make a deal and that one could happen, and signalled no when asked whether he would resume strikes after Tuesday’s vote
Tehran wants the US naval blockade lifted, sanctions eased and frozen assets released before reopening the Strait of Hormuz, while Washington is demanding nuclear concessions
Khamenei has also ordered military commanders to prepare for renewed confrontation, and the International Crisis Group’s Ali Vaez described the negotiating mandate as narrow with clear red lines
European gas futures fell almost 11% at one point, while US heating oil posted its steepest drop in six months
Nasdaq 100 enters correction as chip rout overshadows oil slump
[8:39 am] A three-day selloff in chipmakers pushed the Nasdaq 100 into a technical correction, offsetting a rally in old economy stocks as oil tumbled on US-Iran peace hopes.
The S&P 500 fell 0.51% to 7,541.40 and the Nasdaq dropped 1.07% to 25,164.32, after being up as much as 1.1% and 1.4% respectively earlier in the session
The Nasdaq 100 is now down 10% from its October peak, while a gauge of chip giants has fallen 12% over three sessions
Apple fell almost 2% ahead of its results after the bell, which beat on revenue but missed on China sales
The 10-year Treasury yield fell 2 bps to 4.91%
Marvell sinks 13% on US$115bn Lumentum takeover
[8:38 am] Chipmaker Marvell Technology has agreed to buy optical components maker Lumentum in a deal valued at US$115 billion, one of the largest tech deals on record, but investors sold off both stocks.
Lumentum shareholders will receive 4.5 Marvell shares for each share held, giving them about 33% of the combined group
Marvell shares fell 12.7% to US$171.41 and Lumentum dropped 18%
Marvell expects the deal to expand its addressable market to US$550bn, deliver more than US$1bn in annual cost synergies and be earnings accretive in the first year after closing
“AI infrastructure is undergoing a fundamental architectural shift toward optical connectivity,” said Marvell CEO Matt Murphy
Good morning!
[8:29 am] ASX 200 futures are up 55 pts (+0.62%). Here's what happened overnight:
Wall Street’s rebound lost steam as tech selling resumed, while the Dow held gains and cyclicals led ahead of Tuesday’s US midterm elections
S&P 500 (-0.51%), Equal-weight S&P 500 (-0.76%)
Nasdaq (-1.07%), Dow (+0.41%), Russell 2000 (-0.21%)
Oil suffered its steepest drop in about three months after Iran’s supreme leader approved talks with Washington and Trump signalled diplomacy would get more time
AI financing stayed front and centre as Oracle filed a US$20bn stock and bond raise and Anthropic disclosed US$895bn in compute commitments in its revised IPO filing