ASX 200 Live Today - Wednesday, 14th October
The ASX 200 is set to fall after a choppy overnight session on Wall Street and broad commodity price weakness. Here are today's top stories.
Today’s ASX 200 Updates
The live blog has wrapped up for Wednesday, October 14. Thanks for following along, and we’ll be back tomorrow morning. Let us know how we can make it even better.
ASX 200 set to snap three-day win streak as banks unwind Tuesday’s rally
[2:20 pm] The ASX 200 is down 59 points (-0.68%) and on track to snap a three-day win streak. The ASX 200 Banks Index is down 1.7%, off session lows but still on track to give back all of Tuesday’s 1.9% rally.
Miners are mostly lower, with BHP down 0.6% and Rio Tinto down 0.3%. The All Ords Gold Index is down 1.5%, with Evolution Mining (-4.2%) a notable laggard following its 1Q27 report.
Lithium stocks are bouncing after the recent sell-off in lithium prices, with PLS Group and IGO both up 3.2% and MinRes up 2.1%. PLS had fallen 20.6% over the prior four sessions.
Energy stocks continue to grind higher, up 5.2% over the past two weeks but still about 4% below their 7 April high.
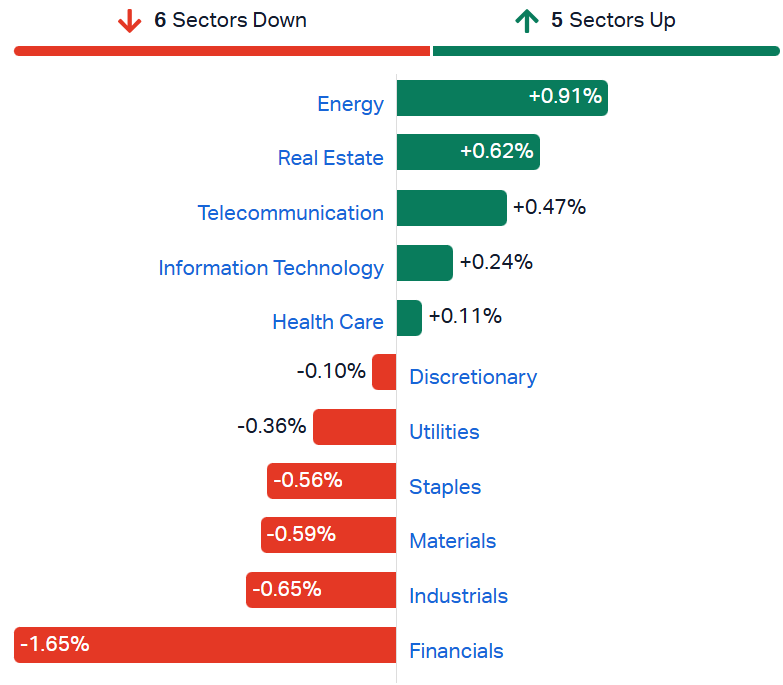
S&P/ASX 200 sectors (Source: Market Index)
Overall, markets continue to remain choppy at best, just look at how banks caught an aggressive bid on Tuesday, only to give it all back today. The Small Ords has slumped 10.7% since 25 August, falling in close to a straight line to its lowest level since June 2025. The Emerging Companies Index has followed a similar path, down 8.7% since 24 September to a two-month low. Both are now in what I call ‘no man’s land’, oversold and due for a bounce, but with no clear sign of where they’ll bottom. On a more encouraging note, the Australian 10-year yield is making a tentative move lower. It’s down 7 bps over a five-day losing streak to 5.32%, a three-week low, and is trading below its 20-day moving average for the first time since August. It’s not the most dramatic move, but it’s a start.
Goldman initiates on data centres, backs Goodman and Megaport
[1:17 pm] Goldman Sachs has initiated coverage on the ANZ data centre sector, with Buy ratings on Goodman Group and Megaport and Neutral ratings on NEXTDC, DigiCo REIT and Macquarie Technology.
Goodman Group rated Buy with a $32 target (22% upside), with Goldman valuing its share of the data centre power bank at $28bn vs $11bn implied by its share price
Megaport rated Buy with a $25.90 target (31% upside), backed by its carrier-neutral global network and a full-stack AI offering bundling network, compute and storage
NEXTDC rated Neutral with an $11 target (6% upside), as structural demand looks largely priced in and rising financing costs leave a roughly $1bn funding shortfall against work in progress
DigiCo REIT rated Neutral with a $2.60 target (8% upside), with growth hinging on the FY27-28 ramp-up at SYD1 and distributions not fully funded by FFO
Macquarie Technology rated Neutral with a $58 target (14% upside), with data centres the core value driver as it converts its 47MW IC3SW site into billing capacity
China’s producer prices jump 5% as oil and AI costs bite
[1:15 pm] China’s factory-gate inflation hit its fastest pace since 2022 in September, driven by surging oil prices and rising costs for AI-related goods.
PPI up 5% year-on-year, beating most estimates and marking the fastest pace since 2022
CPI up 0.9% from 0.8% in August, slightly below forecasts, with core CPI steady at 1%
Gasoline prices contributed about half a percentage point to the annual CPI increase
Margin squeeze as businesses struggle to pass on rising raw material costs, with industrial profits already growing at their weakest pace this year
Today's biggest intraday gainers and losers
[12:05 pm] These are the ASX 200 stocks with the biggest moves from today’s open, with defence and AI-related names catching a bid.
Ticker | Company | % Chg | % Chg from Open | Price |
|---|---|---|---|---|
ASB | Austal | 4.0% | 4.3% | $3.90 |
SLX | Silex Systems | 5.4% | 2.9% | $3.90 |
EOS | Electro Optic Systems | 2.4% | 2.4% | $9.34 |
GMG | Goodman Group | 1.9% | 2.2% | $27.01 |
SLC | Superloop | 3.3% | 2.1% | $2.47 |
DTL | Data#3 | 2.1% | 1.9% | $13.75 |
DBI | Dalrymple Bay Infrastructure | 0.9% | 1.8% | $5.60 |
NIC | Nickel Industries | 1.0% | 1.8% | $0.72 |
SIG | Sigma Healthcare | 1.7% | 1.7% | $2.77 |
RSG | Resolute Mining | 0.2% | 1.6% | $1.11 |
Paladin Energy has been sold off heavily after a weak September quarter production report, while gold miners have faded from a flat open and PLS Group is struggling to bounce after falling 20% over the past four sessions.
Ticker | Company | % Chg | % Chg from Open | Price |
|---|---|---|---|---|
PDN | Paladin Energy | -8.2% | -8.2% | $7.37 |
PDI | PDI Gold | -5.4% | -5.0% | $4.12 |
ORA | Orora | -4.3% | -4.0% | $1.33 |
CYL | Catalyst Metals | -3.4% | -3.6% | $5.41 |
NEC | Nine Entertainment Co | -3.4% | -3.4% | $0.63 |
KCN | Kingsgate Consolidated | -3.4% | -3.4% | $4.53 |
EVN | Evolution Mining | -3.5% | -3.3% | $12.50 |
PME | Pro Medicus | -2.6% | -3.0% | $161.44 |
NEU | Neuren Pharmaceuticals | -2.9% | -2.9% | $19.07 |
PLS | PLS Group | 1.0% | -2.5% | $3.11 |
Kiwi exodus to Australia hits 13-year high ahead of NZ election
[12:03 pm] New Zealand citizen departures to Australia hit their highest level in 13 years in the March quarter, adding pressure on Prime Minister Christopher Luxon ahead of the 7 November election.
12,471 departures to Australia in the March quarter, the most since the three months to March 2013
Returns rising with about 13,460 citizens coming back from Australia in the 12 months to March, the most since September 2021
Net exodus of 27,890 over the year, the lowest since the third quarter of 2023
Net migration inflows of 20,503 in the 12 months to August, up from a low of 9,163 a year earlier
Election pressure with Luxon’s National Party neck-and-neck with Labour in polling, amid criticism over living costs and jobs
Source: Bloomberg
Singapore’s MAS unexpectedly holds policy, lowers inflation forecast
[12:00 pm] Singapore’s central bank surprised markets by leaving policy unchanged, pausing after back-to-back tightening in April and July as it expects the energy crunch and AI boom to ease next year.
Policy band unchanged with only three of 20 economists surveyed by Bloomberg expecting the hold, as most tipped a steeper slope
Singapore dollar down 0.1% to 1.28 per US dollar after the decision
Core inflation forecast narrowed to 1.5% to 2% for 2026, from up to 2.5% previously, with both core and headline seen averaging 1.5% to 2.5% in 2027
Q3 GDP up 5.4%, beating the 5.1% median forecast but slowing from 6.2% in the second quarter, with AI driving factory activity, services and exports
Banks give back Tuesday’s rally as CBA slides 2.8%
[11:59 am] Banks are trading sharply lower, unwinding all of Tuesday’s rally. CBA is down 2.8% to $150.20, after climbing 2.3% on Tuesday to a near one-month high.
Ticker | Company | % Chg | Price | 1 Week | YTD |
|---|---|---|---|---|---|
CBA | Commonwealth Bank | -2.8% | $150.20 | -0.5% | -6.5% |
BEN | Bendigo & Adelaide Bank | -2.7% | $10.31 | 0.7% | -2.6% |
BOQ | Bank Of Queensland | -2.6% | $6.52 | 0.2% | -0.7% |
NAB | National Australia Bank | -2.2% | $38.37 | -0.6% | -9.2% |
WBC | Westpac | -1.9% | $34.48 | 0.1% | -10.4% |
ANZ | ANZ Group | -1.9% | $37.66 | -0.2% | 3.3% |
JDO | Judo Capital | -1.6% | $0.90 | -2.7% | -49.7% |
MQG | Macquarie Group | -1.1% | $249.02 | 0.0% | 22.7% |
The move could simply be a pullback after an outsized gain, or it may be tied to CBA’s in-principle enterprise agreement covering 35,000 staff. The AFR reported:
Pay rises of up to 13% over FY27-29 for the lowest-paid frontline staff, scaling down to 5% for packaged employees earning above $165,000
AI committee to be established to support dialogue with staff on AI-enabled change and reskilling, after CBA reversed a decision last year to replace call centre workers with AI
Industry benchmark with the union saying the deal sets the starting point for talks with NAB, whose agreement expires on 31 December, followed by ANZ and Westpac
Westpac leading index points to below-trend growth into 2027
[11:56 am] The Westpac-Melbourne Institute Leading Index held steady in September, pointing to growth at or slightly below trend heading into early 2027.
Leading Index growth unchanged at -0.03% in September, up from -0.16% in March
Below-trend 2026 with Westpac forecasting 1.5% growth, as higher fuel prices and the RBA’s September rate hike are still working through the economy
Positive contributors included unemployment expectations (+0.23ppts), consumer expectations and the ASX 200 (both +0.15ppts)
Drags were led by dwelling approvals (-0.34ppts) and monthly hours worked (-0.08ppts)
Narrow range of -0.3% to +0.5% since early 2025, compared with a historical range of -1.9% to +1.6% outside the COVID and GFC shocks
Source: Westpac
Glencore makes ASX debut under ticker GLC
[11:53 am] Glencore made its ASX debut today, with its CDIs down 1.8% to $11.24 in intraday trade.
Secondary listing adds to Glencore’s primary listing on the London Stock Exchange under GLEN and its secondary listing in Johannesburg under GLN, with the miner admitted to the ASX as a Foreign Exempt Listing
No capital raising was involved, and no new shares were issued as part of the listing
Copper growth funding is the main aim, with the listing designed to tap one of the world’s fastest-growing pools of institutional capital and potentially open the door to large M&A
Investor interest in an Australian listing was strong, according to CEO Gary Nagle, particularly after the miner’s failed merger talks with Rio Tinto earlier this year
ASX 200 inclusion is targeted within 12 months
Company page: Glencore (GLC)
Lithium futures slump on battery production cut chatter
[11:50 am] Macquarie says lithium prices are nearing cost-curve support after Chinese futures plunged on reports of battery production cuts, with CY27 demand uncertainty outweighing near-term market tightness.
GFEX lithium futures down about 12% to close at Rmb104,740/t, approaching the upper end of Macquarie’s estimated cost curve
CATL production cut of about 10% to its October battery plan was reported in market chatter, with similar adjustments across the supply chain, though Macquarie notes this hasn’t been verified
Spot lithium carbonate has fallen to Rmb119,500/t, 22% below the CY26 year-to-date average of Rmb152,650/t
Next cost-curve support sits at about Rmb80,000/t, where higher-cost producers representing about 10% of global supply could come under pressure
ESS rebate expiry has heightened concerns over further cuts into year-end ahead of the planned end of the 6% export VAT rebate, making the October ESS order book key to watch
EU hybrid curbs under consideration could halve Chinese hybrid imports, though Macquarie expects this to shift production to Europe rather than structurally reduce battery demand
Top ASX 200 gainers
[10:46 am] Energy stocks are extending their gains with Brent above US$106 a barrel, while battered lithium, rare earths and AI-linked names are bouncing back from yesterday’s sell-off.
Ticker | Company | % Chg | Price | 1 Week | YTD |
|---|---|---|---|---|---|
KAR | Karoon Energy | 7.1% | $1.66 | 6.8% | 7.5% |
SLC | Superloop | 3.3% | $2.47 | -2.4% | -5.4% |
ZIP | Zip Co | 3.1% | $2.19 | 5.0% | -33.2% |
MIN | Mineral Resources | 3.0% | $47.18 | -7.9% | -13.3% |
DTL | Data#3 | 2.7% | $13.83 | 0.5% | 54.2% |
NXT | NextDC | 2.6% | $9.62 | -7.9% | -21.9% |
ILU | Iluka Resources | 2.3% | $5.44 | -6.5% | -6.0% |
PLS | PLS Group | 1.9% | $3.14 | -18.4% | -25.2% |
SLX | Silex Systems | 1.9% | $3.77 | -18.0% | -55.3% |
STO | Santos | 1.9% | $9.08 | 6.0% | 46.8% |
Top ASX 200 losers
[10:46 am] Paladin Energy tanks after reporting higher-than-expected 1Q27 costs and lower-than-expected production, while banks, software and industrials trade mostly lower.
Ticker | Company | % Chg | Price | 1 Week | YTD |
|---|---|---|---|---|---|
PDN | Paladin Energy | -7.8% | $7.40 | -21.4% | -23.2% |
DMP | Domino's Pizza | -3.8% | $21.07 | 3.2% | 0.2% |
NEU | Neuren Pharmaceuticals | -3.3% | $18.99 | -5.5% | 2.0% |
ORA | Orora | -2.9% | $1.35 | -1.1% | -38.9% |
DYL | Deep Yellow | -2.8% | $0.86 | -26.2% | -53.3% |
PME | Pro Medicus | -2.6% | $161.38 | 1.9% | -26.9% |
PDI | PDI Gold | -2.3% | $4.25 | -8.0% | 16.4% |
BEN | Bendigo & Adelaide Bank | -2.0% | $10.39 | 1.5% | -1.9% |
MSB | Mesoblast | -2.0% | $1.99 | 1.3% | -27.1% |
FFM | Firefly Metals | -2.0% | $1.50 | -10.7% | -27.4% |
Morgan Stanley lifts Data#3 target after early guidance upgrade
[10:45 am] Morgan Stanley has raised its Data#3 price target to $13 from $11 following the company’s unscheduled upgrade, but kept its equal-weight rating on valuation grounds.
1H27 guidance points to gross profit up 15% and PBT up 40% on the pcp, both well ahead of pre-revision consensus
Upgrade drivers include large one-off transactions, $1.5m in higher interest income and the timing of investment spend, plus some acceleration in organic activity
Earnings upgrades of 4.5% to FY27-29 EBITDA and 6.7% to EPS, with FY27 PBT now forecast at about $92m
Early guidance is unusual for Data#3, which typically guides at its AGM in late October, and could point to further upside given its conservative track record
Valuation of about 33x FY27 earnings, which the broker says is “basically at peak valuation” and leaves risk-reward broadly balanced
Next catalysts are the AGM on 28 October and an investor day on 25 November
Company page: Data#3 (DTL)
GYG chair Guy Russo sells $35.6m in shares
[10:11 am] Guzman y Gomez chair Guy Russo has sold 23% of his holding through an off-market block trade.
1.39m shares sold at $25.50 each for $35.6m on 13 October
Remaining holding of 4.69m shares, with the sale including all 394,250 shares held by his superannuation fund
Personal financial planning was cited as the reason, with the sale made under GYG’s securities trading policy
Long-term holder having invested in GYG for about 17 years, with Russo a director since 2009 and chair since 2018
Commitment unchanged with Russo saying “I intend to remain as a significant long-term shareholder in GYG”
The announcement dropped right before the market opened (9:55 am AEDT). GYG shares dipped as much as 7.0% ($25.02) shortly after the open, currently down 3.8% to $25.86.
Company page: Guzman y Gomez (GYG)
Terra Metals releases PGM hits after ASX price query
[10:06 am] Terra Metals has released new drill results from its Southwest discovery after receiving an ASX price query over recent trading in its shares.
Price query response confirms TM1 held unreleased assay results at the time of the query, with the company requesting ASX lift its trading halt
Paid research in the form of an East Coast Research note on 12 October was also flagged as a possible contributor, with TM1 confirming it commissioned and paid for the note
Shallow RC drilling returned 194m at 1.01g/t 3E and 0.17% Ni from 15m, and 200m at 0.75g/t PGE3 from surface
Diamond drilling returned 181m at 1.12g/t PGE3 from 144.13m, including 56.87m at 1.69g/t PGE3
Assay backlog of more than 40,000 samples still awaiting results, with turnaround averaging about two months
Maiden resource targeted for Q1 CY27, with a scoping study to follow
So you're telling me Terra Metals paid for a research note published on Monday, which sent the stock up 34% to 19.5 cents on 3.2m shares traded, roughly 150% above its 20-day average of 1.3m, before it was halted at 1:36 pm? Shares resumed trading today alongside the assays and are down 12.8% to 17 cents.
Company page: Terra Metals (TM1)
Stakk lands US postal vote deployment ahead of midterms
[9:58 am] Stakk has secured another US government deployment, with its technology now live to help assess postal votes ahead of the 3 November midterm elections.
Multi-state rollout across several US states and counties, delivered through subsidiary ParaScript and strategic partners
Signature verification and document review designed to add a further layer of authentication and help flag potential fraud
Follows FBI engagement announced recently, adding to Stakk’s work with US government agencies at state and federal levels
No financial terms disclosed for the deployment
Company page: Stakk (SKK)
Praemium FUA up 7.4% as net flows ease
[9:57 am] Praemium lifted platform FUA in its Q1 FY27 update, though net flows slowed amid softer inflow conditions across the wealth sector.
Platform FUA up 7.4% to $34.4bn
Net flows of $274m, easing from strong levels in recent periods, with Spectrum supported by new client onboarding
Scope+ FUA up 30.3% to $45.5bn
Scope+ portfolios up 30.7% to 12,856, lifting their share of all Scope portfolios to 22.4% from 16.3%, even as total Scope portfolios fell 5.2%
Bell Potter transition to Scope+ complete, with portfolio numbers exceeding the initial target
Company page: Praemium (PPS)
Regal Partners FUM up 2.4% on 12th straight quarter of inflows
[9:54 am] Regal Partners’ FUM rose in its September quarter update, with hedge fund strategies driving another quarter of net inflows.
FUM up 2.4% on the prior quarter to $21.9bn
Net inflows of $671m marked a 12th consecutive quarter of positive flows, taking nine-month inflows to just over $2.0bn
Hedge funds drew $681m in net inflows, including $0.4bn raised for PM Capital Global Opportunities Fund through a placement and SPP
Sovereign credit mandate of $0.2bn received in August, with part deployed during the quarter
Investment performance broadly neutral at -$25m, as a $155m hit in hedge funds was offset by gains in credit and real assets
Commitments up 14% to $1.04bn, lifting total FUM and commitments to $23.0bn
Company page: Regal Partners (RPL)
Paladin misses on uranium output as costs jump
[9:34 am] Paladin Energy’s September quarter production fell short of ests after a planned shutdown and weaker recoveries at Langer Heinrich, though FY27 guidance was maintained.
U3O8 production down 19% on the prior quarter to 1.00Mlb vs 1.20Mlb ests (17% miss)
U3O8 sales down 14% on the prior quarter to 1.16Mlb vs 1.15Mlb ests (1% beat)
Realised price up 12% on the prior quarter to US$79.4/lb vs US$77.5/lb ests (2% beat)
Cost of production up 19% on the prior quarter to US$61.6/lb, well above FY27 guidance of US$44/lb to US$48/lb
FY27 production guidance of 5.1Mlb to 5.6Mlb maintained, with the 5.35Mlb midpoint in line with ests and output expected to lift in the second half
Cash and investments of US$209m, plus an undrawn US$70m revolving credit facility
PLS approvals progressed, with the CNSC agreeing to target completion of construction licence hearings by end-CY27
Company page: Paladin Energy (PDN)
Evolution misses on gold output, but costs land well below ests
[9:24 am] Evolution Mining’s September quarter gold production fell short of ests, but lower costs and strong cash generation kept FY27 guidance on track.
Gold production down 11% to 154koz vs 165koz ests (7% miss)
Copper production of 18kt
AISC down 4% to $1,653/oz vs $1,849/oz ests (11% beat)
Group cash flow of $185m, or $1,185/oz, including a record $186m in net mine cash flow from Ernest Henry
Net cash up to $141m from $19m in the June quarter
Major capex up 12% to $240m vs $272m ests (12% below)
FY27 guidance maintained across all measures
Company page: Evolution Mining (EVN)
Core Lithium produces first Finniss concentrate, eyes December quarter shipment
[9:22 am] Core Lithium produced first spodumene concentrate at Finniss in its September quarter report, less than six months after its final investment decision.
First shipment of new spodumene concentrate on track for the December quarter, with the plant still in commissioning and optimisation
Plant capacity up about 20% to 1.2Mtpa following brownfields upgrades, with a reflux classifier to be installed in FY27
BP33 underground development on schedule for first development ore in mid-CY27
BP33 drilling returned 34.08m at 2.09% Li2O, extending high-grade mineralisation beyond the current resource
Cash up 10% to $199.7m after receiving US$44m in convertible note funding, leaving Finniss fully funded to steady-state production in 2028
Stockpile sales completed with the final 25,000t of lithium fines sold to Glencore, taking 2026 stockpile revenue to about $38.5m
Company page: Core Lithium (CXO)
IAG offers to sell WA NRMA policies to win ACCC approval for RAC deal
[9:20 am] IAG has offered to offload its NRMA Insurance home and motor policies in Western Australia to address ACCC competition concerns over its proposed alliance with RAC.
NRMA renewal rights for active WA home and motor policies to be transferred to another insurer through a sale process
Net $1.2bn in premium added annually after the RAC alliance and NRMA transfer
Deal still EPS accretive in the first full year of ownership and mid-single digit accretive at full synergy run-rate
$100m in annual synergies pre-tax once integration is complete, with $15m to $25m in annual integration costs over three years
Further commitments include RAC home insurance in the state’s north, $20m in community investment over a decade and tougher pricing accountability
ACCC decision on the public benefits phase expected in December 2026, subject to extensions
Company page: Insurance Australia Group (IAG)
Rio Tinto holds guidance as capital release tops US$2bn
[9:14 am] Rio Tinto maintained all production and unit cost guidance in its Q3 production update, with Oyu Tolgoi copper and Pilbara iron ore driving the quarter.
Copper production flat at 205kt, taking year-to-date output to 646kt against unchanged 2026 guidance of 800kt to 870kt
Oyu Tolgoi production up 27% in Q3, with the mine running at a roughly 450kt annualised rate
Pilbara iron ore sales up 2% to 85.7Mt, with 2026 guidance of 323Mt to 338Mt unchanged
Simandou reached a roughly 10Mtpa annualised run-rate and remains on track for 60Mtpa during 2H 2028
Lithium production up 4% to 13.0kt LCE, with 2026 guidance of 61kt to 64kt now expected at the lower end
Pilbara cost pressures with diesel adding US$1.1/t and the stronger Australian dollar about US$1.0/t to full-year unit costs, though guidance is maintained
Capital release above US$2bn year-to-date, including the Dampier desalination plant sale and Kitimat land sale to LNG Canada, towards an initial US$5bn target
Company page: Rio Tinto (RIO)
Rio Tinto flags record-low copper TCs and weaker China steel demand
[9:13 am] Rio Tinto’s quarterly market review points to tight copper and aluminium markets, while softer Chinese steel demand weighs on iron ore.
Copper hit a record of US$14,850/t on the LME in mid-August, averaging US$14,110/t for the quarter
Copper TCs at a record low of -US$267/t as the concentrate market remained extremely tight
Iron ore steady around US$97/dmt, with higher freight costs squeezing netbacks for long-haul Atlantic supply
China steel consumption estimated down about 4% quarter-on-quarter and 2% year-on-year, partly offset by exports rising 3% to a 122Mt annualised rate
Aluminium in deficit with LME prices averaging US$3,226/t, 23% above the 2025 average
Lithium carbonate averaged about US$19,000/t, with battery storage shipments up 94% year-on-year in the first eight months of 2026
Company page: Rio Tinto (RIO)
Finbar to book Garden Towers settlements in 1H FY27
[9:12 am] Finbar’s largest development by lot count has been completed and titled, with settlements set to flow into first-half FY27 earnings.
Settlements commence with most expected within 14 days of titles being issued and revenue recognised in 1H FY27
82% sold with 279 of 342 lots sold for $210m, leaving 56 apartments and seven commercial lots
End value of about $296.9m for the 50:50 joint venture with Ventrade, a subsidiary of largest shareholder Chuan Hup
Tax settings CEO Ronald Chan said “the continued availability of negative gearing and capital gains tax concessions” is expected to support Perth apartment demand
$1.95bn pipeline over five years, with the recent Parkside Residences launch in Rivervale achieving 27 sales
Company page: Finbar Group (FRI)
Fletcher Building volumes lift but residential remains a drag
[9:12 am] Fletcher Building’s core businesses lifted volumes across most units in its Q1 volume update, though Residential & Development remains weak.
Light Building Products volumes up across every unit on the pcp, led by Fletcher Insulation up 13.6% and Iplex NZ up 13.1%
Pipeline volumes softer with Iplex NZ down 5.1% on Q4 FY26 as customers worked through stock bought ahead of Q4 price increases
Heavy Building Materials led by Dimond up 18.2% and ColorCote up 16.2% on the pcp, while Golden Bay Cement rose 2.0%
PlaceMakers frame and truss sales up 16.0% on the pcp
Residential units of 54 taken to profit, with rolling 12-month volumes down 38.6% and minimal contribution expected towards half-year earnings
Outlook uncertain with inflation and interest rates delaying the start of new commercial and residential projects
Company page: Fletcher Building (FBU)
Mercury trading margin up 19% despite dry Waikato inflows
[9:08 am] New wind and geothermal capacity helped Mercury offset historically dry Waikato conditions in its Q1 trading update. At the time of writing, NZX-listed Mercury shares are down 0.2% to NZ$6.76.
Trading margin up 19% to NZ$445m
Generation volume down 1% to 2,526GWh, with 307GWh of new wind and geothermal output mostly offsetting lower hydro
Hydro generation down 24% or 332GWh, with Waikato inflows at the 2nd percentile vs the 71st percentile a year earlier
Kaiwera Downs Stage 2 is now at full generation, with the NZ$486m project adding 155MW from 36 turbines. All 12 turbines are installed at Kaiwaikawe
FY27 capex of about NZ$150m stay-in-business and NZ$300m to NZ$400m growth
FY27 EBITDAF guidance reaffirmed, with Mercury on track based on its current outlook
Company page: Mercury NZ (MCY)
Fed’s Williams backs one more hike, sees no need for more in 2027
[9:02 am] New York Fed President John Williams said he still expects one more rate hike this year but sees no reason for further tightening in 2027, pulling Treasury yields lower ahead of Wednesday’s CPI print.
One more hike “I haven’t changed my view that it may be appropriate to have one more rate hike,” Williams said, after the Fed lifted rates to 3.75% to 4.00% in September
Inflation near 2% next year as tariff and energy shocks fade, with Williams adding “this is not an economy that is overheating overall”
Near neutral Williams pegs the real neutral rate at 1% “or a little above,” saying “we’re not that far from neutral”
Market pricing with futures implying a December hike and two more in 2027, while Hammack and Logan see more than one further move needed
Waller on yields saying the surge in long-term yields is curbing housing and auto demand and “doing a little bit of the work”
AI inflation Waller warned the AI build-out is bidding up semiconductor prices, with pressures that could last two or three years
Fund managers want 5.9% Treasury yields before ditching stocks
[9:02 am] Fund managers say 10-year Treasury yields would need to hit 5.9% before they rotate from stocks into bonds, according to BofA’s latest survey.
5.9% threshold vs the 10-year yield of 5.22% on Tuesday
Bond yields top tail risk with 32% citing a disorderly rise in yields, ahead of 23% for an AI bubble
AI bubble split as 45% expect an AI bubble in 2027 and 42% do not
Pullback warnings have emerged on rapidly rising yields, high oil prices, AI risks and weak market breadth
Source: Yahoo Finance
Iran escalates Hormuz attacks as Houthis target Saudi Arabia
[9:01 am] Middle East hostilities are widening, with Iranian attacks on Hormuz shipping and Houthi strikes on Saudi Arabia threatening the recent recovery in Gulf oil exports.
Brent up 0.3% to US$106.30 a barrel
Four tankers hit in the Strait of Hormuz on 11 October, roughly double the prior week’s daily average (UKMTO)
Tankers turning back with more than a dozen supertankers and several Suezmax vessels reversing course near Fujairah
Gulf flows had recovered to about 80% of pre-conflict levels last week according to Shell’s CEO, with Vitol estimating 12m barrels a day of crude exiting Hormuz
Houthi strikes on Riyadh’s main airport killed 13 on Saturday, with the group threatening Aramco’s headquarters and a Riyadh refinery
Trump warns Houthis accusing them of targeting Saudi Arabia to lift oil prices before the 3 November midterms, and said US forces may join the Saudi campaign
Israel weighs Iran strike after Netanyahu and Trump discussed a major new operation before the Israeli and US elections, citing signs Iran is rebuilding its nuclear programme
IMF lifts 2026 global growth forecast but warns of split outlook
[9:00 am] The IMF nudged its 2026 global growth forecast higher on advanced economy resilience, but warned energy importers outside the AI boom remain exposed to the war-driven price shock.
Growth upgraded by 0.1 percentage points to 3.1% in 2026, down from 3.5% in 2025
Bifurcated outlook with AI investment buoying advanced economies while poorer energy importers face stark choices
Fuel prices with refined petroleum products still 70% to 95% above pre-war levels
Downside risks “The global economy has been resilient, but that resilience is under strain, with risks tilted to the downside,” said chief economist Silvana Tenreyro
Complacency warning from Managing Director Kristalina Georgieva, as the IMF urged governments to rein in spending given elevated debt levels
Nvidia pledges another US$2bn for European AI push
[8:59 am] Nvidia CEO Jensen Huang announced US$2bn in new European investments during a tour that included a meeting with French President Emmanuel Macron.
US$2bn pledge on top of the US$8bn Nvidia has invested in Europe over the past year
French startups receiving new funding include Doctolib, Genesis AI, Pigment and Entalpic
Open models pitched as Europe’s path to catch up, with partner Mistral’s latest model trained on 4,000 Grace Blackwell chips
Source: Bloomberg
Beats won’t be enough this AI earnings season
[8:52 am] With Q3 beats now expected, investors will be looking for confidence that AI-driven growth can carry into 2027.
S&P 500 Q3 earnings forecast to surge over 30%, driven largely by AI-related tech (LSEG)
Beats are the status quo after two quarters of big positive surprises, according to BofA strategist Savita Subramanian
Hyperscaler capex from the top five on pace to grow more than 110% year-on-year in Q3
AI dependence “Ultimately, index [EPS] remains highly dependent on the durability of the AI capex cycle and successful monetization,” Subramanian wrote
Valuation with the S&P 500 trading under 19 times forward earnings, its lowest since 2023
Tougher backdrop as rates are expected to rise again, alongside commodity pressure and November midterm uncertainty
Source: Yahoo Finance
Kospi sinks 5.5% as chip rout deepens on CXMT and AI worries
[8:52 am] A global chip sell-off deepened on Tuesday, with Korea’s memory giants hit hardest after China’s CXMT flagged progress on a new memory architecture.
Kospi down 5.5% at the close after falling more than 7% intraday, triggering the first program trading halt since August
SK Hynix and Samsung fell about 10% and 7% respectively, with Samsung’s record earnings last week failing to support the stock
CXMT plans to launch a higher-density server memory product by the end of 2026, using an architecture Samsung and SK Hynix are also developing
Foreign selling hit US$3.4bn, the most since June, leaving the Kospi down a third from its June record and below its 200-day moving average
Broadcom CEO warning Hock Tan said financing may be a bigger problem than chip shortages, adding “a lot of investors have no clue what they are investing in”
Regional spillover with Taiwan’s Taiex and Japan’s Nikkei down nearly 2%, and TSMC off 2% ahead of results from TSMC and ASML this week
JPMorgan dips on rare profit miss as fixed income disappoints
[8:50 am] JPMorgan posted a rare earnings miss as fixed income trading fell well short of ests, with shares closing 0.9% lower, down from session highs of 3.0%.
Managed NII up 13% to US$27.1bn vs US$26.84bn ests (1% beat)
Fixed income markets revenue of US$5.4bn vs US$5.89bn ests (8% miss)
Equity markets revenue up 49% to US$5.0bn vs US$4.5bn ests (11% beat)
IB fees up 14% to US$3.0bn vs US$3.08bn ests (3% miss)
Adjusted EPS of US$5.75 vs US$5.90 ests (3% miss), excluding US$658m in securities losses
Dimon on the economy “Large fiscal deficits, sticky inflation, elevated asset prices, rising interest rates and geopolitical conditions continue to shift under the surface”
Deals delayed, not cancelled CFO Jeremy Barnum said dealmaking slowed in late September but “fundamentally, the pipeline is robust”
Goldman Sachs crushes ests as equities revenue surges 72%
[8:50 am] Goldman Sachs delivered a big beat on the back of its equities desk, more than offsetting a miss in fixed income trading. The stock rallied as much as 4.1% in early trade but finished down 0.2%.
Revenue up 23% to US$18.68bn vs US$16.71bn ests (12% beat)
Equities revenue up 72% to US$6.44bn vs US$4.96bn ests (30% beat)
FICC revenue flat at US$3.47bn vs US$3.72bn ests (7% miss)
IB fees up 21% to US$3.22bn vs US$2.76bn ests (17% beat), though the backlog fell from the end of Q2
EPS up 39% to US$17.01 vs US$13.02 ests (31% beat), including a roughly US$3.20 boost from a one-off tax benefit
ROE of 18.7% vs 14.5% ests
No succession underway CEO David Solomon said “there is no succession transition or timeline underway at Goldman Sachs” after reports the board discussed a handover as soon as end-2027
Citi dips despite best third-quarter revenue in a decade
[8:49 am] Citigroup topped profit ests with its best third-quarter revenue in a decade, but shares tumbled 5.6% to a fresh four-month low.
Revenue up 8% to US$23.8bn vs US$23.72bn ests (in line)
Services revenue up 15% to US$6.6bn
Fixed income markets revenue up 4% to US$4.4bn vs US$4.34bn ests (1% beat)
Adjusted EPS up 27% to US$2.85 vs US$2.66 ests (7% beat)
US card spending up 11% with net charge-offs improving to 3.6% from 4.0%
US$4.1bn returned to shareholders, an 85% payout ratio
J&J slides 6% as medtech misses for a second quarter
[8:49 am] Johnson & Johnson beat on earnings and nudged up guidance, but shares fell 5.7% as its MedTech division missed ests for a second straight quarter.
Revenue up 5.9% to US$25.4bn vs US$25.28bn ests (in line)
Innovative Medicine sales up 7.7% to US$16.76bn vs US$16.59bn ests (1% beat)
Tremfya sales up 68% to US$2.4bn vs US$2.24bn ests (7% beat), replacing lost Stelara revenue as generics bite
MedTech sales up 2.5% to US$8.64bn vs US$8.77bn ests (1% miss), with international sales flat
Adjusted EPS down 7.5% to US$2.59 vs US$2.54 ests (2% beat)
FY26 adjusted EPS guidance raised to US$11.05 to US$11.15, with the US$11.10 midpoint in line with ests
Gulf demand hit CFO Joe Wolk said Middle East customers’ “budgets now are being resourced and allocated towards defense”
DePuy Synthes spin on track for mid-2027, with J&J now leaning towards a spin-off over a sale
Wall St flat as chip sell-off extends and bank earnings kick off
[8:48 am] US stocks bounced off session lows to finish mixed, as dovish Fed commentary offset a fifth straight decline in chipmakers.
Chip index down a fifth session with the PHLX semiconductor index off more than 8% over that stretch, though still up over 70% year-to-date. Micron and Applied Materials both fell sharply
Banks lower as the KBW Nasdaq Bank index fell 1.1%, with Wells Fargo down after its net interest income missed ests
Narrow breadth with the S&P 500 up about 14% in 2026, but the median stock up less than 5% and over 200 constituents down for the year
Good morning!
[8:30 am] ASX 200 futures are down 30 pts (-0.34%). Here's what happened overnight:
Wall Street drifted lower as a deepening chip rout offset the start of earnings season, with stocks finishing off their worst levels
S&P 500 (-0.02%), Nasdaq (-0.15%), Dow (-0.35%), Russell 2000 (-0.40%)
Megacap tech held up well, including Meta (+2.6%), Nvidia (+0.9%), Microsoft (+0.4%)
Chip names mixed, with Applied Materials (-6.6%), SpaceX (-4.2%), Micron (-3.6%) lower, but AMD (+1.9%) bucking the trend
Big banks kicked off earnings season on a mixed note, Goldman’s trading blowout contrasting with a rare JPMorgan miss and Dimon’s warning on sticky inflation and rising rates
The AI trade is cracking, memory chipmakers slumped worldwide on a Chinese breakthrough claim, dragging Korea's Kospi sharply lower
Fed hike path in focus, NY Fed's Williams backed one more hike this year but none in 2027, ahead of Wednesday's US CPI