ASX 200 Live Today - Wednesday, 4th November
The ASX 200 is trading lower as healthcare extends its pullback, retailers give back Tuesday’s gains and defensives are back in focus.
Today’s ASX 200 Updates
Welcome to our live ASX coverage for Wednesday, November 4. Expect a high volume of posts pre-market and more periodic updates throughout the day. We'll be wrapping the blog up around 2:30 pm AEDT, after the RBA decision. Let us know how we can make it even better.
ASX turns defensive as Utilities and Staples shine
[1:14 pm] The ASX is turning defensive, with Utilities, Energy and Staples outperforming every other sector by a sizeable margin. Materials, meanwhile, has flipped from a 0.2% gain in early trade to a 1.1% loss. The prospect of a Democratic sweep is stirring market jitters, with investors wary of tighter regulation, particularly stricter rules around data centres and AI.
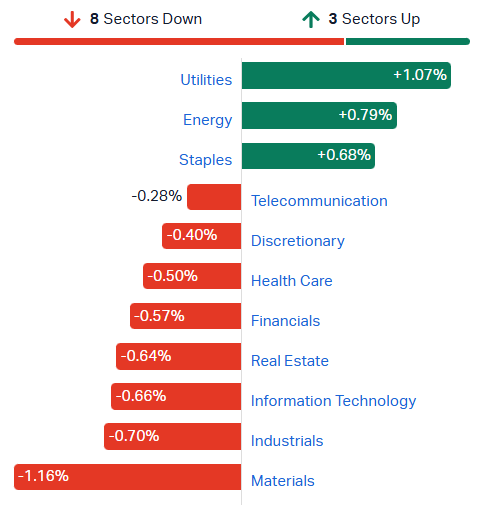
S&P/ASX 200 sectors (Source: Market Index)
US futures and dollar slide as markets price a Democratic sweep
[1:10 pm] US stock futures and the dollar fell while Treasuries rallied as early midterm results pointed to Democrats taking both houses of Congress, raising the prospect of tighter regulation for tech and AI companies.
S&P 500 futures down 0.73%, Nasdaq futures down 1.57%
US 2-year yield down 6 bps to 4.57% and US 10-year down 6 bps to 4.90%, the lowest since 10 September
KOSPI down 1.0%, fading a 3.1% gain in early trade
Copper down 1.2% to US$6.40/lb, despite holding flat in early trade
Kalshi is pricing a 99% chance of Democrats winning the House and a similar probability for the Senate
Household spending rebounds 0.6% as fuel costs bite
[12:59 pm] Australian household spending returned to growth in September, though higher fuel prices did much of the heavy lifting as fuel volumes fell.
Household spending rose 0.6% in September, after falling 0.1% in August and rising 1.0% in July
Fuel spending jumped 5.4% on higher global oil prices and the end of fuel excise relief on 3-Aug, while experimental ABS data shows fuel volumes fell 2.2%
Transport and health spending both rose 1.5%, with late flu activity driving more GP visits and medicine purchases
Recreation and culture rose 0.8% on live entertainment, electronics and gambling around major sporting events
September quarter spending volumes rose 0.7%, a fourth straight quarter of growth, led by a 1.6% rise in transport
Source: ABS
Small caps hold firm as banks drag
[12:31 pm] Small caps are holding up relatively well, with the Emerging Companies Index up 0.46% and Small Ordinaries flat, while the blue-chip ASX 20 is down 0.56% and ASX 200 Banks falling 0.97%.
Perhaps some relative outperformance or mean reversion for small caps, but zooming to a year-to-date chart, the ASX 20 (green) has outperformed by a wide margin, while the small/speculative end has tanked ~15% YTD.
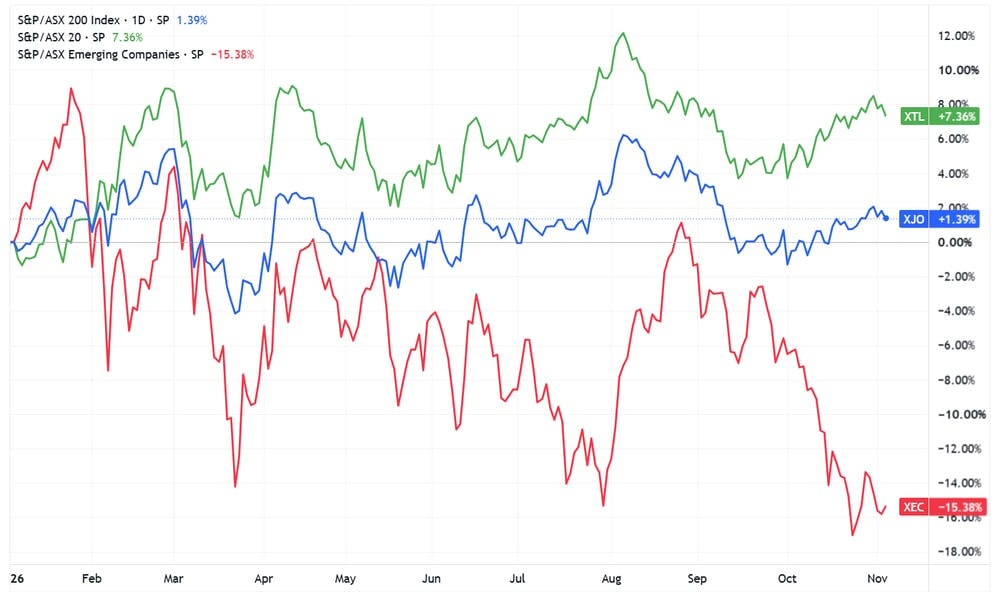
S&P/ASX 20 (green), ASX 200 (blue) and ASX Emerging Companies Index (red) | Source: TradingView
US futures slide as Democrats gain early momentum in midterms
[12:27 pm] US stock futures extended losses as early vote counts pointed to a strong Democratic showing, raising concerns over tighter regulation of sectors that have powered Wall Street’s bull market.
S&P 500 futures fell 0.6% and Nasdaq 100 futures lost 1.2%
Decision Desk HQ projects Democratic incumbents Jon Ossoff and Cory Booker will hold their Senate seats in Georgia and New Jersey
Kalshi odds of Democrats taking both houses jumped to 86% from about 72% a few hours earlier
Saxo’s Charu Chanana says the market appears to be pricing a potential Democratic sweep, which KCM Trade’s Tim Waterer sees as the least desirable outcome for tech and risk assets
Large caps have gained about 15% in the six months after midterms since 1982 and roughly 22% over the following year, according to Morgan Stanley
Source: Bloomberg
Canva overhaul hits 22% of staff as AI forces reset
[12:26 pm] Canva has announced job cuts and a restructure affecting more than one-fifth of its workforce, with CEO Melanie Perkins calling it the hardest moment in the company’s 13-year history.
Some 1,271 staff, or 22% of the workforce, will lose their jobs, change roles or relocate to central hubs, Perkins told employees
Perkins didn’t specify how many roles will go, but said Canva needs to become a simpler business with small teams and fewer niche specialisations
Sydney will become the main base for more product teams, with most hybrid staff to spend two to three days a week in the office from January
The overhaul comes as Canva prepares for a potential listing, after its growth slowed for the first time in a decade
Software stocks have shed billions in value on concerns AI tools such as Anthropic’s Claude will cannibalise their businesses
Source: Bloomberg
Citi shrugs off Brazil car sales dip for CAR Group, UBS sees IAG upside
[11:35 am] Brokers are sticking with their calls on CAR Group, Goodman, Dicker Data and IAG after a round of company and industry updates.
CAR Group bull Siraj Ahmed at Citi isn’t overly troubled by a 9% year-on-year fall in Brazil’s October used-vehicle sales, noting the data includes commercial vehicles its local subsidiary isn’t exposed to. Citi is Buy-rated with a $33.30 target
Goodman’s 1Q update is a clear step forward in de-risking its data centre pipeline, says Citi’s Howard Penny, with Hong Kong’s HKG10, Los Angeles’ LAX02 and Amsterdam’s AMS01 the near-term watchpoints. Citi is Buy-rated with a $40 target
Dicker Data’s acquisition of NZ-based Sektor could be 9% EPS accretive in its first full year of ownership, says UBS’s Damen Kloeckner. UBS is Neutral-rated with a target lifted to $15.90 from $15.41
IAG’s acquisition of RAC’s WA insurance business looks more likely to win ACCC approval after concessions, says UBS’s Kieren Chidgey, adding upside earnings risk. UBS is Buy-rated with a $9.10 target
Company pages: CAR Group (CAR), Goodman Group (GMG), Dicker Data (DDR), Insurance Australia Group (IAG)
Polls close in key Senate states as Democrats eye Congress
[11:32 am] Polls have started closing in the US midterm elections, with Democrats favoured to win the House while control of the Senate remains harder to call.
Polls have closed in North Carolina, Ohio and Georgia, all states with critical Senate races
Democratic Senator Jon Ossoff is projected to hold his Georgia seat, according to Decision Desk HQ
Democrats need a net gain of three seats to take the House, with the Cook Political Report projecting a gain of 15 to 25, and must flip four Republican-held seats to win the Senate
Final results could take weeks given state rules on counting mail-in votes and longer tabulation where ranked-choice ballots are used
Trump told CBS News he would veto Democratic legislation if they win either chamber, while government funding and lifting the debt ceiling would require both sides to work together
Source: Bloomberg
Ai Group manufacturing index slumps as fuel costs squeeze margins
[11:11 am] Australian manufacturers are bearing the brunt of higher fuel prices flowing through supply chains, with weak demand leaving them unable to fully pass on rising costs, according to the Australian Industry Group.
The Australian Industry Index rose 6.4 points to -19.1 in October, with readings below zero signalling contraction
Ai Group’s manufacturing PMI fell 13.4 points to -20.1, reversing September’s gains
The input price index rose to 69.3, its highest in a year, while the sales price index edged up to 15.4, leaving a 53.9-point gap
New orders rose 12.8 points to -22.0, though they have been very weak in trend terms since the energy crisis began at Easter
Input costs were the biggest drag, cited by 29% of businesses, while demand impacts jumped to 20% from 8% in September
Source: Ai Group
Australian services activity contracts for the first time since May
[11:10 am] Australia’s services sector slipped into contraction in October as higher interest rates and capacity constraints weighed on activity, joining manufacturing in decline.
The services PMI fell to 48.5 from 51.9 in September, its first sub-50 reading since May and lowest in seven months
The composite PMI fell to 48.2 from 51.3, with the downturn broad-based across services and manufacturing
New business growth slowed to the weakest of its four-month expansion, with firms citing higher interest rates and weak confidence, though foreign demand picked up on tourism
Employment returned to growth after job cuts at the end of the September quarter, as backlogs rose at the fastest rate since May 2022
Input cost inflation hit a five-month high on fuel, freight and labour costs, while output prices rose at the fastest pace in three months and above the long-run average
Source: S&P Global
Top ASX 200 gainers
[10:24 am] Block rallies after the company upgraded its 2026 guidance, while battered uranium, rare earths, lithium and data centre stocks continue to bounce.
Ticker | Company | % Chg | Price | 1 Week | YTD |
|---|---|---|---|---|---|
XYZ | Block | 6.9% | $117.27 | 10.6% | 20.9% |
MP1 | Megaport | 4.7% | $17.71 | -1.8% | 56.1% |
DYL | Deep Yellow | 3.6% | $0.72 | -7.1% | -60.9% |
TLX | Telix Pharmaceuticals | 3.5% | $13.46 | 2.7% | 19.6% |
IPX | Iperionx | 3.3% | $2.20 | 6.8% | -60.1% |
LYC | Lynas Rare Earths | 3.0% | $12.33 | 2.3% | -0.6% |
VUL | Vulcan Energy Resources | 2.8% | $1.09 | -11.1% | -75.4% |
NXT | NextDC | 2.6% | $6.43 | 7.2% | -47.8% |
WTC | Wisetech Global | 2.2% | $42.73 | 6.6% | -37.6% |
AMP | AMP | 2.1% | $2.18 | -11.2% | 19.8% |
Top ASX 200 losers
[10:24 am] Healthcare/biotech and airlines slip, while the likes of Champion Iron and 4DMedical continue to spiral lower.
Ticker | Company | % Chg | Price | 1 Week | YTD |
|---|---|---|---|---|---|
4DX | 4DMedical | -3.3% | $2.33 | -37.9% | -41.8% |
MSB | Mesoblast | -2.5% | $2.11 | 12.0% | -22.9% |
QAN | Qantas Airways | -2.5% | $9.13 | 4.7% | -12.2% |
PNI | Pinnacle Investment Management | -2.3% | $15.81 | 9.6% | -7.3% |
NEC | Nine Entertainment Co | -2.1% | $0.70 | 4.5% | -37.4% |
SHL | Sonic Healthcare | -2.0% | $19.18 | 0.4% | -15.2% |
AMC | Amcor | -2.0% | $67.26 | 3.2% | 7.5% |
A2M | A2 Milk Company | -1.9% | $6.90 | 0.2% | -25.1% |
CIA | Champion Iron | -1.9% | $1.82 | -20.2% | -70.0% |
NEU | Neuren Pharmaceuticals | -1.9% | $20.28 | 6.8% | 8.9% |
Worley lands CP2 Expansion contract, CLW extends government leases
[10:16 am] Here are a few announcements we missed this morning, all of which were marked as non-price sensitive.
Worley signed a reimbursable EPC contract for Venture Global’s CP2 Expansion LNG project in Louisiana, where it already delivers Phases 1 and 2, with a final investment decision targeted for early 2027
Charter Hall Long WALE REIT extended its Defence lease in Canberra and ATO leases in Albury and Adelaide, lifting its WALE to 9.4 years from 9.2 years, though the ATO will vacate the Adelaide building in April 2029, and reaffirmed FY27 operating EPS and distribution guidance of 25.5c
Catalyst Metals appointed former Develop Global CFO Ben MacKinnon as CFO and former Northern Star Yandal operations head Rob Williamson as COO, with both joining before year end
Company pages: Worley (WOR), Charter Hall Long WALE REIT (CLW), Catalyst Metals (CYL)
Scentre quantifies David Jones exposure, reaffirms 2026 FFO target
[10:05] Scentre Group says David Jones accounts for about 3.6% of its funds from operations, after media reports about the department store chain and its owner Anchorage Capital Partners.
Occupancy of 99.8% is its highest in more than a decade, with specialty rent escalations of 5.6% and releasing spreads of 3.7%
Business partner sales up 3.5% in the September quarter, with specialty store sales up 4.6%
David Jones gross rent of $45m in 2026 is about 1.8% of group gross rent, at $352 per sqm vs the portfolio average of $942
Bank guarantees of about $30m (Scentre share) cover around eight months of David Jones rent, with all rent paid up to 30-Sep
Scentre sold a 50% stake in Westfield Mt Gravatt in Brisbane to joint venture partner Australian Retirement Trust for $882.5m
2026 FFO target reaffirmed at a minimum of 23.79c, implying growth of at least 4.25%, with distributions to rise 4.25% to 18.473c
Company page: Scentre Group (SCG)
Ingenia rebuffs Warburg Pincus bid to regain due diligence access
[10:04] Land lease communities operator Ingenia says an amended proposal from Warburg Pincus is not superior, leaving the private equity firm locked out of due diligence while property developer AVID’s matched $5.45 offer stands.
AVID matched Warburg’s $5.45 cash per security on 2-Nov, with its offer not reduced by an interim distribution of up to 5c, which the board judged equal or superior
Warburg’s new proposal on 3-Nov keeps the same price but seeks a carve-out letting a rival bidder keep due diligence access for four days after a matching offer
The proposal is conditional on Ingenia reinstating Warburg’s due diligence access, issuing AVID a matching right notice and signing an amended process deed by 6-Nov
The board says it is not a Superior Proposal under the AVID process deed, so Warburg’s due diligence access remains terminated
Company page: Ingenia Communities Group (INA)
Thinking out loud about Goodman Group
[9:53 am] Goodman has a long track record of low-balling its initial annual guidance and upgrading it as the financial year progresses. Analysts often point to this under-promise and over-deliver approach as a hallmark of CEO Greg Goodman’s management style. Many recent years have started with guidance of around 9% before climbing to the low-to-mid teens. UBS and Citi currently forecast FY27 EPS of 147 cents and 143 cents, implying growth of 13.1% and 10.1% respectively. It’s only the first quarter update, but it’s worth keeping in mind as the year unfolds, given analysts almost always price in an upgrade ahead of time.
Dateline and US Government take Colosseum stay bid to Ninth Circuit
[9:34 am] Dateline Resources and the US Government have each asked a US appeals court to let work resume at the Colosseum gold and rare earths project while they appeal the injunction that halted it.
The stay motions were lodged with the US Court of Appeals for the Ninth Circuit after Friday’s District Court decision left the injunction in place, and will be decided afresh by a three-judge panel
The injunction was granted on 10-Aug in proceedings brought by the National Parks Conservation Association, requiring Dateline to halt operations at Colosseum until the injunction is lifted or a final judgment is delivered
The US Government argues it is likely to succeed on appeal and that the injunction irreparably harms national security and the public interest
Dateline maintains its 1985 Plan of Operations is a valid existing right that survived the creation of the Mojave National Preserve, as recognised by the National Park Service in 1995, 2024 and April 2025
Company page: Dateline Resources (DTR)
Goodman targets 9% EPS growth as data centres make up 79% of WIP
[9:20 am] Goodman says demand for data centre capacity continues to outrun supply, with constraints on power, land and planning expected to drive rental growth across its portfolio.
Like-for-like NPI growth of 4%, or 6.2% excluding Greater China, where rent reversion remained negative
Occupancy of 95.5% (96.7% excluding Greater China), with the total portfolio at $90bn and valuations positive in the quarter
Work in progress of $19.7bn across 51 projects, with data centres 79% of the book and a yield on cost of 8.3%
WIP is 31% pre-committed, as data centres are commenced before customer contracts are signed, with advanced talks on full-building hyperscale deals at several sites
Power bank increased to 6.6GW, with 3.6GW secured
FY27 operating EPS growth target of 9%, with a distribution target of 30c per security
Company page: Goodman Group (GMG)
City Chic flags positive 1H EBIT as discount pullback lifts margins
[9:16 am] Plus-size fashion retailer City Chic expects to deliver positive first-half EBIT, provided sales momentum holds through Black Friday and Christmas.
Group sales fell 1.7% excluding wholesale for the 18 weeks to 1-Nov, while gross margin dollars rose 2.2%
Gross margin up 240bps at group level, with comparable gross margin dollars up 5.1% on comparable sales growth of 1.2%
ANZ stores delivered comparable sales growth of 15.4%, with full-price stores up 19.6% and growth in each of the first 18 weeks of FY27
ANZ online comparable sales fell 7.4% as promotions were scaled back, though trading gross margin rose 200bps
USA comparable sales fell 12%, while comparable gross margin dollars rose 7.1% and online trading gross margin jumped 1,060bps
No drawn debt expected at the end of 1H FY27, with a positive cash balance and its $10m facility in place until March 2028
Company page: City Chic Collective (CCX)
Junior wrap: Altoro hits 25.7% zinc in Spain, Titanium Sands lands Chinese backer
[9:15 am] Altoro Metals led the explorers after its first modern drilling at a historical Spanish zinc mine returned high grades well outside its existing resource.
Altoro Metals hit 5m at 13.66% zinc at the historical Emilia Mine in northern Spain, including 1m at 25.7%, with the nine-hole program sitting entirely outside its resource
Titanium Sands raised $500,000 from the Australian arm of Beijing-based Gage Capital at 0.8c a share, a 33% premium, with Gage also taking a first right on capex funding and offtake for its Sri Lankan mineral sands project
Riversgold will acquire Black Cat Syndicate’s E25/594 licence, lifting its Northern Zone gold project area about 15-fold to 12.82 sq km, with Black Cat becoming a shareholder on completion
Gold Mountain returned four rock chips above 10,000ppm tungsten (about 1.26% WO₃) at the historical Malhada do Angico mine in Brazil, with over-limit assays pending
Koonenberry Gold rock chips returned up to 19.05% copper at Breakfast Creek in NSW, where three skarn drill targets have been defined, while maiden drilling at Dunedoo returned only low-grade results
Olympio Metals grab samples returned up to 1,509g/t silver and 16.41% antimony from historical mine dumps at its Raven project in Montana
Company pages: Altoro Metals (ARO), Titanium Sands (TSL), Riversgold (RGL), Gold Mountain (GMN), Koonenberry Gold (KNB), Olympio Metals (OLY)
Block lifts FY26 guidance as Cash App profit beats
[9:02 am] Block raised its full-year profit guidance, though Cash App inflows of $86 billion came in about 4% short of forecasts. NYSE-listed Block shares are currently up 5.8% after hours.
Revenue up 10% to $6.72bn vs $6.59bn ests (2% beat)
Gross profit up 22% to $3.24bn
Cash App gross profit up 27% to $2.07bn vs $1.97bn ests (5% beat)
Adjusted EPS up 109% to $1.13 vs $1.03 ests (10% beat)
FY26 adjusted operating income guidance raised to $3.5bn vs $3.22bn ests (9% beat)
FY27 adjusted operating income outlook of $4.6bn vs $4.25bn ests (8% beat), with gross profit growth of at least 15%
Company page: Block (XYZ)
Super Micro jumps 8% after hours on guidance upgrade
[9:01 am] Super Micro shares rose 8% after hours after the AI server maker lifted its full-year outlook, offering some relief after a 27% slide over the past month on Gartner’s warning that most neocloud companies would fold by 2030.
Revenue up 298% to a record $19.9bn
Adjusted EPS up 417% to $1.81 vs $1.62 ests (12% beat)
Operating cash outflow of $434m for the quarter, with cash and equivalents of $6.9bn
Q2 revenue guidance of $19.5–21.5bn, with the $20.5bn midpoint 17% above ests of $17.5bn
FY27 revenue guidance raised to $72–82bn, with the $77bn midpoint 11% above ests of $69.2bn
Goldman says 60% of the S&P 500 is in a bear market
[8:56 am] The S&P 500 is within about 3% of its record high, yet Goldman Sachs trader Bobby Molavi says 60% of its members are in bear market territory as investors turn on AI spending.
The Magnificent Seven have shed $4tn in market value since 15-Oct, with Molavi saying it’s the first time he can remember earnings not being good enough
Cloud demand remains strong, with Google Cloud revenue doubling, Azure up 48% and AWS up 39%, its fastest growth in five years
The four biggest hyperscalers generated $26bn of combined free cash flow, a fraction of past levels, and are leaning more on debt and equity to fund AI
Amazon’s long-term debt has climbed to $173bn from $66bn in nine months
The Philadelphia Semiconductor Index fell 7% on Friday, with forward multiples back at AI-cycle lows of around 16 times
The spread between B and CCC-rated bonds hit 8%, a level reached fewer than five times since 1996, each time with the S&P 500 at least 11.5% below its 52-week high
Source: Bloomberg
AllianceBernstein urges investors to diversify beyond AI
[8:56 am] AllianceBernstein head of equities Nelson Yu is telling clients to build portfolios less reliant on tech megacaps as doubts grow over returns on AI spending.
Yu favours defence, healthcare and international equities, along with small caps and value stocks
The S&P 500 Health Care Index has gained almost 10% since the Nasdaq 100 peaked on 6-Oct, while the Nasdaq 100 has fallen 9.5%
Yu says healthcare offers exposure to AI through pharma and biotech names, while traditionally holding up when growth stocks sell off
Japan, Europe and Latin America stand out internationally, on governance reforms, quality industrials and consumer growth respectively
The Russell 2000 is flat since 6-Oct while the S&P 500 is down almost 3%, with small caps showing signs of stabilising
Source: Bloomberg
UBS eyes year-end squeeze once midterms are cleared
[8:55 am] UBS says the midterm elections could be the last hurdle before a year-end rally, with history suggesting the result shapes stocks for a few months at most.
The S&P 500 has returned an average 1.9% in November since 1950, its strongest month, and UBS says low hedge fund net exposure could amplify a rally
A decisive Democratic sweep could weigh on financials and data centre names, with UBS recommending November puts on the XLF financials ETF after the sector rallied about 6% in October
UBS sees opportunity in renewables, where positioning is near a one-year low and a Democratic win could act as a catalyst
Prediction market Polymarket gave Democrats a 76% chance of winning both chambers on Tuesday morning, with a Democratic House and Republican Senate at 19%
After the seven midterms that handed Democrats Congress under a Republican president, the S&P 500 rose an average 11% over three months and was higher every time
The S&P 500 was higher a year after all 20 midterms since 1946, averaging about 14%, though it sank nearly 15% by Christmas Eve after the 2018 vote
Source: Bloomberg
CrowdStrike rises on AI kill switch and $495m startup deals
[8:54 am] CrowdStrike shares rose 1.2% after the cybersecurity company launched a kill switch for rogue AI agents and agreed to buy two AI security startups for a combined $495 million.
The kill switch sits in Falcon Guardian, letting security teams terminate an AI agent that strays from its intended behaviour, block it from relaunching and cut its network access
CrowdStrike will acquire Fiddler AI, which builds tools to help companies monitor their AI systems
Dreadnode tests AI systems for security vulnerabilities, and will let Falcon continuously scan AI models, apps and agents before deployment
Cybersecurity names have benefited from agentic AI driving demand for verification and authentication, despite early-year fears AI would disrupt their business models
Source: Yahoo Finance
Trump says US close to trade deal with Canada
[8:53 am] President Donald Trump says the US is close to striking a trade deal with Canada after months of tit-for-tat tariffs.
Trump told Fox News a deal with Canada would come very soon
Trump and Prime Minister Mark Carney said on Sunday they had discussed a deal, which Trump said would be great for US farmers
Carney said both teams would work over the coming weeks to deliver the outcome
Tariffs on Canada have become an issue in northern border states such as Michigan and Maine ahead of the midterms
Source: Reuters
Oil flat as US and Iran weigh peace proposals
[8:53 am] Oil whipsawed as Washington and Tehran reviewed fresh proposals from Qatari mediators, even as limited US strikes kept escalation risks alive.
Brent swung in a more than $6 range during the session, pushing some oil volatility gauges to their highest since late July
Qatari mediators held talks in Tehran and expect feedback from both sides within two days, with a diplomat describing the talks as positive
Iran’s national security chief said the US response to its demands had so far been unsatisfactory, which helped futures pare losses
The US struck targets on Iran’s Qeshm Island in the Strait of Hormuz, with Trump calling it a minor attack and Energy Secretary Chris Wright saying Hormuz flows were unaffected
Tehran wants the US naval blockade lifted, sanctions eased and frozen assets released, while Washington is demanding nuclear concessions
Exports from Saudi Arabia, the UAE, Iraq and Kuwait rose 10% to more than 15m barrels a day in October, and Dubai’s nearest timespread has flipped into contango
Treasury yields climb as job openings top forecasts
[8:50 am] A volatile session for bond yields, which finished broadly higher but off session highs.
The 10-year Treasury yield rose 5 bps to 4.96% (down from a 12 bp spike to 5.03%), while Germany’s 10-year added 4 bps to 3.33% and the UK’s climbed 7 bps to 5.26%
US job openings rose to 7.5m in September from a revised 7.2m in August vs 7.1m ests
Quits rose to 3.4m vs 3.09m ests, while layoffs held at 1.6m and the hiring rate edged up to 3.4% from 3.3% in August
The Bloomberg Dollar Spot Index rose 0.3%, sitting near the year high it hit in October as hot inflation data fuelled bets on further Fed tightening
AMD jumps 9% after hours as Q4 guidance tops ests
[8:49 am] AMD shares rose about 9% in after-hours trade as Anthropic, Meta, Microsoft, OpenAI and Oracle began running workloads on the chipmaker’s first Helios AI racks.
Revenue up 45% to $13.40bn vs $13.09bn ests (2% beat)
Data centre revenue up 97% to a record $8.55bn vs $8.27bn ests (3% beat)
Adjusted EPS up 74% to $2.09 vs $1.95 ests (7% beat)
Free cash flow down 64% to $554m vs $1.05bn ests (47% miss)
Q4 revenue guidance of $16.5–17.5bn, with the $17bn midpoint 5% above ests of $16.23bn, as CEO Lisa Su expects growth to accelerate further as Helios and Venice production scales
A $1.1bn non-cash charge tied to the OpenAI and Meta deals cut GAAP EPS by $0.66, with both customers holding warrants over up to 320m AMD shares at $0.01 each
Chip rebound lifts Nasdaq as Dow slips on US election day
[8:48 am] The Nasdaq rose 0.8% as chipmakers bounced back from a fresh bear market, though most S&P 500 members finished lower as Americans headed to the polls.
The S&P 500 rose 0.4% to 7,568, the Nasdaq gained 0.8% and the Dow fell 0.4%
The PHLX Semiconductor Index rose 2.6% after Monday’s close left it about 22% below its 6-Oct high, its second bear market since June
Chip stocks have climbed in all eight midterm cycles since 1994, measured from the October close to the following June, though they first fell another 11% in 2002 and 2018
Apple fell after warning memory costs will keep rising, while Palantir dropped as much as 7.3% on an outlook pointing to slower sales growth despite beating ests
Shopify dipped 8.0% after Q3 revenue of $3.74bn missed ests for the first time since 2022, with subscription revenue of $836m vs $850m ests (2% miss)
Good morning!
[8:30 am] ASX 200 futures are down 34 pts (-0.38%). Here's what happened overnight:
Chipmakers led a tech rebound that lifted the S&P 500 and Nasdaq as Americans voted in the midterms, even as Apple and most S&P 500 members lagged
S&P 500 (+0.36%), Equal-weight S&P 500 (-0.33%)
Nasdaq (+0.83%), Dow (-0.38%), Russell 2000 (+0.23%)
Oil whipsawed as the US and Iran weighed fresh mediator proposals, although Tehran said it would not accept diplomacy based on coercion. Brent settled flat at US$104.5 a barrel, but whipsawed between US$107.2 and US$100.8
Meta drew up to US$58bn of orders for a US$15bn US dollar bond sale, a fresh test of investor appetite for Big Tech's AI debt