Everything you need to know about the Anthropic IPO
The highly anticipated Anthropic IPO filing is here, so get your popcorn out and settle in for a wild read (and 100 pages on risk factors).
Source: Gemini
KEY POINTS
- Anthropic has lodged its S-1 and proposes to list on the Nasdaq as ANT in mid-November. Reports point to a US$2 trillion valuation and a SpaceX-sized raise.
- It’s growing faster than almost any company before it, with first-half revenue up about 1,300% to US$16.2 billion, though that pace is expected to slow.
- The catch is most revenue depends on usage, while roughly US$550 billion in compute commitments are locked in. Growth has to stay very strong to cover them.
Anthropic filed for its long-awaited IPO on Monday, a landmark moment that'll test how much public investors are willing to pay for AI growth that's very real, but enormously expensive to sustain.
The filing has shed light on just about every corner of the business, across more than 300 pages, nearly 100 of them on risk factors alone. Here’s what investors need to know.
Anthropic IPO in a nutshell
All figures in this article are in US dollars.
Ticker: ANT, Class A common stock on the Nasdaq
Price range and share count: Not yet set. The offer price range, share numbers and underwriting discount are all blank in the S-1
Valuation: Not yet set. Anthropic raised $65 billion at a $965 billion valuation in May. Reports suggest the IPO could value the company at around $2 trillion
Raise size: Not disclosed. Bloomberg reported Anthropic expects to raise as much as or more than SpaceX did. SpaceX raised $75 billion in June, pricing 555.6 million shares at $135 each
Timing: Marketing to investors could start as soon as the week of 9 November, according to Bloomberg. The Wall Street Journal reported the listing is set for the week of 16 November
Underwriters: Goldman Sachs and Morgan Stanley lead a 22-bank syndicate that includes JPMorgan, Citigroup, UBS, Jefferies and Macquarie Capital
Australian investors: The offering includes a public offer in Australia, as well as Canada, Europe, Japan, Switzerland and the UK
Revenue at a glance
First-half revenue hit $16.2 billion, up about 1,300% year-on-year, with sales more than doubling quarter-on-quarter in both Q1 and Q2. The S-1 doesn’t explicitly spell out numbers for Q3, but says revenue was 86 times the $197 million booked in Q4 2024, which works out to roughly $16.9 billion.
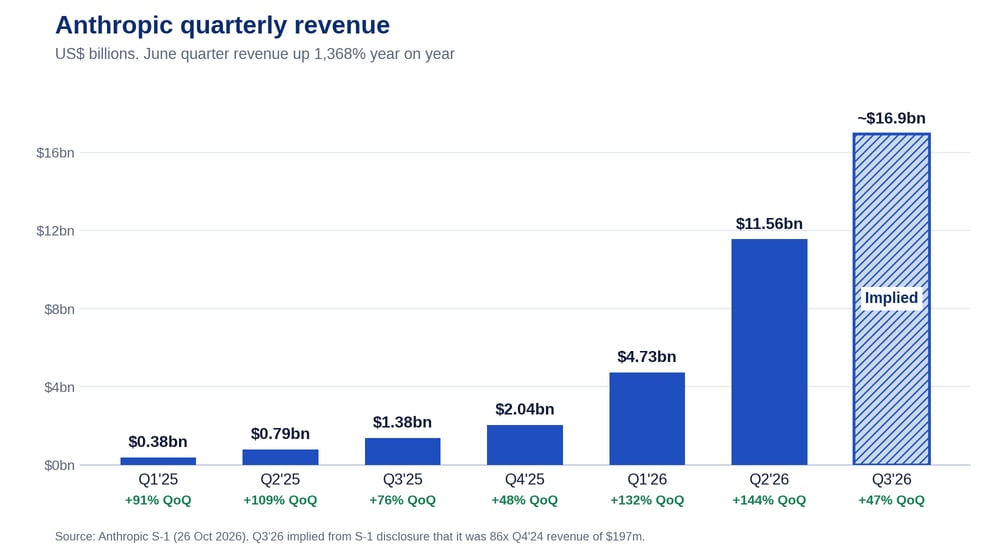
These astronomical growth rates are expected to decelerate, with the prospectus flagging a number of risks.
Little is locked in. About 80% of revenue is consumption-based, and contracted revenue covers less than 20% of the year ahead
New models do the heavy lifting. More than 80% of Q3 revenue came from models released in the prior six months
Price cuts. Claude Opus 5.5 cut customer cost per task by about 40%. Anthropic argues cheaper tasks drive more usage, but each cut also lowers what it earns per task
Compute supply. Demand for compute has historically exceeded available capacity, and Anthropic has in the past sought more compute from cloud providers than they were willing to provide
Who’s paying
Net revenue retention is about 900%, excluding the Pro and Max consumer plans. That means customers who were paying Anthropic a year ago spent roughly nine times as much in the September quarter.
The customer base by annual spend:
More than 11,900 customers spend over $100k a year
More than 1,900 spend over $1m
About 250 spend over $10m
No single consumer accounted for more than 10% of year-to-September revenues, though the top five made up about 25%. This is down from 36% in Q1 and 21% in Q3, so moving in the right direction, but still very concentrated.
Interestingly, Claude Enterprise users who don’t use Claude Code spend less than $75 a month on average, while the top 5% who do spend roughly 20 times as much. Claude Cowork, which extends Claude Code’s agent setup to general knowledge work, is being adopted faster than Claude Code was at the same point after launch.
The path to profit
On a GAAP basis, Anthropic is still deep in the red, with a net loss of $80.7 billion in the first half of 2026. Though almost all of that is financing-instrument noise, including a $72.4 billion change in the fair value of convertible notes and derivatives, plus $8.8 billion of other mark-to-market items.
In laymans terms, investors who lent Anthropic capital via convertible notes are repaid in shares. So every time the company's valuation jumps, the notes are worth more to the holders, and the increase in liability runs through the income statement as a loss.
On an operating basis, Anthropic has cut compute costs as a share of revenue sharply, which has narrowed losses and pushed the business into profit. Each $1 of compute and infrastructure cost now brings in $2.08, compared to just 40 cents in the first quarter of 2025. The June quarter marked the company's first positive GAAP operating income of $974 million, an 8.4% margin.
The ~$500 billion compute bill
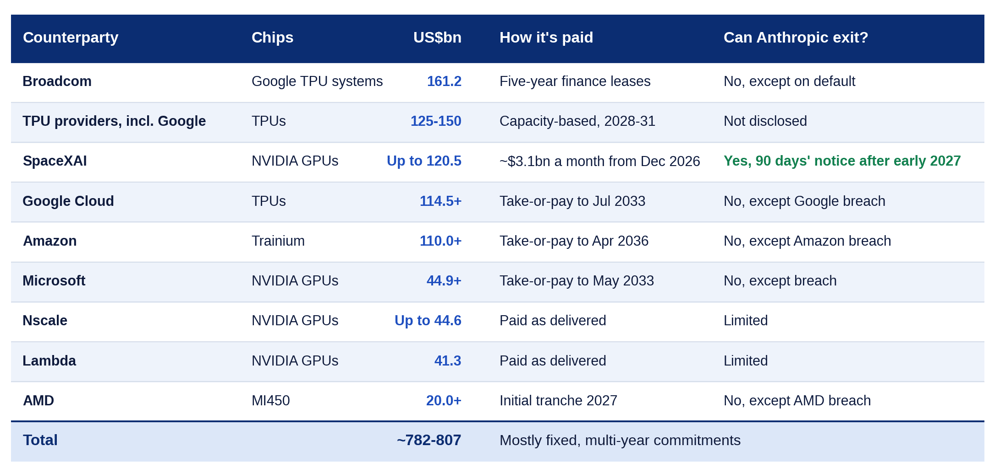
As of 31 December 2025, Anthropic had signed $417 billion in compute leases and minimum purchase commitments, plus a further $125 billion to $150 billion in additional capacity slated between 2028 and 2031. That's some $550 billion in future infrastructure obligations that have not yet been built or accounted for on the company's current balance sheet.
Some of the major deals include:
Source: Anthropic S1 (Oct-26) + denotes a minimum commitment
The SpaceXAI deal alone runs to about $3.1 billion a month once all capacity is delivered, which is expected in December. That’s roughly $37 billion a year, or about 80% of June-quarter annualised revenue. This is where things get a little sweaty as revenue is variable and driven by usage, while compute costs are fixed and mostly take-or-pay.
If this sounds risky, don’t worry. Anthropic agrees. Risk factors run for almost 100 of the 261 pages of the prospectus (compared to just ~50 used to describe the business itself). There's plenty of existential and fear-mongering scenarios as to how things could go wrong, including:
Suppliers that compete. Amazon, Google and Microsoft are investors, compute suppliers and customers at once. The S-1 flags that some of the cloud providers it relies on offer their own AI models, so their commercial interests may not always line up with Anthropic’s.
Models acting on their own. A dedicated risk factor warns its models may behave in unintended, misaligned or autonomous ways, including taking harmful actions nobody directed.
Political exposure. The S-1 says its safety advocacy could make it a target of selective government action. It cites the Department of War floating the Defense Production Act and the June export restrictions on Fable 5 and Mythos 5.
The most intriguing risk lands on page 50: "In addition, with the scale of harm that could result from a catastrophic AI-related incident, no single insurer, and potentially the insurance industry in the aggregate, may have sufficient capacity or expertise to underwrite insurance commensurate with such exposure."
Paying suppliers in shares
Anthropic’s suppliers are also some of its financiers, and a large part of that financing is settled in stock. This includes deals with:
Broadcom: up to $42bn of convertible notes, usable only to pay quarterly rent on the 2026 lease. They carry 9% interest paid in kind and convert at a 10% discount. If Anthropic misses certain revenue targets, the interest rises to 13% and the discount to 15%.
Google: a $20bn facility in notes or Class N stock, available through 2030. Google also has an option to buy up to $10bn of non-voting stock at the IPO price, which would shrink the facility by the same amount.
Amazon: bought $5bn of preferred shares in April, with $15bn more available in $5bn steps as compute milestones are hit, settled in Class N stock.
AMD: will buy up to $5bn of Class N stock as GPU delivery milestones are met, with purchases after the IPO priced at the 30-day average.
The supplier notes settle at a trailing volume-weighted price, so a lower share price means more shares (or dilution) for the same dollar amount.
Lock-ups drip-feed supply
Some shares held by non-founder directors, officers and employees can be sold from the first trading day, with more unlocking on days 27, 48, 62 and 76. Releases then come roughly every two weeks after the FY26 result.
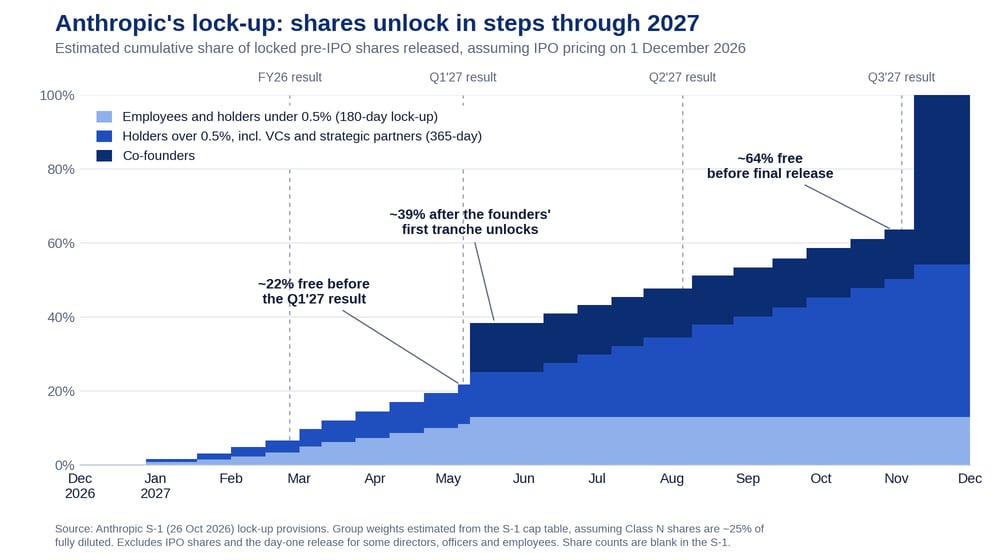
Still, there's a big argument that the IPO is just exit liquidity, as private markets have already funded Anthropic with some $120 billion (or over 50x what the five most successful public companies in the world today raised before they went public).
The bottom line
There are a lot of moving parts to the Anthropic IPO. It’s listing at an eye-watering, SpaceX-like valuation with arguably more losses ahead, and the prospectus spends more time flagging risks than describing the business. But while it’s easy to pick holes in the mega IPO, SpaceX is a reminder that a hefty price tag doesn’t have to end badly. Its shares are trading at $146.90, about 9% above the $135 IPO price since debuting on 12 June. We’ll just have to see where the dust settles.